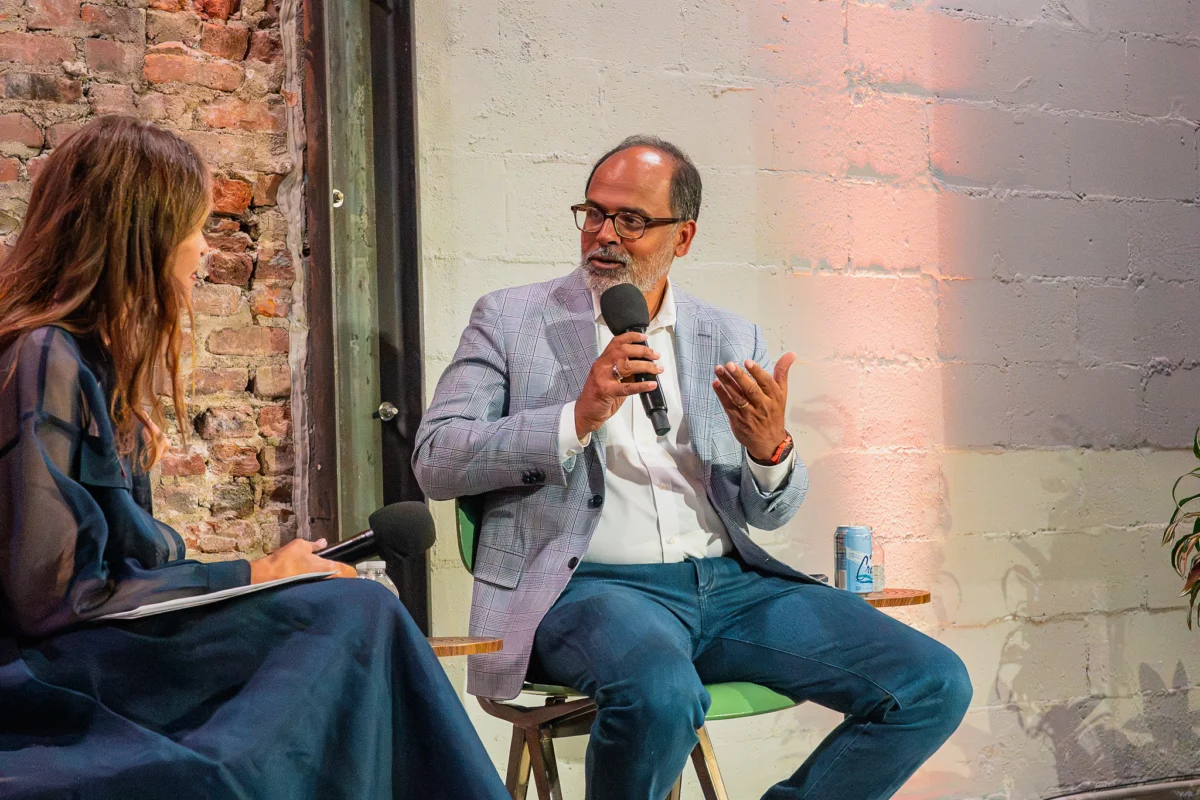
Devin Parekh, who has co-helmed the formidable investment firm Insight Partners for an impressive 26 years, offered a rare glimpse into the strategies and philosophies underpinning one of the venture capital world’s most successful, yet comparatively low-profile, players. Unlike many contemporaries who maintain a ubiquitous presence across social media platforms like X and frequent podcast appearances, Parekh and Insight Partners have consistently opted for a more understated approach, allowing their extensive portfolio to underscore their market impact. This candid exchange occurred during a recent sit-down with TechCrunch at its StrictlyVC event held on Thursday night in New York, where Parekh delved into the firm’s significant triumphs, notable near-misses, the complex dynamics of venture investing conflicts, and the rationale behind Insight’s steadfast commitment to a diversified strategy amidst a fervent industry-wide pivot towards frontier AI labs.
The interview, edited for conciseness and clarity, revealed a strategic mind deeply engaged with the technological and economic currents shaping the future of innovation. With approximately $90 billion in assets under management, Insight Partners operates on a scale that few can match, yet its public persona remains deliberately subdued, a stark contrast to the often-boisterous world of venture capital.
The Philosophy of Understatement: Letting the Portfolio Speak
Parekh articulated Insight Partners’ distinctive ethos by stating, "Every venture capitalist thinks they’re an expert on everything now — epidemiology during COVID, geopolitics during the Iran war. I’m not sure we’re all experts on everything. Our attitude has been: Let the portfolio do the talking." This philosophy underpins the firm’s operational model, prioritizing substantive investment performance over public grandstanding. For decades, Insight Partners has cultivated a reputation for its strategic "scale-up" approach, providing not just capital but also operational expertise to help growth-stage software and technology companies expand rapidly.
This deliberate quietness is not a sign of inactivity but rather a calculated strategy. The firm’s long list of successful investments, including leading and co-leading numerous rounds in data and AI giant Databricks, and holding significant stakes in foundational AI companies like OpenAI and Anthropic, serves as a testament to this approach. Databricks, for example, has grown to become one of the most valuable private software companies globally, with a valuation exceeding $43 billion, a trajectory Insight has significantly influenced. This track record, Parekh argues, communicates more effectively than any pronouncement on social media or in a podcast studio. The emphasis is on supporting founders and companies to achieve their potential, believing that their collective success ultimately defines Insight’s own.
Navigating the AI Frontier: Weighing Risks Against Transformative Potential
The conversation inevitably turned to artificial intelligence, specifically addressing the burgeoning debate around AI risk, intensified by recent high-profile departures of researchers from leading AI labs due to safety concerns. Parekh acknowledged the validity of some anxieties, citing the theoretical risk of a non-state actor misusing an open-source model to develop biological weapons. However, he swiftly juxtaposed this with the immense potential for positive societal transformation.
"There’s an even higher probability we get a massive decrease in the time it takes to develop new drugs and cure diseases. I’ll take that bet," Parekh asserted. Drawing on his experience as a board member at NYU Langone, he highlighted the tangible benefits already being realized in healthcare. AI’s capacity to analyze vast datasets—such as 50 million patient records—enables unprecedented predictive diagnostics, potentially identifying individuals at high risk for conditions like heart attacks even when presenting for unrelated issues. This capability is not merely an incremental improvement but a paradigm shift, promising to scale healthcare services dramatically at a time when an aging global population faces a critical shortage of medical professionals.
Parekh framed AI risks within a historical context, noting that "Every generation has new risks, and somehow, over time, the world still raises living standards." He argued that the benefits, particularly in critical sectors like healthcare, are too profound to ignore, making the calculated risks worth taking. This perspective aligns with a broader segment of the tech industry that views AI as a powerful tool for human advancement, albeit one that requires careful governance and development.
The Intricacies of Investing in Rival AI Giants
One of the most intriguing aspects of Insight Partners’ AI strategy is its simultaneous investment in two of the leading generative AI companies: OpenAI and Anthropic. This move, which would have been considered taboo in traditional venture capital, particularly at earlier stages, prompted internal debate within the firm. Parekh clarified Insight’s rationale, distinguishing between early-stage and later-stage investments.
"The internal debate was more about whether we should have gotten into earlier rounds," he explained. He elaborated that an early-stage investor, such as Khosla Ventures in OpenAI’s Series A, would be precluded from investing in a direct competitor like Anthropic due to governance involvement and potential information-sharing conflicts. However, at a later stage, where Insight typically enters, the dynamic shifts. "Once you’re at a later stage, off the board, not driving governance, you’re just buying a great stock," Parekh stated. This perspective views later-stage investments as more akin to public market positions, where the primary objective is capital appreciation from established companies.
The landscape for these foundational AI models is also evolving rapidly. As companies like OpenAI and Anthropic seek to raise tens of billions of dollars, their ability to dictate exclusivity diminishes. Parekh noted that while the firm maintains strict information-sharing restrictions and avoids investing in direct competitors at the Series A/B stage, the lines blur at later stages, especially when companies’ strategies, initially distinct (e.g., OpenAI as consumer-focused, Anthropic as enterprise-focused), begin to converge. This nuanced approach allows Insight to capitalize on the growth of the leading players in a transformative sector without violating ethical boundaries at critical early stages.
When it comes to the nascent field of "physical AI" or robotics, Parekh expressed a more cautious stance, characterizing many such companies as "still largely science projects." While acknowledging their long-term potential, he indicated that Insight prefers to observe rather than make early, highly speculative bets. This pragmatic view contrasts sharply with the enthusiasm of younger VCs, including his 23-year-old son, who see physical AI as the next frontier. This intergenerational difference in investment philosophy highlights the tension between established, risk-averse strategies and the bold, often unproven, visions of emerging technologies.
The Power of Diversification in a Concentrated Market
Insight Partners’ robust AUM of $90 billion is deployed across a multifaceted strategy that encompasses early-stage, growth equity, buyouts, and secondaries, reflecting a flexible and opportunistic approach. Parekh emphasized that the allocation across these stages is "temporal, not fixed," adapting to global market conditions rather than adhering to rigid percentages.
Currently, the high interest rate environment has made buyouts less attractive, particularly for software companies, due to reduced debt market receptiveness and lower exit multiples. Insight has not undertaken a major buyout since 2024, signaling a strategic pause in this area. Conversely, the venture side has witnessed a rapid resurgence in valuations, reminiscent of the frothy 2021 market, a period that "didn’t end well" according to Parekh. He noted a concerning trend where rounds are closing so quickly that there is "almost no incremental data," meaning investors are paying higher prices without a corresponding reduction in risk.
This dynamic has led Insight to lean into earlier-stage investments, where a "scale fund" can make smaller initial bets—such as a $20-25 million check instead of $500 million—and then aggressively double down on proven winners. The success story of Wiz, a cloud security startup, exemplifies this strategy. Insight invested in Wiz’s Series A and continued to inject capital, resulting in a significantly larger gain than if they had stopped at the initial check. Moreover, the inherent diversification of a large fund means that an unsuccessful smaller bet would "barely dent" its overall performance.
This diversified strategy stands in stark contrast to the growing trend of concentrated funds, particularly those heavily focused on a few frontier AI labs. Parekh highlighted the concerns of Limited Partners (LPs) regarding concentration risk. He cited examples of funds raising capital with pitches explicitly stating that 35-40% of their fund would be allocated to just one or two major AI companies. While acknowledging the potential for exceptional returns from such concentrated bets, as demonstrated by firms like Founders Fund and Thrive Capital, Parekh stressed that "this business has always rewarded diversification over a long horizon." For a firm like Insight, now on its 13th fund, a long-term perspective dictates against excessive concentration, a sentiment largely shared by most LPs seeking balanced exposure.
Global Talent and Competitive Landscapes
As a global investor, Insight Partners observes distinct patterns in talent distribution. Parekh noted that while "talent has gone flat globally" across many sectors, allowing for investment opportunities in diverse geographies—illustrated by Insight’s competitive bid for AI legal-tech company Legora in Stockholm, which they ultimately lost to General Catalyst—AI infrastructure talent remains heavily concentrated in San Francisco. This geographical pull is so strong that even Parekh’s 23-year-old son, also a VC, is relocating there, convinced that "you can’t invest in AI without being there."
However, this concentration varies by vertical. Financial services talent, for instance, is largely centralized in New York, enabling companies like Ramp to thrive there. This indicates that while foundational AI development may be geographically constrained, the application of AI in specific industries can foster more diverse investment landscapes. The loss of Legora, though a setback, was attributed by Parekh to General Catalyst’s superior articulation of their value proposition, a common competitive dynamic in high-stakes venture deals.
The Critical Imperative of LP Liquidity and Market Timing
The conversation also touched upon the crucial, often overlooked, aspect of Limited Partner (LP) liquidity. Parekh pointed out a significant issue stemming from the capital deluge of 2021-2023: many funds raised substantial amounts but have yet to return capital to their LPs. This lack of liquidity, measured by the Distributed to Paid-in Capital (DPI) ratio, is a looming threat for many first and second-time funds, potentially hindering their ability to raise subsequent funds.
Insight Partners, having learned from its own early experiences, now prioritizes liquidity. Parekh advises fund managers to de-risk positions even if a company is projected for further growth. "LPs want to know you can turn positions into cash; that’s the job," he stated. Over the past two years, Insight has returned over $20 billion to LPs through strategic sales and IPOs, with billions more anticipated, underscoring their commitment to delivering tangible returns. This proactive approach ensures LP confidence and sustained access to capital for future funds.
The concept of a "narrow window" for founders to sell into peak valuations, popularized by VC Elad Gill, resonates with Parekh. He consistently advises founders to consider de-risking 10-20% of their holdings when valuations become "frothy," acknowledging that market corrections are inevitable, even if their timing is unpredictable. He cautioned against the unsustainable math of continuous exponential growth, particularly for companies valued in the tens of billions.
The Dawn of a New IPO Era and Market Cycles
The anticipated public listings of Anthropic and OpenAI are poised to redefine the industry’s perception of growth and scale. Parekh highlighted Anthropic’s staggering achievement of becoming larger than Salesforce within just four years. He predicted a wave of "three companies—SpaceX, Anthropic, OpenAI—going public within six to eight months, each north of a trillion dollars in market cap." The public market’s absorption of SpaceX’s massive valuation suggests a readiness for such large-scale tech IPOs.
The real implication, however, lies in the bar these behemoths will set for the "next tier" of companies. Public market investors, witnessing companies achieve zero-to-$65 billion valuations in four years, may find traditional "double, double, triple, triple" growth rates less exciting by comparison. While these hyper-growth rates cannot persist indefinitely, the public markets provide the necessary mechanism for these companies to transition into "normal-growth companies." Parekh anticipates an increase in such high-profile IPOs over the next 18 months, signaling a potential shift in market dynamics and investor expectations.
This influx of LP money flowing back into the system could fuel further market frenzy. Parekh observed the cyclical nature of investment behavior, mirroring individual investors who "pile in right when we should be pulling back." LPs, too, exhibit this macro-level behavior, rushing into markets before 2021, retreating, and now re-entering. This boom-bust cycle is difficult to avoid, leading to a proliferation of large venture-growth funds, once rare, now becoming commonplace.
Strategic Portfolio Management: Doubling Down and Course Correction
Insight Partners’ rigorous approach to portfolio management is evident in its comprehensive review process, where 300 portfolio companies are assessed over three days. This allows the firm to not only monitor major positions but also identify companies at an "inflection point" where doubling down, buying secondary shares, or even pulling back is warranted.
Examples abound: Wonderful, an enterprise AI agent platform, achieved a $5 billion valuation within two years, warranting rapid follow-on investments. In contrast, some investments made in 2021 languished for three or four years before finding product-market fit. The firm’s ability to adapt its strategy based on real-time performance is crucial.
The case of Armis, a security company, perfectly illustrates Insight’s long-term relationship-building and strategic opportunism. After losing the initial Series A deal to Sequoia, an Insight partner maintained a connection, eventually making a small $5 million investment from a much larger fund. Eighteen months later, Insight acquired the entire cap table, including Sequoia’s stake, for a nine-figure sum, and subsequently sold Armis to ServiceNow for $7 billion. This demonstrates that success can come from both small, strategic checks and large, decisive acquisitions. The ultimate goal remains consistent: identifying and backing the "best founders in the best markets."
Devin Parekh’s insights reveal a firm that, despite its immense scale, maintains a disciplined, adaptive, and founder-centric approach. In an industry often characterized by public spectacle, Insight Partners quietly continues to shape the future of technology, guided by a belief in the enduring power of performance over proclamation, and diversification over concentrated risk.