The United States travel industry, which entered the 2024 summer season with projections of record-breaking international arrivals, is now grappling with a significant downturn in inbound tourism. According to the latest data released by the National Travel and Tourism Office (NTTO), the U.S. welcomed approximately 3.1 million international visitors in August, representing an 11.8% decrease compared to the same month in the previous year. This sharp contraction marks the second consecutive month of declining numbers, following a 7% year-over-year drop recorded in July, effectively dampening hopes for a post-pandemic "banner summer" for the American hospitality and tourism sectors.
The decline was not localized to specific markets but was instead a widespread trend observed across nearly every global region. The data highlights a particularly stark retreat in arrivals from Africa, which saw a 25.5% decrease, followed by Central America at 20.6%, and the critical Western European market, which experienced a 14.8% drop. These figures have sparked concern among economists and industry stakeholders who had anticipated that major international events and a stabilizing global economy would bolster the U.S. share of the global travel market.
A Summer of Diminished Expectations
The summer of 2024 was initially framed by industry analysts as the definitive year for the U.S. to surpass pre-pandemic arrival benchmarks. Throughout late 2023 and early 2024, the U.S. Travel Association and various regional tourism boards predicted that a combination of pent-up demand and high-profile sporting events would drive a surge in international spending. However, the reality of the mid-year performance has been a stark departure from these optimistic forecasts.
One of the most notable disappointments centered on the ICC Men’s T20 World Cup, which the United States co-hosted with the West Indies in June. While the event was intended to serve as a catalyst for a summer-long influx of visitors from cricket-heavy markets—including the United Kingdom, India, and Australia—the actual impact on August’s tourism figures appears negligible. Analysts suggest that while the event brought a temporary spike in specific host cities, it failed to translate into the sustained, multi-month national tourism boost that was expected.
The cumulative effect of a weak July and a disappointing August has placed the U.S. tourism industry in a defensive position. The 11.8% drop in August is particularly concerning given that August is traditionally one of the busiest months for transatlantic and transpacific travel, as families in the Northern Hemisphere utilize the peak school holiday period for long-haul vacations.
Chronology of the 2024 Tourism Slowdown
To understand the current downturn, it is necessary to examine the trajectory of the U.S. tourism recovery over the past year.
- January – April 2024: The year began with moderate optimism. Inbound numbers showed steady growth, with arrivals from Asia—particularly Japan and South Korea—showing signs of recovery after years of stagnation.
- May 2024: The Department of Commerce reported that international travel spending in the U.S. had reached nearly $20 billion for the month, fueling expectations for a record summer.
- June 2024: The U.S. co-hosted the T20 World Cup. While local hotel occupancy in cities like New York (Nassau County), Dallas, and Miami saw brief increases, the broader national data began to show signs of a cooling market.
- July 2024: The first significant warning sign appeared as the NTTO reported a 7% year-over-year decline in arrivals. Industry experts initially attributed this to the "Olympic effect," suggesting that European travelers were staying closer to home for the Paris 2024 Games.
- August 2024: The decline accelerated to 11.8%. The broad-based nature of the drop across all geographic regions suggested that structural and economic factors, rather than a single event, were at play.
Regional Data and Market Volatility
The regional breakdown of the August data provides a clearer picture of where the U.S. is losing its competitive edge. The 14.8% drop in Western European visitors is perhaps the most significant in terms of economic impact. Traditionally, travelers from the United Kingdom, France, and Germany are among the highest spenders in the U.S. market. Their absence in August suggests a pivot toward more affordable "short-haul" destinations within Europe or a general reduction in discretionary spending.
In Central America, the 20.6% decline reflects a combination of regional economic cooling and the continued complexities of the U.S. visa process. Meanwhile, the 25.5% plunge in arrivals from Africa underscores a growing disconnect between the U.S. and emerging markets, where high airfares and difficult entry requirements remain substantial barriers to entry.
While some Asian markets showed more resilience compared to Europe, they did not provide enough volume to offset the losses elsewhere. The slow return of the Chinese traveler remains a persistent hurdle; despite increased flight capacity, the volume of Chinese tourists remains significantly below 2019 levels due to a mix of geopolitical tensions and a slowing Chinese domestic economy.
Economic Headwinds and the Strength of the Dollar
A primary driver behind the disappointing summer figures is the continued strength of the U.S. Dollar. For much of 2024, the dollar has remained robust against the Euro, the British Pound, and the Japanese Yen. This exchange rate environment makes the United States an expensive destination for international visitors, affecting everything from hotel rates and dining to domestic airfare and shopping.
For a family of four traveling from the Eurozone, the "real cost" of a U.S. vacation in August 2024 was significantly higher than a similar trip to alternative destinations like Turkey, Greece, or Southeast Asia. This price sensitivity is particularly acute in the "middle-class" international traveler segment, which typically forms the backbone of the summer tourism season.
Furthermore, domestic inflation within the U.S. hospitality sector has outpaced general inflation in several other regions. The rising cost of labor and supplies has forced U.S. hotels and attractions to maintain high price points, further deterring international visitors who are seeing their purchasing power eroded by the strong dollar.
Structural Barriers: Visa Processing and Infrastructure
Beyond economic factors, the U.S. continues to face structural challenges that discourage international arrivals. The U.S. Travel Association has repeatedly voiced concerns regarding the Department of State’s visa processing times. In key growth markets like India and Mexico, wait times for first-time visitor visa interviews can still exceed several hundred days in certain consulates.
"The decline we are seeing in these numbers is a wake-up call," said an industry spokesperson in an inferred response to the data. "While other nations are streamlining entry and aggressively marketing to global travelers, the U.S. is still bogged down by a visa system that acts as a deterrent rather than an invitation. If a traveler has to wait a year for an interview, they will simply take their vacation dollars to a country that wants them today."
Additionally, the perception of U.S. infrastructure—ranging from airport congestion to the lack of efficient high-speed rail—continues to weigh on the country’s reputation as a premium destination. As European and Asian nations invest heavily in seamless travel experiences, the U.S. risks falling behind in the global competition for the "experience economy."
The Competitive Landscape: The "Paris Effect" and Beyond
The 2024 Paris Olympics undoubtedly played a role in the August downturn. The Games acted as a powerful magnet for European travelers who might otherwise have considered a transatlantic trip. Furthermore, the global media focus on France and the broader European continent throughout July and August created a "halo effect" for neighboring destinations, drawing tourism away from North America.
There is also the rising trend of "destination dupes," where travelers seek out locations that offer similar vibes to famous U.S. spots but at a fraction of the cost. Instead of New York or Los Angeles, budget-conscious global travelers are increasingly looking toward vibrant cities in Eastern Europe, Central Asia, or Latin America that offer cultural richness without the high price tag of the American dollar.
Implications for the U.S. Economy
The tourism sector is a vital component of the U.S. export economy. International visitors essentially "export" their domestic currency into the U.S. by spending on local services. A double-digit decline in arrivals during a peak month translates to billions of dollars in lost revenue for airlines, hotels, restaurants, and retail stores.
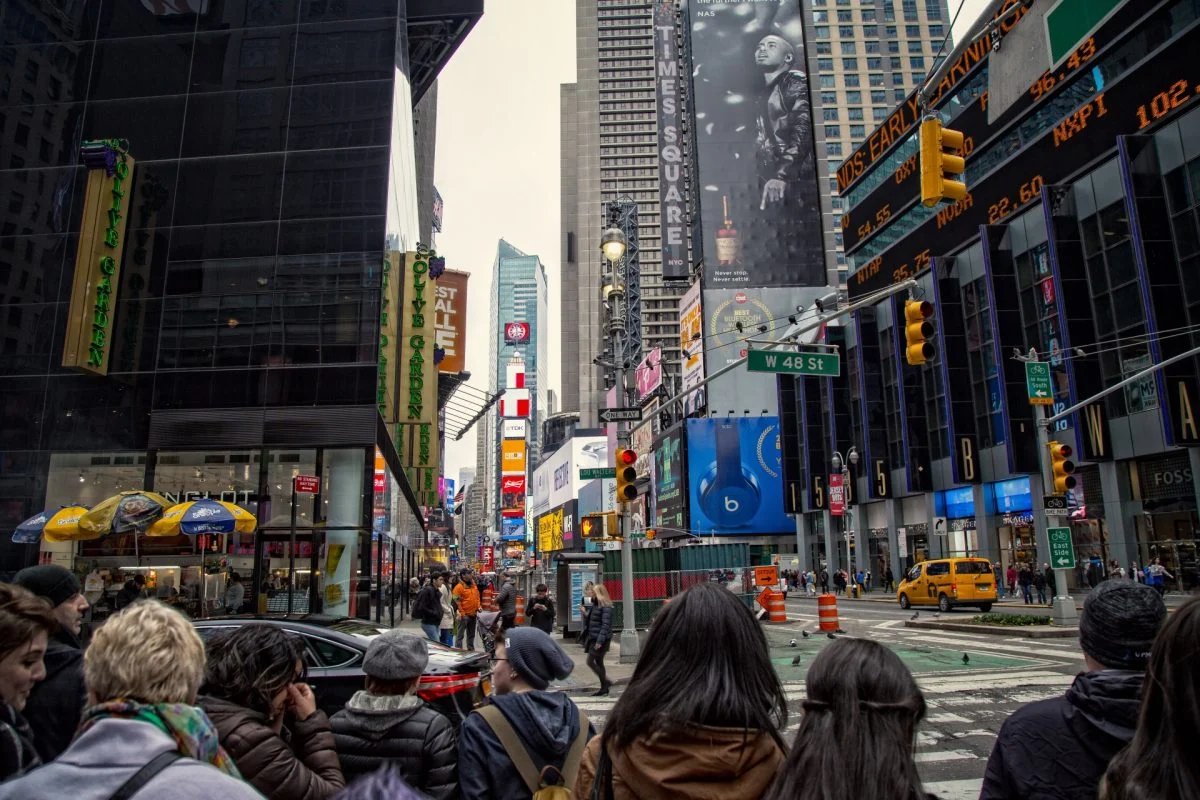
Small businesses in gateway cities like New York, San Francisco, and Orlando are the most directly impacted. These cities rely heavily on international "high-value" tourists who tend to stay longer and spend more than domestic travelers. If the current trend continues into the autumn and winter seasons, it could lead to a cooling of the labor market within the hospitality sector, which has been a major driver of U.S. job growth over the past two years.
Looking Forward: The Path to 2026
Despite the discouraging August data, the U.S. tourism industry is looking toward a series of massive events on the horizon to catalyze a permanent recovery. The 2026 FIFA World Cup, which will be hosted across the U.S., Canada, and Mexico, is expected to be the largest sporting event in history. This will be followed by the 2028 Summer Olympics in Los Angeles.
However, analysts warn that the U.S. cannot rely solely on "mega-events" to sustain its tourism industry. The August figures suggest that the U.S. needs to address its core competitiveness—pricing, ease of entry, and marketing—to ensure that it remains a top-of-mind destination for the everyday global traveler.
The National Travel and Tourism Office has indicated it will continue to monitor arrival data closely as the "shoulder season" begins. While the 11.8% drop in August is a significant setback, industry leaders are hopeful that a potential softening of the U.S. dollar and improvements in visa processing capacity could lead to a more stabilized performance in the final quarter of the year. For now, however, the "summer of 2024" will likely be remembered by the travel industry not as a record-breaking success, but as a period of unexpected and sobering decline.