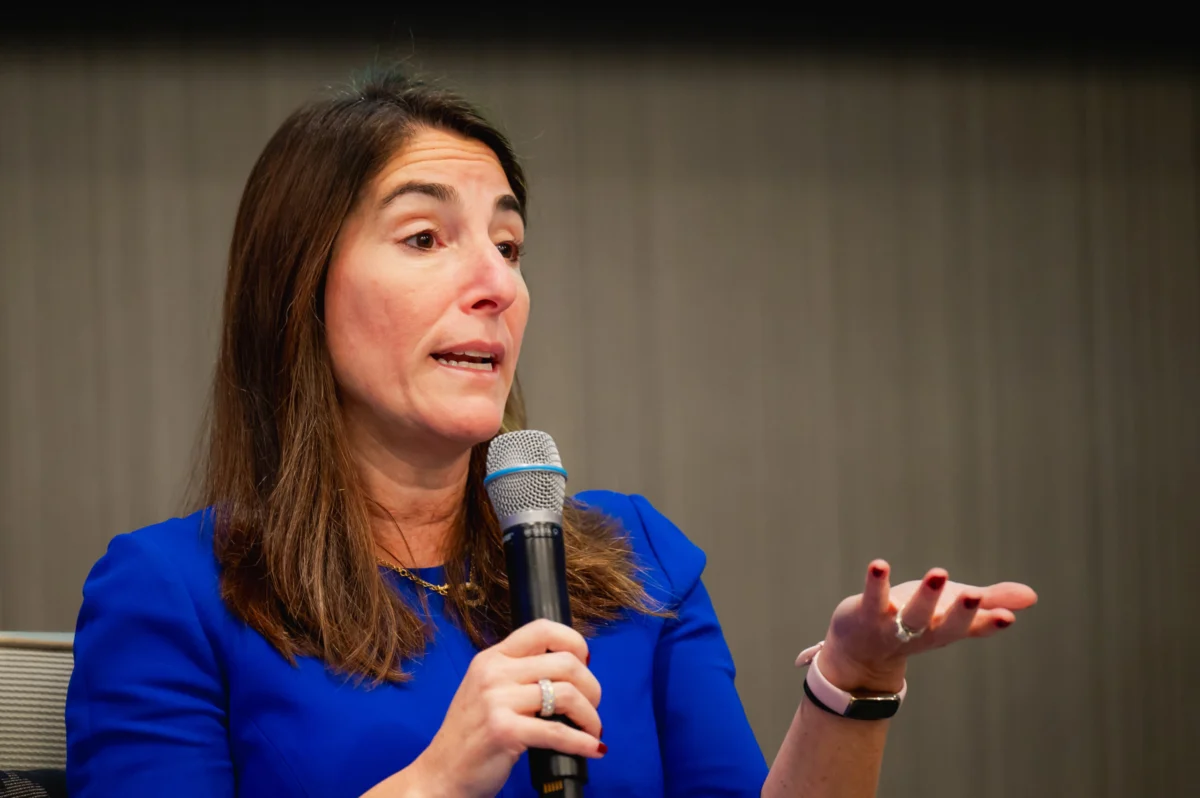
Three influential Federal Reserve officials publicly broke ranks this week, casting dissenting votes against the Federal Open Market Committee’s (FOMC) decision to maintain the benchmark interest rate at its current range. Cleveland Fed President Beth Hammack, Minneapolis Fed President Neel Kashkari, and Dallas Fed President Lorie Logan all argued for immediate interest rate hikes, citing the urgent need to combat stubbornly high inflation that has persisted above the Fed’s 2% target for over five years. Their dissent, revealed in statements issued on Friday, October 31, 2025, underscores a growing internal debate within the central bank regarding the appropriate course of action to restore price stability to the American economy.
The FOMC ultimately voted 9-3 to hold the federal funds rate in a range between 3.5% and 3.75%. This decision marked a continuation of a policy stance that has seen rates remain steady throughout much of 2025, following a series of three targeted rate cuts implemented in late 2024. However, the explicit calls for tightening from three regional Fed presidents signal a significant divergence of opinion, potentially foreshadowing a more hawkish shift in monetary policy in the coming months.
The Urgent Call for Action: Voices from the Dissenters
Cleveland Fed President Beth Hammack, a prominent voice among the dissenters, articulated her conviction that proactive measures are paramount. "In my view, now is the time for the [Federal Open Market Committee] to act to speed the return of PCE inflation to our 2 percent objective and deliver on our commitment to price stability for the American people," Hammack declared in her statement. Her reasoning centered on the escalating costs of inaction: "The longer that high inflation persists, the more challenging and costly it can be to bring it back down." Hammack further emphasized that she is "not confident it will return to our objective on its own," challenging the notion that current economic dynamics or unforeseen external factors would naturally cool price pressures.
The industrial heartland represented by the Cleveland Fed district, home to a diverse array of manufacturing and service industries, is particularly sensitive to both input costs and consumer purchasing power. Hammack’s firsthand accounts from constituents underscore the tangible impact of sustained price increases, describing a widespread "pricing pressures as broadening rather than fading, and consumers are expressing despair over persistently higher prices." This anecdotal evidence, gathered from businesses and households within her district, painted a picture of inflationary pressures not confined to specific sectors but permeating the broader economy, indicating both demand-side and supply-side factors at play.
Echoing Hammack’s urgency, Minneapolis Fed President Neel Kashkari advocated for a strategy of gradual, preemptive tightening. "In my view, a potential series of small policy moves would be better than waiting and eventually concluding that even bolder actions were necessary," Kashkari stated. His comments drew parallels to historical periods of entrenched inflation, implicitly referencing the "Great Inflation" of the 1970s and early 1980s, when the Federal Reserve’s initial reluctance to act decisively against rising prices led to a prolonged and painful battle against inflationary expectations. Kashkari’s stance also resonates with the more recent debate following the COVID-19 pandemic, where many central bankers initially characterized burgeoning inflation as "transitory"—a temporary phenomenon largely driven by supply chain disruptions and pent-up demand. This historical lesson, Kashkari suggests, underscores the risk of delayed action.
While acknowledging the complexity of inflation driven by supply shocks, Kashkari argued that monetary policy still plays a crucial role. "Economic theory argues that monetary policy is the right tool to address demand-driven inflation but faces greater trade-offs when dealing with supply shocks," he noted. However, he added a critical qualification: "I increasingly believe that monetary policy does have an important role to play in addressing a series of successive supply shocks that might lead to entrenched higher inflation." This nuanced perspective suggests that while the Fed cannot directly fix supply chain issues or geopolitical disruptions, it must prevent these shocks from translating into a self-reinforcing cycle of rising wages and prices—a phenomenon known as an inflationary spiral.
Dallas Fed President Lorie Logan, whose full statement explaining her vote was anticipated later Friday morning, also dissented, asserting that current monetary policy is insufficient to restrain the economy. "Labor, consumption and financial market conditions indicate that monetary policy is not restraining the economy," Logan observed. Her analysis implies that despite the current federal funds rate, economic activity remains robust, allowing inflation to persist. Logan emphasized the need for the Fed to be proactive rather than reactive, stating, "Without any policy restraint, inflation will likely continue to trend above target until there’s an unanticipated shock." The Dallas Fed district, a powerhouse in the energy sector, provides Logan with a unique vantage point on global commodity markets, which have been a significant driver of recent inflation. Her perspective likely reflects the persistent upward pressure on energy costs that continues to ripple through the economy.
The FOMC’s Stance and Chairman Warsh’s Nuance
The 9-3 vote to hold rates steady, while reflecting a consensus among the majority of FOMC members, highlights the inherent complexities and differing interpretations of economic data within the central bank. The FOMC, composed of 12 voting members—seven governors of the Federal Reserve System, the president of the Federal Reserve Bank of New York, and presidents of four other regional Federal Reserve Banks on a rotating basis—often strives for a unified front. However, the public dissent by three regional presidents, particularly on an issue as critical as inflation, signals a robust internal debate.
Federal Reserve Chairman Kevin Warsh, despite voting in favor of the hold, acknowledged the persistent inflation challenge and reiterated his commitment to achieving the 2% target. "We have begun a new chapter, and we understand that the five-plus years of inflation above target cannot be cured in nine weeks – or by a single month of modest price decreases," Warsh stated. His remarks suggest a cautious approach, recognizing the deeply entrenched nature of current price pressures while perhaps hoping that the cumulative effects of past actions and evolving economic conditions might eventually bring inflation down without immediate further tightening. This stance implies a belief that the current policy is restrictive enough, given time, or that the risks of over-tightening might outweigh the benefits of an immediate hike.

A Persistent Inflationary Landscape: Drivers and Dynamics
The backdrop to this internal Fed debate is an inflationary environment that has proven far more stubborn than initially anticipated. For over five years, the Personal Consumption Expenditures (PCE) price index, the Fed’s preferred inflation gauge, has consistently hovered above its 2% target, a period of sustained price pressure not seen in decades. After briefly dipping to 3.5% in June amidst a temporary easing of Middle East tensions, the PCE index rebounded sharply to 4.2% in October, reigniting fears that inflation was becoming deeply entrenched. Core PCE, which strips out volatile food and energy prices, also remained elevated, signaling broad-based price increases.
The resurgence of inflation this year has been significantly influenced by a confluence of geopolitical and economic factors. The escalation of the Iran war, in particular, has sent ripples through global energy markets, leading to substantial increases in crude oil and natural gas prices. For instance, West Texas Intermediate (WTI) crude oil, which had briefly eased to around $80 per barrel in June, surged back above $90 per barrel in October, directly impacting transportation costs, utility bills, and the price of goods across various sectors.
Compounding these supply-side shocks, the impact of President Donald Trump’s tariffs, reintroduced or expanded on various imported goods, has also contributed to upward price pressures. Tariffs, essentially taxes on imports, increase the cost of foreign goods, which producers often pass on to consumers. This protectionist trade policy, aimed at bolstering domestic industries, inadvertently acts as an inflationary impulse, adding to the burden faced by consumers and businesses already grappling with elevated costs.
The Demand vs. Supply Debate and Monetary Policy Effectiveness
A central tenet of the debate within the Fed revolves around the nature of current inflation—is it primarily driven by robust demand or constrained supply? Hammack, while acknowledging supply-side factors like energy prices, explicitly pointed to "inflationary pressures coming from the demand side of the economy, as well." This suggests that even with the current interest rates, consumer spending and business investment might still be too strong, outstripping the economy’s capacity to produce goods and services efficiently. Real GDP growth, for example, has remained surprisingly resilient, hovering around 2.0-2.5% in 2025, defying predictions of a significant slowdown and potentially validating the view that the economy is not adequately restrained.
Kashkari’s comments further complicate this picture by acknowledging the significant role of successive supply shocks. Historically, monetary policy, primarily through interest rate adjustments, is most effective at taming demand-driven inflation. By making borrowing more expensive, the Fed can cool aggregate demand, thereby reducing price pressures. However, when inflation is predominantly driven by external supply-side factors—such as geopolitical conflicts impacting energy, or tariffs affecting import costs—the effectiveness of interest rate hikes becomes more nuanced. Raising rates in response to supply shocks risks stifling economic growth without directly addressing the root cause of the inflation, potentially leading to a period of "stagflation" (high inflation and stagnant growth). Yet, Kashkari argues that if these successive supply shocks lead to "entrenched higher inflation" by altering wage-price dynamics and inflation expectations, then monetary policy must indeed play a role to prevent these temporary shocks from becoming permanent features of the economic landscape.
Implications and The Road Ahead
The public dissent by three regional Fed presidents, particularly after a prolonged period of high inflation, sends a strong signal to financial markets and the broader economy. While not unprecedented, such explicit disagreements can introduce an element of uncertainty regarding the future trajectory of monetary policy. Investors, who typically prefer clear and unified messaging from the central bank, may interpret this divergence as a sign of potential future volatility or an increased likelihood of rate hikes at upcoming meetings. Futures markets, which had largely priced in a prolonged pause, might begin to recalibrate, reflecting a higher probability of tightening moves in late 2025 or early 2026. This could translate into higher borrowing costs for consumers and businesses, impacting everything from mortgage rates to corporate investment decisions.
The broader economic implications of potential rate hikes are significant. While aimed at curbing inflation, higher interest rates can slow economic growth, potentially increasing unemployment. The current U.S. labor market, with unemployment hovering around a robust 3.8%, might be able to absorb some of this tightening, but the risk of tipping the economy into a recession remains a constant concern for policymakers.
For the Federal Reserve, maintaining its credibility as an inflation fighter is paramount. After years of above-target inflation, the public’s confidence in the Fed’s ability to achieve its dual mandate of maximum employment and price stability has been tested. The dissenting votes underscore the urgency of this challenge and the internal pressure to demonstrate a firm commitment to price stability.
As the FOMC prepares for its next meeting, policymakers will be scrutinizing a range of economic indicators. Key data points such as the Consumer Price Index (CPI), Personal Consumption Expenditures (PCE) inflation, employment reports including wage growth, and consumer sentiment surveys will be critical in shaping future decisions. The evolution of geopolitical tensions and commodity prices, particularly energy, will also weigh heavily on their minds. The recent dissent suggests that the debate over the appropriate path forward is far from settled, and the coming months could see the Federal Reserve grapple with some of its most challenging policy choices in recent memory as it strives to bring inflation back to its target without unduly harming economic growth. The path to price stability, it appears, is proving to be a highly contentious and complex journey.