BEIJING – The battleground of China’s automotive industry has undergone a seismic shift, with a select cohort of brands demonstrating remarkable resilience and strategic acumen to not only survive but thrive in a landscape increasingly dominated by electric-powered vehicles. This dynamic environment, characterized by intense innovation, aggressive pricing, and evolving consumer preferences, has reshaped the hierarchy, pushing domestic electric vehicle (EV) manufacturers to the forefront while challenging established global players. The transformation is unfolding against a backdrop of a broader market contraction, making the success of these emerging leaders even more pronounced.
The Shifting Sands of Consumer Preference and Market Dynamics
The first half of 2026 has provided a stark illustration of this evolving market, as detailed by industry data from Autohome. While the overall passenger car market experienced a significant downturn, tumbling by 20.3% year-on-year through July, and new energy vehicle (NEV) sales, encompassing battery and hybrid-powered cars, also saw a 12.5% drop in the same period, the underlying trend toward electrification remains undeniable. NEVs accounted for a staggering 65.1% of new passenger cars sold in July, a substantial leap from 54% just a year prior. This indicates that despite an overall tightening of consumer spending and a challenging economic climate, the transition to electric mobility is accelerating, forcing every automaker to recalibrate their strategies or risk obsolescence.
The fierce competition is fueled by several factors: robust government support for NEV development over the past decade, a burgeoning domestic supply chain for EV components, and a technologically savvy consumer base eager for cutting-edge features. This fertile ground has allowed Chinese brands to innovate rapidly, often outpacing their foreign counterparts in terms of product cycles and affordability.
Geely’s Strategic Diversification Pays Off
Leading the charge in this new era is Geely, a Hangzhou-based automotive conglomerate that has skillfully navigated the transition. Their strategy of diversification, encompassing both gasoline-powered vehicles and a robust portfolio of electric brands, has proven highly effective. Among the top 10 most popular car models sold in China in the six months through July, Geely’s Xingyuan electric hatchback emerged as the undisputed bestseller, recording nearly 197,500 units sold. Its compelling price point, just under 100,000 yuan ($14,820), underscores a critical trend: affordability is a key driver in the mass-market EV segment in China.
Geely’s success is not merely confined to budget-friendly models. The company has positioned itself as a formidable rival to market leader BYD, securing the second spot by overall China sales volume in 2025. Beyond the Xingyuan, Geely’s ecosystem includes premium electric brands like Zeekr, which targets a more affluent demographic with advanced technology and luxury features, and brands like Lynk & Co, which offer a blend of traditional and electrified powertrains. This multi-pronged approach allows Geely to capture various market segments, insulating it somewhat from fluctuations in any single category.
An industry analyst from Shanghai-based automotive consultancy, who wished to remain anonymous due to client relationships, commented, "Geely’s strength lies in its comprehensive platform strategy and vertical integration. They control significant parts of their supply chain, from batteries to software, allowing for cost efficiencies and rapid product development. The Xingyuan’s success is a testament to their ability to deliver compelling value in a price-sensitive market, while brands like Zeekr demonstrate their capacity for premium innovation."
Tesla’s Enduring Appeal and Premium Market Grip
Despite the rise of domestic contenders, Tesla continues to hold a significant and influential position in the Chinese market, particularly in the premium EV segment. The company’s Model Y electric SUV ranked second in popularity, with over 180,000 units sold in the same period. This performance is particularly noteworthy given its substantially higher price tag, ranging from 263,500 yuan to 313,500 yuan. This sales volume surpassed key rivals in its segment, including Li Auto’s i6 SUV and Xiaomi’s highly anticipated SU7 sedan, signaling strong brand loyalty and perceived value among Chinese consumers for Tesla’s technology, charging infrastructure, and brand cachet.
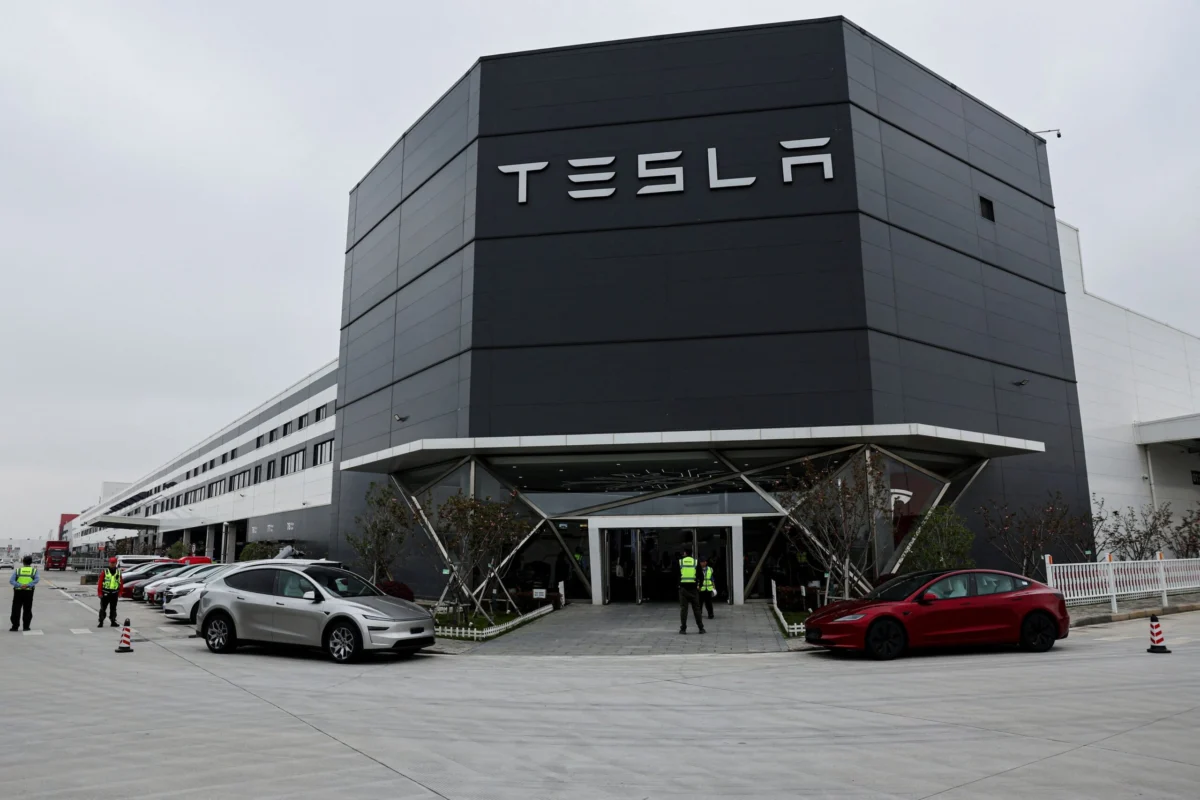
Tesla’s consistent sales performance in China, despite facing increasing domestic competition and occasional regulatory scrutiny, highlights the global appeal of its brand and its pioneering role in the EV revolution. The Shanghai Gigafactory, an exterior view of which was captured during a government-organised media trip on April 14, 2026, continues to be a crucial manufacturing hub for the company, not only serving the Chinese market but also exporting vehicles globally. The plant’s efficiency and technological advancements have been key to Tesla’s cost competitiveness and production scale in the region.
"Tesla’s Model Y maintains its strong appeal due to a combination of factors: perceived quality, access to a robust charging network, and its status as a technological leader," stated Mr. Li Wei, an automotive market researcher based in Shenzhen. "While Chinese brands are rapidly catching up in terms of features and software, Tesla’s brand equity and established ecosystem provide a significant advantage, especially in the higher-end segments where consumers are less price-sensitive and prioritize performance and brand reputation."
BYD’s Broad Volume Play and Market Challenges
BYD, the Chinese automotive giant, presents a nuanced picture. While it is often heralded as the global leader in NEV sales by volume, its individual model rankings in the intensely competitive Chinese market show a different dynamic. Three of the 10 best-selling cars between February and July were from BYD, according to Autohome data. However, the most popular among them, the modestly priced Yuan UP SUV, secured only fifth place with nearly 97,700 units sold. Its Ti 7, under BYD’s off-road brand, followed in sixth place, with the Sealion 06 SUV trailing close behind.
This distribution of sales across multiple models, rather than a single dominant bestseller, reflects BYD’s strategy of offering a vast and diversified product portfolio spanning various price points and segments, from compact city cars to luxury sedans and SUVs. This approach contributes to its overall market leadership in NEV sales volume but indicates that its individual models face stiff competition from specialized offerings by rivals.
The reported drop of more than 10% in BYD’s passenger car sales in the first half of the year, as disclosed in their August 2, 2026 filing to the Hong Kong Stock Exchange, highlights the challenging market conditions affecting even the strongest players. This dip could be attributed to intensified price wars, increased competition from new entrants, and the broader economic slowdown impacting consumer discretionary spending. Despite this, BYD’s robust export strategy and its integrated battery technology business continue to provide a strong foundation.
"BYD’s sheer scale and technological integration, particularly in battery production, give it a significant long-term advantage," explained Ms. Chen Jing, an analyst specializing in the EV supply chain. "While the domestic market is incredibly tough, their diversified product line and increasing international presence are key to their sustained growth. The H1 dip is a reflection of market pressures, not a fundamental weakness in their strategy."
Volkswagen’s Enduring Grip Amidst Electrification
In a market increasingly dominated by electric vehicles and aggressive domestic brands, Volkswagen’s performance stands out as an anomaly among traditional foreign automakers. The German automaker was the sole traditional foreign car company to secure a spot in the top 10 best-selling models, with its compact gasoline-powered Lavida ranking ninth. This achievement is significant, underscoring the enduring appeal of established brands and internal combustion engine (ICE) vehicles in certain segments, even as the market rapidly electrifies. The Lavida was sandwiched between Leapmotor’s A10 electric SUV and Geely’s gasoline-powered Boyue L SUV, illustrating the mixed landscape.
Volkswagen’s continued success with ICE models, while it rapidly invests in its own EV platforms and models for China, suggests that a substantial segment of Chinese consumers still value the reliability, brand recognition, and established service networks of legacy automakers. However, this position is increasingly precarious. Volkswagen, like other global players, faces immense pressure to accelerate its EV transition in China to remain competitive in the long run. The company has poured billions into new EV factories and R&D centers in China, signaling its commitment to adapting to the market’s new realities.
A spokesperson for Volkswagen China, speaking on condition of anonymity, acknowledged the challenges but expressed confidence in their dual strategy: "The Lavida’s continued strength demonstrates the trust Chinese consumers place in the Volkswagen brand. Simultaneously, we are making aggressive strides in our electric vehicle portfolio, with significant local investments in R&D and production. We believe our localized EV offerings, combined with our heritage, will ensure our relevance in this dynamic market."
Broader Implications and Future Outlook
The trends observed in China’s automotive market in early 2026 carry profound implications for the global industry. The rapid ascendancy of domestic EV brands like Geely and BYD, coupled with Tesla’s sustained performance, signifies a new era of competition. Traditional foreign automakers, particularly those heavily reliant on ICE vehicle sales, are under immense pressure to accelerate their electrification strategies, localize their R&D and production, and offer competitive pricing. Failure to adapt could lead to significant market share erosion in what remains the world’s largest automotive market.
The intense price wars, which have characterized the Chinese EV market for the past two years, are likely to continue, forcing manufacturers to focus on efficiency, scale, and technological differentiation. This environment will inevitably lead to consolidation, with smaller, less competitive players struggling to survive. The emphasis on affordability, as demonstrated by the success of models like the Geely Xingyuan and BYD Yuan UP, suggests that the mass-market segment will be a key battleground, complementing the ongoing innovation in premium and high-performance EVs.
Furthermore, China’s experience serves as a potential blueprint for other emerging markets and even developed economies. The government’s strategic push for NEVs, coupled with a robust domestic industry, has created a powerful ecosystem that fosters innovation and rapid adoption. The insights gained from consumer preferences, technological advancements, and business models in China are invaluable for automakers worldwide.
Looking ahead, the Chinese automotive market will likely remain a crucible of innovation and competition. The battle for market share will intensify, driven by continuous technological advancements, evolving policy landscapes, and the relentless pursuit of consumer satisfaction. The survivors of this fierce contest will be those who can best balance innovation with affordability, global ambition with local relevance, and traditional strengths with future-proof strategies. The era of the electric vehicle is not just arriving in China; it is rapidly defining the future of global mobility.