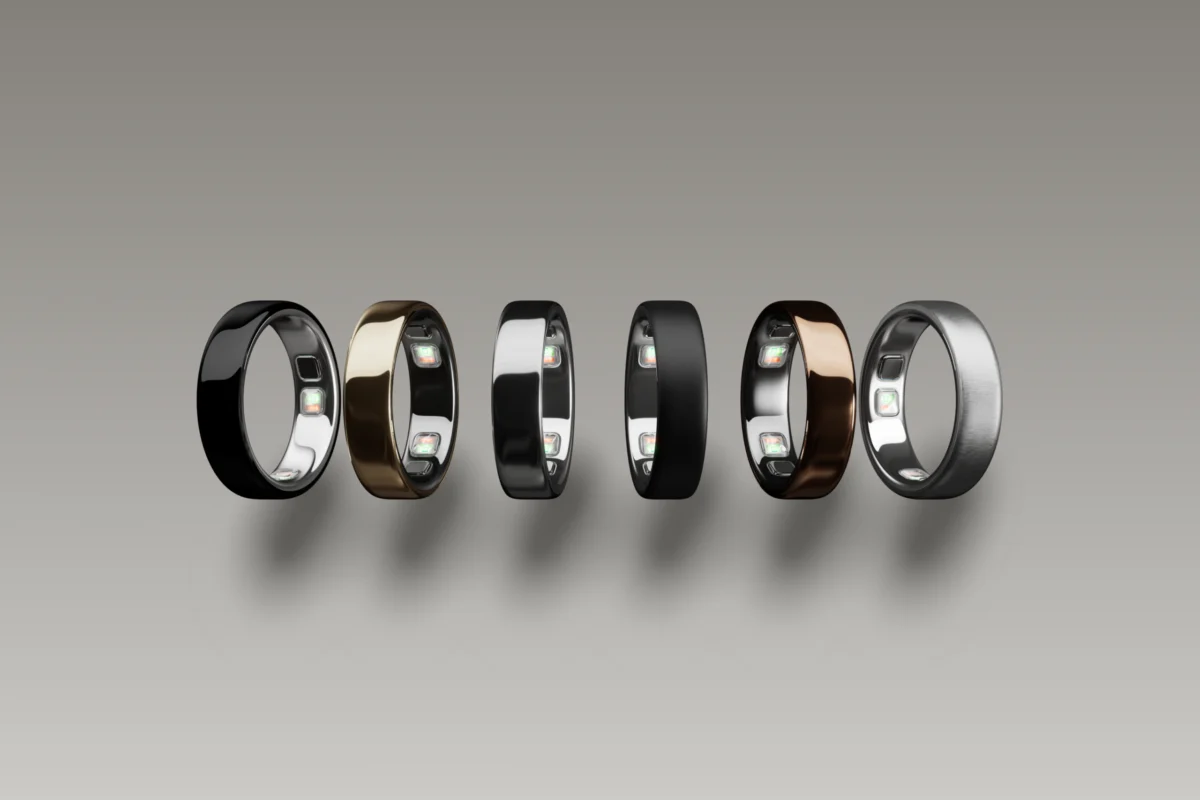
The smart ring market, once a niche dominated by a few key players, is rapidly evolving into a fiercely contested arena, prompting market leader Oura to make a strategic move. On September 3, the Finnish health tech company officially filed to go public, signaling its intent to solidify its position and fuel future growth amidst an onslaught of innovative rivals. This pivotal decision comes at a time when Oura is experiencing robust financial health, with its revenue nearly doubling to an impressive $1.21 billion for the nine months ending June 30. The company also reported selling 3.6 million rings over the past year and boasts a significant user base of approximately 5 million paid members. This strong performance, coupled with the recent successful launch of the Oura Ring 5 – its slimmest and lightest iteration to date – underscores Oura’s current momentum as it prepares for public market scrutiny.

Oura’s journey from a nascent startup to a leader in the wearable tech space has been remarkable. Founded in 2013, the company pioneered the concept of a discreet, ring-shaped device capable of tracking sleep, activity, and recovery with scientific precision. Its initial appeal lay in its ability to offer comprehensive health insights without the intrusiveness of a smartwatch or smartphone, providing users with a subtle yet powerful tool for self-monitoring. For years, Oura effectively cornered the market, establishing a loyal customer base attracted by its elegant design, sophisticated sensors, and actionable data. Its proprietary algorithms, which translate raw biometric data into personalized readiness scores and sleep stages, became a benchmark for the industry. However, the very success that propelled Oura to its current valuation has also attracted a wave of competitors, each vying for a slice of the rapidly expanding wearable market. The IPO filing is not merely a financial transaction but a declaration of intent, a bid to secure substantial capital to accelerate research and development, expand market reach, and vigorously defend its market share against an increasingly aggressive and innovative landscape.
The competitive landscape of the smart ring market is shifting dramatically, moving beyond rudimentary health and sleep tracking towards an arms race of advanced features and capabilities. New entrants are not merely replicating Oura’s success but are actively pushing the boundaries of what a smart ring can achieve, integrating functionalities traditionally associated with smartphones and smartwatches. This evolution marks a significant departure from the original minimalist philosophy that defined early smart rings, prompting a reevaluation of user expectations and market direction.

One of the most ambitious challengers is Indian company Ultrahuman. Fresh off a substantial $70 million funding round with backing from Qualcomm’s venture arm, Ultrahuman is not just content with enhanced biometric tracking. Their long-term vision involves transforming the smart ring into a miniature, on-device computer capable of running software directly. This ambitious goal suggests a future where smart rings could facilitate everything from AI interactions to mobile gaming, blurring the lines between a health tracker and a full-fledged smart device. Earlier this year, Ultrahuman unveiled its third-generation smart ring, the $479 Ring Pro, slated for U.S. shipment in mid-September. The development of the Ring Pro was influenced by a significant patent dispute with Oura. In October 2025, the U.S. International Trade Commission ruled in Oura’s favor, imposing an import ban on Ultrahuman’s existing ring inventory into the U.S. market. To circumvent this legal hurdle, Ultrahuman engineered the Ring Pro with a completely redesigned form factor and an improved heart-rate sensing system for enhanced signal quality during sleep. It also incorporates a new dual-core processor, promising more accurate data collection and greater on-device processing capabilities, underpinning its future aspirations for advanced computing. Qualcomm’s investment is a powerful endorsement of Ultrahuman’s technological prowess and its vision to integrate more complex computational power into such a compact form factor.
Meanwhile, French company Circular is carving out its niche by focusing on convenience and advanced diagnostics. This week, Circular announced its upcoming Ring 3 series, which includes a Pro model and a Slim option, both expected to launch early next year. A standout feature of the Ring 3 series is an integrated NFC chip, enabling seamless contactless payments directly from the finger – a significant step towards greater practicality and integration into daily life. Beyond payments, the rings will incorporate on-finger vibrations for a range of alerts, including silent wake-up alarms, reminders, and crucial vital health notifications. The Ring 3 Pro, in particular, boasts a slimmer design than its predecessor and aims for medical-grade accuracy with FDA-cleared ECG for AFib detection. It also promises blood pressure trend tracking, glucose tracking capabilities, advanced sleep analysis, and comprehensive biometric monitoring, positioning it as a powerful diagnostic tool discreetly worn on the finger. The introduction of such features, particularly FDA clearance for specific medical conditions, highlights a trend towards integrating smart rings into broader healthcare monitoring.

Another significant player making waves is Chinese company RingConn, which debuted a ring this year with haptic vibrations and a strong emphasis on vascular health. Launched in May with a starting price of $349, the RingConn Gen 3 offers vascular health insights by utilizing sensor data from the ring to assess changes in vascular strain over time, requiring calibration with externally measured blood pressure values. It comprehensively tracks heart rate, blood oxygen saturation (SpO2), sleep patterns, activity levels, and stress, among other vital metrics. Distinct from Circular’s broader use of haptics for communication, RingConn primarily leverages vibration alerts for critical health changes, sedentary reminders, and low battery notifications, maintaining a focus on health-centric notifications rather than general interactivity. This approach suggests a deliberate choice to prioritize core health monitoring and alert functions, catering to users who value medical insights above all else.
The entry of tech behemoths into the smart ring market further underscores its growing mainstream appeal. Samsung, a global electronics giant, became the first major tech company to launch a smart ring in 2024. The Galaxy Ring, priced at $399, is positioned as a compelling option for consumers already entrenched in Samsung’s vast ecosystem of devices. While its current feature set for advanced health and sleep tracking is considered relatively basic compared to dedicated smart ring companies – lacking features like sleep apnea detection (offered by RingConn, Oura, and Ultrahuman) and AFib detection (available on Circular and RingConn smart rings) – its potential for seamless integration with other Samsung products like Galaxy smartphones, smartwatches, and smart home devices is a powerful differentiator. Samsung’s entry legitimizes the smart ring category for a wider audience and brings significant marketing muscle and manufacturing scale, which could accelerate market adoption and competition.

Other innovative entrants include Dreame, a relatively new player that unveiled a ring earlier this year featuring haptic alerts for alarms, calls, and messages. More uniquely, the Dreame Ring incorporates a small touchpad, allowing users to perform actions like skipping songs or snapping photos on their phone with a simple finger gesture. It also promises core health tracking capabilities such as heart rate, blood oxygen monitoring, heart rate variability insights, and sleep analysis. While pricing and availability are yet to be announced, Dreame’s focus on interactive controls through a touchpad hints at a future where smart rings offer more direct user input. Furthermore, the Pebble Halo, currently available only in India, pushes the envelope with a built-in screen, a stark contrast to the screen-less design favored by most smart rings, suggesting a potential future where visual feedback becomes a feature rather than an anomaly.
The rapid proliferation of these advanced features—contactless payments, haptic vibrations, on-device computing, and even miniature screens and touchpads—highlights a fundamental shift in the smart ring industry. What began as a quest for unobtrusive, screen-free health tracking is now evolving into a race to cram as many smartphone-like functionalities as possible into a two-gram titanium band. The irony is palpable: the initial allure of smart rings was their ability to provide health data without the constant digital bombardment of smartphones and smartwatches, allowing users to "step away from a screen" while still monitoring their well-being. However, with the current trajectory, the industry risks transforming these discreet health companions into mini-smartphones for the finger, potentially eroding the very appeal of simplicity and unobtrusiveness that drew early adopters.

This increasingly crowded and feature-rich market presents both opportunities and challenges. For consumers, it means a wider array of choices, with rings tailored to specific needs, from medical-grade diagnostics to seamless payment solutions or even rudimentary computing. For companies, it necessitates relentless innovation and differentiation. Oura’s IPO filing is a strategic move to secure the capital required to stay ahead in this escalating competition, investing in proprietary technology, expanding its ecosystem, and perhaps even acquiring smaller innovators. The market is poised for significant growth, with global wearable technology revenues projected to continue their upward trajectory, and smart rings are expected to capture an increasing share of this market. The coming years will likely see a consolidation of features, clearer market segmentation, and intense competition, ultimately shaping the future of wearable technology and how we interact with our digital health. The question remains whether the industry will find a balance between advanced functionality and the original promise of a truly unobtrusive, health-focused wearable.