The rapidly evolving landscape of autonomous and electric mobility witnessed a week of pivotal developments, marked by significant technological advancements from industry leader Waymo, escalating national security concerns over critical sensor technology, and a flurry of strategic investments shaping the future of transportation. From custom silicon chips to drone delivery ambitions and an investigation into the integrity of Chinese-made lidar, the sector continues its relentless march forward, albeit with increasing complexity and scrutiny.
Waymo’s Vertical Integration: A Custom Silicon Leap Towards Profitability
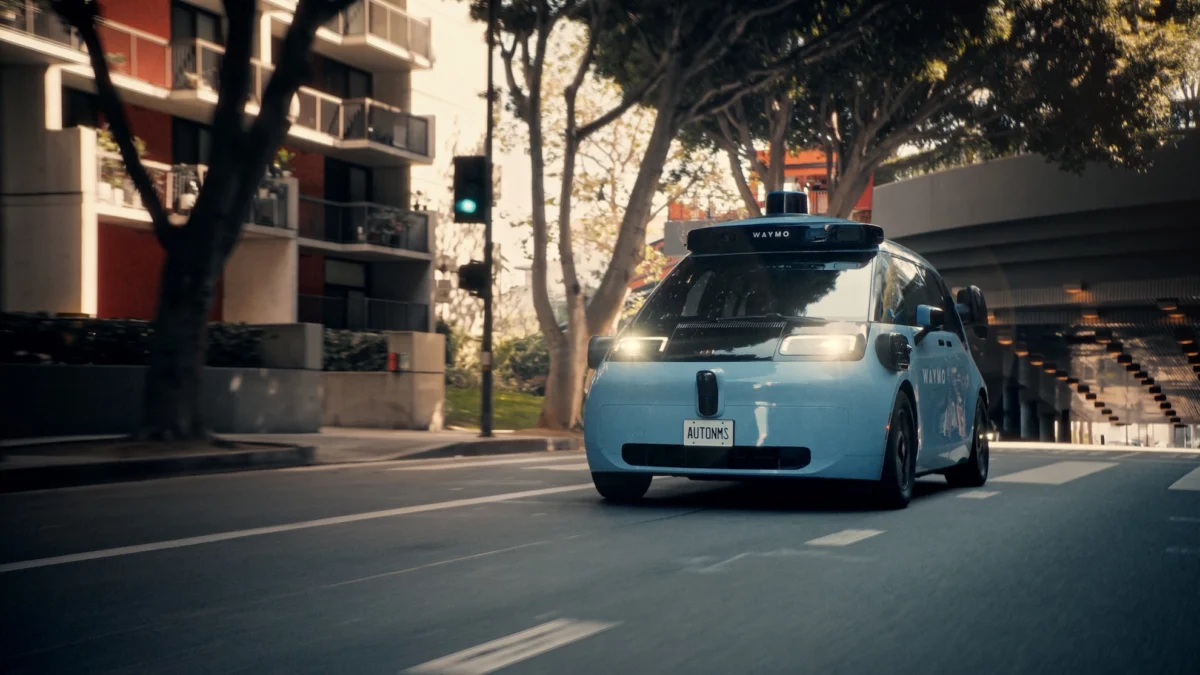
Waymo, a trailblazer in autonomous driving technology, continues its aggressive expansion across key U.S. cities, cementing its position at the forefront of the robotaxi race. The company’s growth trajectory, which sees its autonomous vehicles expanding service areas or entering new markets seemingly every week, is not merely a matter of operational scale but is deeply rooted in a sophisticated technological strategy. Central to these ambitions is Waymo’s sixth-generation self-driving system, which first debuted in its next-generation Ojai robotaxi. This week, the company shed further light on the critical underpinnings of this system, revealing a deeper level of vertical integration than previously understood.
The Ojai robotaxi, which recently became accessible to all riders in Los Angeles, Phoenix, and San Francisco, has been consistently touted by Waymo as a more cost-effective solution to build, operate, and maintain. This focus on economic efficiency is not merely an incremental improvement; it is a fundamental shift aimed at achieving the elusive goal of profitability in the capital-intensive autonomous vehicle industry. The journey to profitability necessitates not just technological prowess but also a meticulous control over the entire operational stack, from hardware to software.
The significant revelation this week was Waymo’s announcement that it has developed a custom silicon chip for its Ojai fleet. Specifically, the company has engineered a 5-nanometer (nm) Application-Specific Integrated Circuit (ASIC). This specialized chip is designed to manage the immense volume of raw data generated by the Ojai vehicle’s sophisticated sensor array before it reaches the core processing unit – effectively the "brain" of the self-driving system. To put the data volume into perspective, the Waymo Ojai is equipped with 13 high-fidelity cameras, alongside an array of lidar and radar sensors, each generating terabytes of data per hour of operation.
The custom ASIC boasts an impressive computing performance exceeding 1,000 TOPS (trillions of operations per second). This puts Waymo’s in-house silicon in a performance bracket comparable to, or even surpassing, some of the most advanced dedicated automotive processors on the market, such as Nvidia’s latest DRIVE AGX Thor. The strategic decision to design and build a custom chip underscores a growing trend in the tech and automotive industries: vertical integration. Companies like Tesla have famously pursued in-house chip design for their Full Self-Driving (FSD) capabilities, recognizing that tailored hardware can offer superior performance, power efficiency, and cost control compared to off-the-shelf solutions. A 5nm process node, at the cutting edge of semiconductor manufacturing, ensures not only high computational density but also remarkable power efficiency, critical for battery-powered electric vehicles where every watt counts.

Waymo asserts that this bespoke chip is a cornerstone of a system delivering "unmatched efficiency and performance." The upshot for urban mobility is profound: a more efficient and powerful processing architecture translates directly into a self-driving system that can react faster and more safely, especially in the highly complex, high-density environments characteristic of modern cities. This capability is paramount for navigating dynamic traffic, unpredictable pedestrians, and intricate road networks, which are the daily challenges faced by robotaxis.
While emphasizing its vertical integration, Waymo also highlighted its collaborative approach, listing a diverse set of partners involved in the compute stack. These include industry giants such as AMD, Micron, Nvidia, Samsung, Sandisk, Socionext, and TSMC. This robust network of partners suggests that while Waymo is taking greater control over critical components like its ASIC, it is simultaneously leveraging specialized expertise and manufacturing capabilities from across the semiconductor industry, demonstrating a pragmatic blend of in-house innovation and strategic outsourcing. The ability to control its core processing unit while integrating best-in-class components from partners provides Waymo with both a competitive edge and supply chain resilience.
National Security Concerns: The Chinese Lidar Probe
Beyond the technological advancements, the autonomous vehicle industry is increasingly navigating a complex geopolitical landscape, with national security concerns taking center stage. This week, revelations emerged regarding a discreet yet significant investigation being conducted by the Idaho National Laboratory (INL). The laboratory, a federally funded research and development center specializing in nuclear energy and national security, is reportedly evaluating whether Chinese-made lidar sensors could pose a security risk if widely adopted in vehicles within the United States.
This investigation is particularly notable not only for its subject matter but also for its funding source: a consortium of companies within the electric vehicle (EV) and autonomous vehicle (AV) industries. This suggests a proactive concern within the private sector, possibly driven by a desire to pre-empt potential future regulatory restrictions or supply chain vulnerabilities. The growing reliance on sophisticated sensors like lidar – which creates high-resolution 3D maps of the vehicle’s surroundings – raises legitimate questions about data integrity, potential for espionage, or remote manipulation if the underlying hardware or software components are compromised.
Lidar technology is foundational for Level 3, 4, and 5 autonomous driving systems, providing critical environmental perception data. If a foreign government were to gain control or access to such sensors, it could potentially gather sensitive infrastructure data, track vehicle movements, or even interfere with vehicle operation. These concerns echo broader geopolitical tensions surrounding Chinese technology companies and their role in global supply chains, particularly in critical infrastructure and emerging technologies. The U.S. government has previously taken steps to restrict the use of certain Chinese telecommunications equipment due to national security fears, and this investigation signals a potential expansion of that scrutiny into the automotive sector.
TechCrunch senior reporter Sean O’Kane, privy to this information from undisclosed sources, reached out to numerous prominent automotive and autonomous driving companies. The list included Rivian, General Motors, Ford, Kodiak, Lucid Motors, Nuro, and Uber, all of whom stated they were unaware of the INL’s review. Other key players, such as Aurora, Nvidia, and Zoox, did not respond to inquiries. The widespread lack of awareness among major industry players underscores the sensitive and discreet nature of the ongoing probe, but also highlights a potential disconnect between government-led security initiatives and industry understanding. The implications of this investigation could be far-reaching, potentially leading to new regulations on sensor procurement, influencing design choices for AV manufacturers, and further fragmenting the global automotive supply chain along geopolitical lines. Companies relying on cost-effective Chinese lidar solutions might be forced to seek alternative, potentially more expensive, suppliers, impacting vehicle development timelines and costs.

Dynamic Mobility Market: Key Investments and Strategic Shifts
The week also saw a vibrant array of funding rounds and strategic partnerships, illustrating the dynamic and capital-intensive nature of the mobility sector. These deals reflect shifting corporate strategies, emerging technological niches, and the relentless pursuit of scalable business models.
Also’s Evolving Vision and Capital Infusion:
Also, a startup incubated within Rivian, successfully raised an additional $150 million in a Series D funding round. Led by Prysm Capital, with continued participation from existing backers Eclipse, Greenoaks, and MVP Ventures, this latest raise brings Also’s total funding to an impressive $455 million since its spin-out from Rivian in March 2025. This rapid accumulation of capital—reaching a Series D within just over a year—is indicative of both investor confidence and the substantial financial requirements of its ambitious mission.
Also’s trajectory has undergone a significant evolution since its inception. Initially described as a micromobility company focused on pedal-assist electric bikes and commercial cargo quads, its mandate has expanded considerably. The company now defines itself as a "Palo Alto-based technology company building the world’s most capable driven and autonomous small electric vehicles." This pivot toward autonomy became evident earlier this year when Also secured a $200 million round and announced a multiyear commercial agreement with DoorDash to develop and deploy autonomous delivery vehicles. This strategic shift underscores the increasing convergence of micromobility with autonomous technology, aiming to address the burgeoning last-mile delivery market with scalable, self-driving solutions. The substantial capital raised will be crucial for accelerating R&D, scaling manufacturing, and deploying these sophisticated autonomous platforms.
Serve Robotics’ Strategic Diversification Post-Uber Exit:
Sidewalk delivery robot company Serve Robotics navigated a critical period by announcing new and expanded partnerships, demonstrating the importance of diversification in a volatile market. This comes on the heels of challenging news earlier in the month, where Serve reported during an earnings call that Uber had reduced its use of Serve’s robots on its app, with the partnership set to conclude next year. Compounding this, Uber also divested its entire stake in Serve Robotics.
Months before these changes, Serve was actively working on securing alternative agreements. This proactive strategy paid off this week with finalized deals that significantly bolster its market position. Serve has partnered with Grubhub to deploy its sidewalk robots, initially in key urban centers including Chicago, Los Angeles, and Alexandria, Virginia. Furthermore, its existing partnership with DoorDash has been expanded to encompass San Jose, California, and Washington, D.C. Uber’s retreat from Serve serves as a stark reminder and an important lesson for any company attempting to scale in the rapidly shifting mobility landscape: over-reliance on a single major partner can be precarious. Serve’s successful diversification into multiple platforms, securing agreements with two of the largest food delivery services, illustrates resilience and a robust strategy for sustainable growth.
Einride’s Electrification of Freight with Tesla Semis:
The Swedish electric and autonomous trucking company Einride struck a significant deal with Tesla, agreeing to purchase 500 of its electric Semis. These formidable electric big rigs will be integrated into Einride’s fleet and made available to its diverse customer base, which includes major logistics players like Amazon. The deployment of these Tesla Semis will occur in phases over the next 24 months, commencing in September. This agreement is particularly noteworthy given Tesla’s ongoing efforts to scale up production of the Semi, a process that has faced challenges and seen the company adjust its promises for "volume production" into 2026. For Einride, this deal reinforces its commitment to electrifying freight transport and expanding its autonomous capabilities, offering its clients a greener and potentially more efficient logistics solution. For Tesla, it provides a substantial commercial order, validating the Semi’s market appeal and helping to ramp up its limited production.

Grounded’s Niche in Custom Electric Vans:
Detroit-based startup Grounded, specializing in the customization of electric and gas-powered vans, successfully closed a $5 million seed round. The funding saw repeat investments from existing backers Also Capital (no relation to the Rivian spin-out ‘Also’) and Chicago-based early-stage firm The 81 Collection. New investors included Animal Capital, the Michigan Outdoor Innovation Fund, and a cohort of "various SpaceX alumni," according to founder and CEO Sam Shapiro. Grounded’s focus on bespoke solutions for commercial fleets taps into the growing demand for specialized vehicles tailored to specific business needs, particularly as companies transition to electric fleets and seek optimized operational efficiencies. The involvement of repeat investors and individuals with experience from high-growth tech companies like SpaceX signals confidence in Grounded’s market strategy and execution.
Uber’s Multi-Modal Delivery Expansion:
Uber continued its aggressive expansion into new delivery modalities and autonomous services, highlighting its strategy to diversify beyond traditional ride-hailing. The company announced an investment in and partnership with drone delivery company Zipline, though the exact investment amount was not disclosed. The ambition, however, is grand: to achieve 1 million deliveries per day using Zipline’s drones by the end of 2029. This aggressive target underscores Uber’s commitment to leveraging advanced technologies for last-mile logistics, potentially transforming the speed and cost-efficiency of deliveries.
In the robotaxi sector, Uber, alongside Tesla and Waymo, received permits from Nevada regulators to operate commercial robotaxi services in Clark County, home to Las Vegas. Collectively, these permits allow for the deployment of up to 8,000 robotaxis across the county over the next 12 months. While it’s improbable that all 8,000 vehicles will materialize in Vegas within a year, even a fraction of this number would significantly impact the city’s transportation landscape, signaling a major push for autonomous mobility in a high-traffic urban environment.
Further expanding its global autonomous footprint, Uber announced early rider testing in London with its partner Wayve, a launch of a robotaxi service in Zagreb, Croatia, with Pony.ai and Verne, and the initiation of driverless rides in Dubai with Baidu’s Apollo Go platform. These moves demonstrate Uber’s strategic intent to build a multi-partner autonomous network globally, adapting its approach to local regulations and technological partnerships to accelerate deployment.
Industry Tidbits and Regulatory Developments
The broader mobility ecosystem was abuzz with other notable developments:
- Amazon’s Drone Delivery Ambitions: Amazon declared its intent to expand its Prime Air drone delivery service to nearly 500 U.S. cities by the end of 2026, a sixfold increase from its current footprint. This ambitious expansion underscores the growing confidence in drone technology for logistics and the drive to redefine rapid delivery.
- Bedrock Robotics’ Autonomous Excavators: Bedrock Robotics, a startup founded by veterans from Waymo and Segment, announced that excavators equipped with its self-driving system are now operating fully autonomously at three large customer sites in Nevada and Texas. This demonstrates the expanding application of autonomous technology beyond passenger vehicles into industrial and construction sectors, promising enhanced efficiency and safety.
- Hyundai Genesis GV90: Hyundai’s luxury brand Genesis unveiled a seven-seater electric SUV, the GV90. This vehicle is poised to compete directly with other large luxury EVs such as the Cadillac Escalade IQ and Rivian R1S, signaling the continued electrification and diversification of the high-end SUV market.
- Tesla’s China Recall: Tesla, along with 10 other carmakers in China, initiated a recall of millions of vehicles over concerns regarding hidden emergency door releases. This industry-wide action, also affecting brands like Xiaomi, Xpeng, and Geely’s Zeekr and Lynk & Co., highlights regulatory scrutiny over vehicle safety features, particularly in the event of a crash or fire where occupants might be trapped.
- Uber’s Dutch Fine: Uber faced a substantial fine of €825 million ($966 million) from the Dutch Data Protection Authority. The fine was imposed for Uber’s use of automated systems to deactivate or suspend driver accounts without providing adequate information, a clear violation of European data protection law. This incident underscores the increasing importance of data privacy and algorithmic transparency in the gig economy and the strict regulatory environment in Europe.
- Waymo’s NHTSA Inquiry: Waymo submitted responses to the National Highway Traffic Safety Administration (NHTSA) as part of the regulator’s investigation into a low-speed collision involving a robotaxi and a child. However, the initial release of these documents was heavily redacted, indicating the sensitive nature of the information and the ongoing regulatory scrutiny into AV safety protocols and incident reporting.
The confluence of these events paints a vivid picture of a mobility sector in constant flux. Technological innovation, particularly in custom silicon, is driving performance and efficiency, while geopolitical considerations are reshaping supply chains and regulatory frameworks. Simultaneously, a dynamic investment landscape is fueling ambitious expansions into autonomous delivery and novel transportation solutions. As these forces continue to interact, the future of how we move people and goods promises to be both transformative and complex.