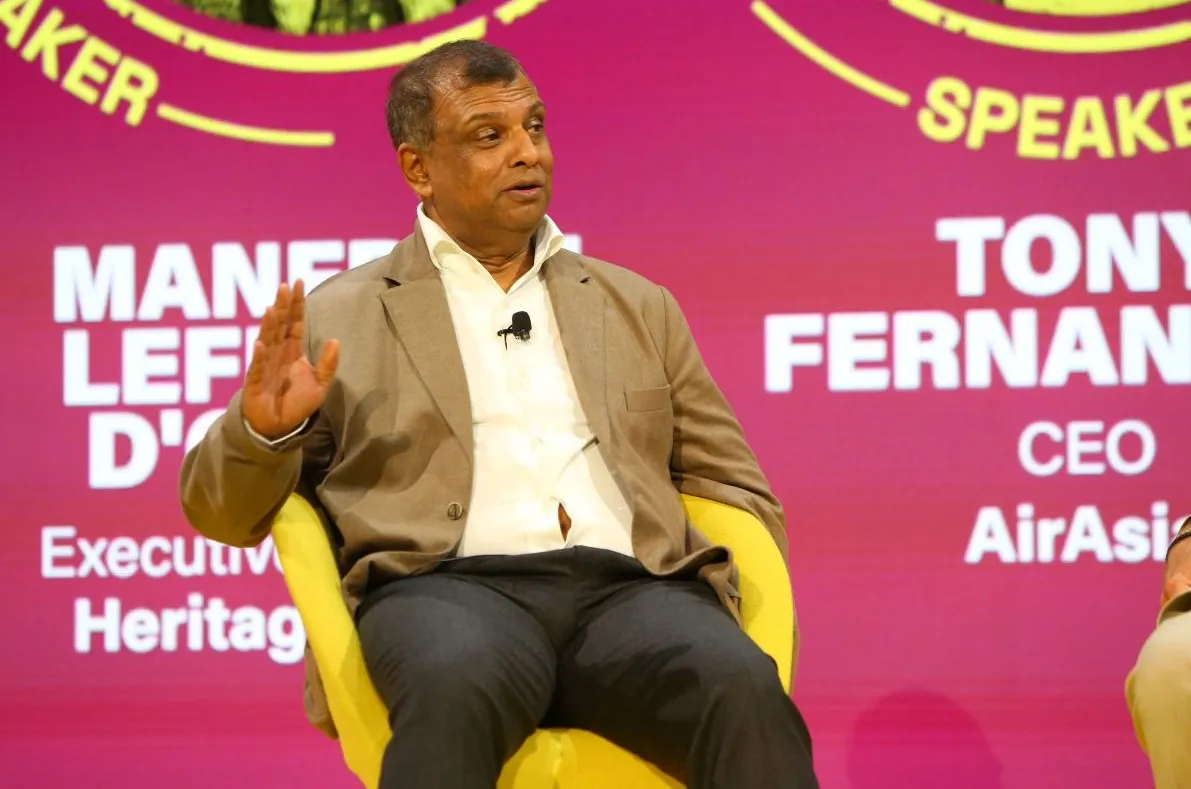
The aviation sector in Southeast Asia has been characterized by intense competition and rapid fluctuations in market dynamics, a reality underscored by recent statements from AirAsia Co-Founder Tony Fernandes. Speaking at a high-profile press conference in Bangkok during a comprehensive tour of AirAsia’s regional offices, Fernandes addressed growing speculation regarding the carrier’s domestic standing in Malaysia. He categorically dismissed reports suggesting that the Malaysian government was in discussions to allow rival airlines to absorb portions of AirAsia’s domestic capacity, labeling such claims as "misinformation" that fails to account for the complexities of the low-cost carrier (LCC) business model.
Fernandes’ remarks come at a time when the aviation industry is grappling with a convergence of macroeconomic pressures, including volatile energy markets and shifting regulatory oversight. The co-founder’s defense of the airline’s market position was rooted in the assertion that AirAsia possesses a "unique brand" and a highly specialized cost structure that cannot be easily replicated or assumed by traditional full-service carriers or even other regional LCCs. According to Fernandes, the suggestion that rivals could simply "step in" to fill the void left by AirAsia’s strategic route adjustments ignores the operational efficiencies and branding power that the carrier has spent over two decades refining.
The Context of the Rebuttal: Strategic Consolidation vs. Market Exit
The rumors addressed by Fernandes emerged against a backdrop of visible operational changes within AirAsia. In recent months, the airline has engaged in a process of route rationalization and fleet management aimed at preserving cash reserves. This strategy has involved the suspension of certain underperforming routes and the return of several aircraft to lessors. To external observers and some industry analysts, these moves were interpreted as a sign of weakening market share or financial instability, prompting speculation that the Malaysian government might intervene to ensure domestic connectivity by redistributing traffic rights to competitors such as Malaysia Airlines or Batik Air.
However, Fernandes clarified that these adjustments are part of a broader, proactive effort to navigate a "perfect storm" of external economic factors. The primary driver of these changes, he noted, is the soaring cost of jet fuel, which has been exacerbated by heightened geopolitical tensions in the Middle East, specifically involving Iran. As fuel typically accounts for 30% to 50% of an airline’s operating expenses, the spike in Brent crude prices has forced AirAsia to prioritize high-yield, high-demand routes while scaling back on secondary sectors that do not meet stringent profitability thresholds in the current high-cost environment.
The Competitive Landscape and the LCC Advantage
A central component of Fernandes’ argument is the "irreplicable" nature of AirAsia’s cost structure. Since its inception, AirAsia has operated on a high-utilization, point-to-point model that maximizes aircraft time in the air and minimizes ground turnaround times. This model is supported by a lean workforce and a focus on ancillary revenue streams—ranging from baggage fees to in-flight meals and digital services.
In Malaysia, the competitive landscape is divided between the national carrier, Malaysia Airlines Berhad (MAB), which focuses on a premium, full-service experience, and Batik Air Malaysia (formerly Malindo Air), which occupies a middle ground. Fernandes argued that these rivals operate on fundamentally different financial frameworks. A full-service carrier attempting to absorb AirAsia’s low-fare capacity would likely face significant margin compression, as their higher overhead costs would make it difficult to sustain the price points that AirAsia customers have come to expect.
Furthermore, the "brand equity" Fernandes mentioned refers to the carrier’s deep penetration into the ASEAN market. AirAsia has long positioned itself as a democratizing force in regional travel, under the slogan "Now Everyone Can Fly." This brand loyalty, coupled with an integrated digital ecosystem through the AirAsia MOVE app (formerly the AirAsia Superapp), provides a level of customer data and engagement that Fernandes believes creates a formidable barrier to entry for any competitor looking to seize its domestic market share.
Impact of Global Geopolitics on Aviation Operating Costs
The mention of the "Iran war"—referring to the broader regional instability and its impact on global energy supplies—highlights the vulnerability of the aviation sector to external shocks. The price of jet fuel is inextricably linked to global crude oil benchmarks. In 2024, the threat of supply disruptions in the Strait of Hormuz and the broader Middle East has led to significant volatility in the Singapore Jet Kerosene benchmark, which is the primary pricing index for Asian airlines.
For a carrier like AirAsia, which operates on razor-thin margins to maintain low fares, a sustained increase in fuel prices necessitates immediate fiscal prudence. Fernandes noted that returning aircraft and cutting routes are not signs of a permanent retreat but are instead tactical maneuvers to protect the airline’s balance sheet. By focusing on core domestic hubs and regional "cash cow" routes, the airline aims to maintain a healthy cash flow while waiting for fuel prices to stabilize or for more fuel-efficient aircraft, such as the Airbus A321neo, to join the fleet.
Financial Health and the PN17 Status Context
To understand the sensitivity of the reports Fernandes dismissed, one must look at the financial trajectory of AirAsia’s parent company, Capital A Berhad. The company has been working to emerge from its Practice Note 17 (PN17) status—a designation by Bursa Malaysia for companies in financial distress. This status was triggered largely by the devastating impact of the COVID-19 pandemic, which grounded the airline’s fleet for the better part of two years.
While AirAsia has shown a robust recovery in passenger numbers and load factors post-pandemic, the PN17 status has made the company a subject of frequent speculation regarding potential mergers, acquisitions, or government-led restructuring. Fernandes’ public dismissal of the reports in Bangkok was likely a strategic move to reassure investors and stakeholders that Capital A remains in control of its destiny and that its domestic dominance in Malaysia is not under threat by government-mandated redistribution.
Timeline of Recent Developments for AirAsia (2023–2024)
- Mid-2023: AirAsia begins a concerted effort to reactivate its entire fleet, bringing aircraft out of long-term storage following the pandemic.
- Late 2023: Rising geopolitical tensions in the Middle East cause a surge in jet fuel prices, prompting a review of the airline’s network expansion plans.
- Early 2024: Capital A announces plans to merge its airline businesses (AirAsia Malaysia, Thailand, Indonesia, and Philippines) under a single entity, AirAsia Aviation Group, to streamline operations and improve capital access.
- Q1 2024: Reports emerge in Malaysian media suggesting that the Ministry of Transport and MAVCOM (Malaysian Aviation Commission) are evaluating the capacity of other airlines to handle domestic traffic in the event of further fleet reductions by AirAsia.
- Friday, Current Month: Tony Fernandes holds a press conference in Bangkok, explicitly denying these reports and reaffirming the airline’s commitment to its core markets.
Regulatory Environment and Traffic Rights
The redistribution of airline capacity is not a simple administrative task; it is governed by a complex set of regulations overseen by the Malaysian Aviation Commission (MAVCOM). Traffic rights are granted based on an airline’s ability to prove operational capability, safety standards, and financial viability.
If the government were to consider shifting capacity, it would involve a lengthy process of revoking AirAsia’s existing Air Service Licenses (ASL) for specific routes and inviting tenders from other carriers. Fernandes’ confidence suggests that AirAsia remains in full compliance with its regulatory obligations, and that the airline continues to meet the "public service" requirements of domestic connectivity, even with a slightly reduced fleet.
Analysis of Implications for the Malaysian Travel Market
The potential implications of this situation are twofold. For the consumer, the stability of AirAsia is critical to maintaining affordable air travel. In the Malaysian domestic market, AirAsia often serves as the primary price setter. If its capacity were significantly reduced or handed over to competitors with higher cost bases, the inevitable result would be an increase in average airfares, potentially limiting travel options for lower-income segments of the population.
For the broader industry, Fernandes’ statements signal a period of "disciplined growth." Rather than chasing market share at any cost, AirAsia is signaling to the market that it will prioritize profitability and liquidity. This shift reflects a broader trend in the global aviation industry where "capacity discipline" has become the new mantra for CEOs navigating a post-pandemic world defined by high interest rates and expensive energy.
Official Responses and Industry Outlook
While the Malaysian government has not issued a formal statement corroborating the rumors of capacity redistribution, the Ministry of Transport has historically emphasized the need for a "level playing field" in the aviation sector. Analysts suggest that the government’s priority remains the recovery of the tourism sector, which is a vital pillar of the Malaysian economy. Ensuring that the nation’s largest LCC remains viable is central to that goal.
In his closing remarks in Bangkok, Fernandes emphasized that AirAsia is not merely an airline but a vital component of the ASEAN infrastructure. He stated that the airline is currently strengthening its major domestic and regional routes where demand remains "extraordinarily strong," particularly in the tourism-heavy corridors between Malaysia, Thailand, and Indonesia.
The consensus among aviation experts is that while AirAsia faces significant short-term headwinds, its entrenched position in the regional market makes it an unlikely candidate for the kind of government-led dissolution suggested by the rumors. The airline’s ability to pivot its strategy in response to fuel prices and geopolitical events will be the true test of its resilience in the coming fiscal year. For now, Fernandes has sent a clear message to rivals and regulators alike: AirAsia remains a "unique brand" that is not easily replaced.