The global tourism industry is currently navigating a complex landscape defined by geopolitical volatility, fluctuating operational costs, and a fundamental shift in consumer behavior. While international travel demand remains resilient, a growing segment of the market is prioritizing "value-driven quality"—a trend that seeks high-level experiences without the prohibitive price tags of traditional luxury. According to recent data from Skift Research, 63% of global travelers intend to increase their travel expenditure over the next twelve months. However, 39% of these same travelers are actively employing cost-saving strategies, signaling a market that is increasingly price-sensitive yet experience-hungry. This shift has exposed a significant structural deficit in emerging markets, most notably across the African continent: the "missing middle."
For decades, the African tourism narrative has been dominated by two extremes: high-end, exclusive luxury safaris aimed at the global elite, or budget-tier, unbranded accommodations that often lack consistent professional management. As the continent prepares for a projected surge in international and intra-African travel, the lack of a reliable, professionally managed mid-market tier has become a primary constraint on scalability. Industry experts and investors now argue that the continent’s greatest economic opportunity lies in repairing this "broken architecture" to create a seamless, connected tourism ecosystem.
The State of African Hotel Development in 2026
The scale of the opportunity is reflected in the current development pipeline. Data from the Lagos-based W Hospitality Group indicates that Africa’s hotel development pipeline reached 123,846 rooms as of early 2026. While this represents a significant increase in capacity, a granular analysis reveals a persistent imbalance. A vast majority of these new developments remain concentrated in the upscale and luxury segments, leaving the mid-market—defined by standardized quality, modern amenities, and accessible pricing—vastly underrepresented.
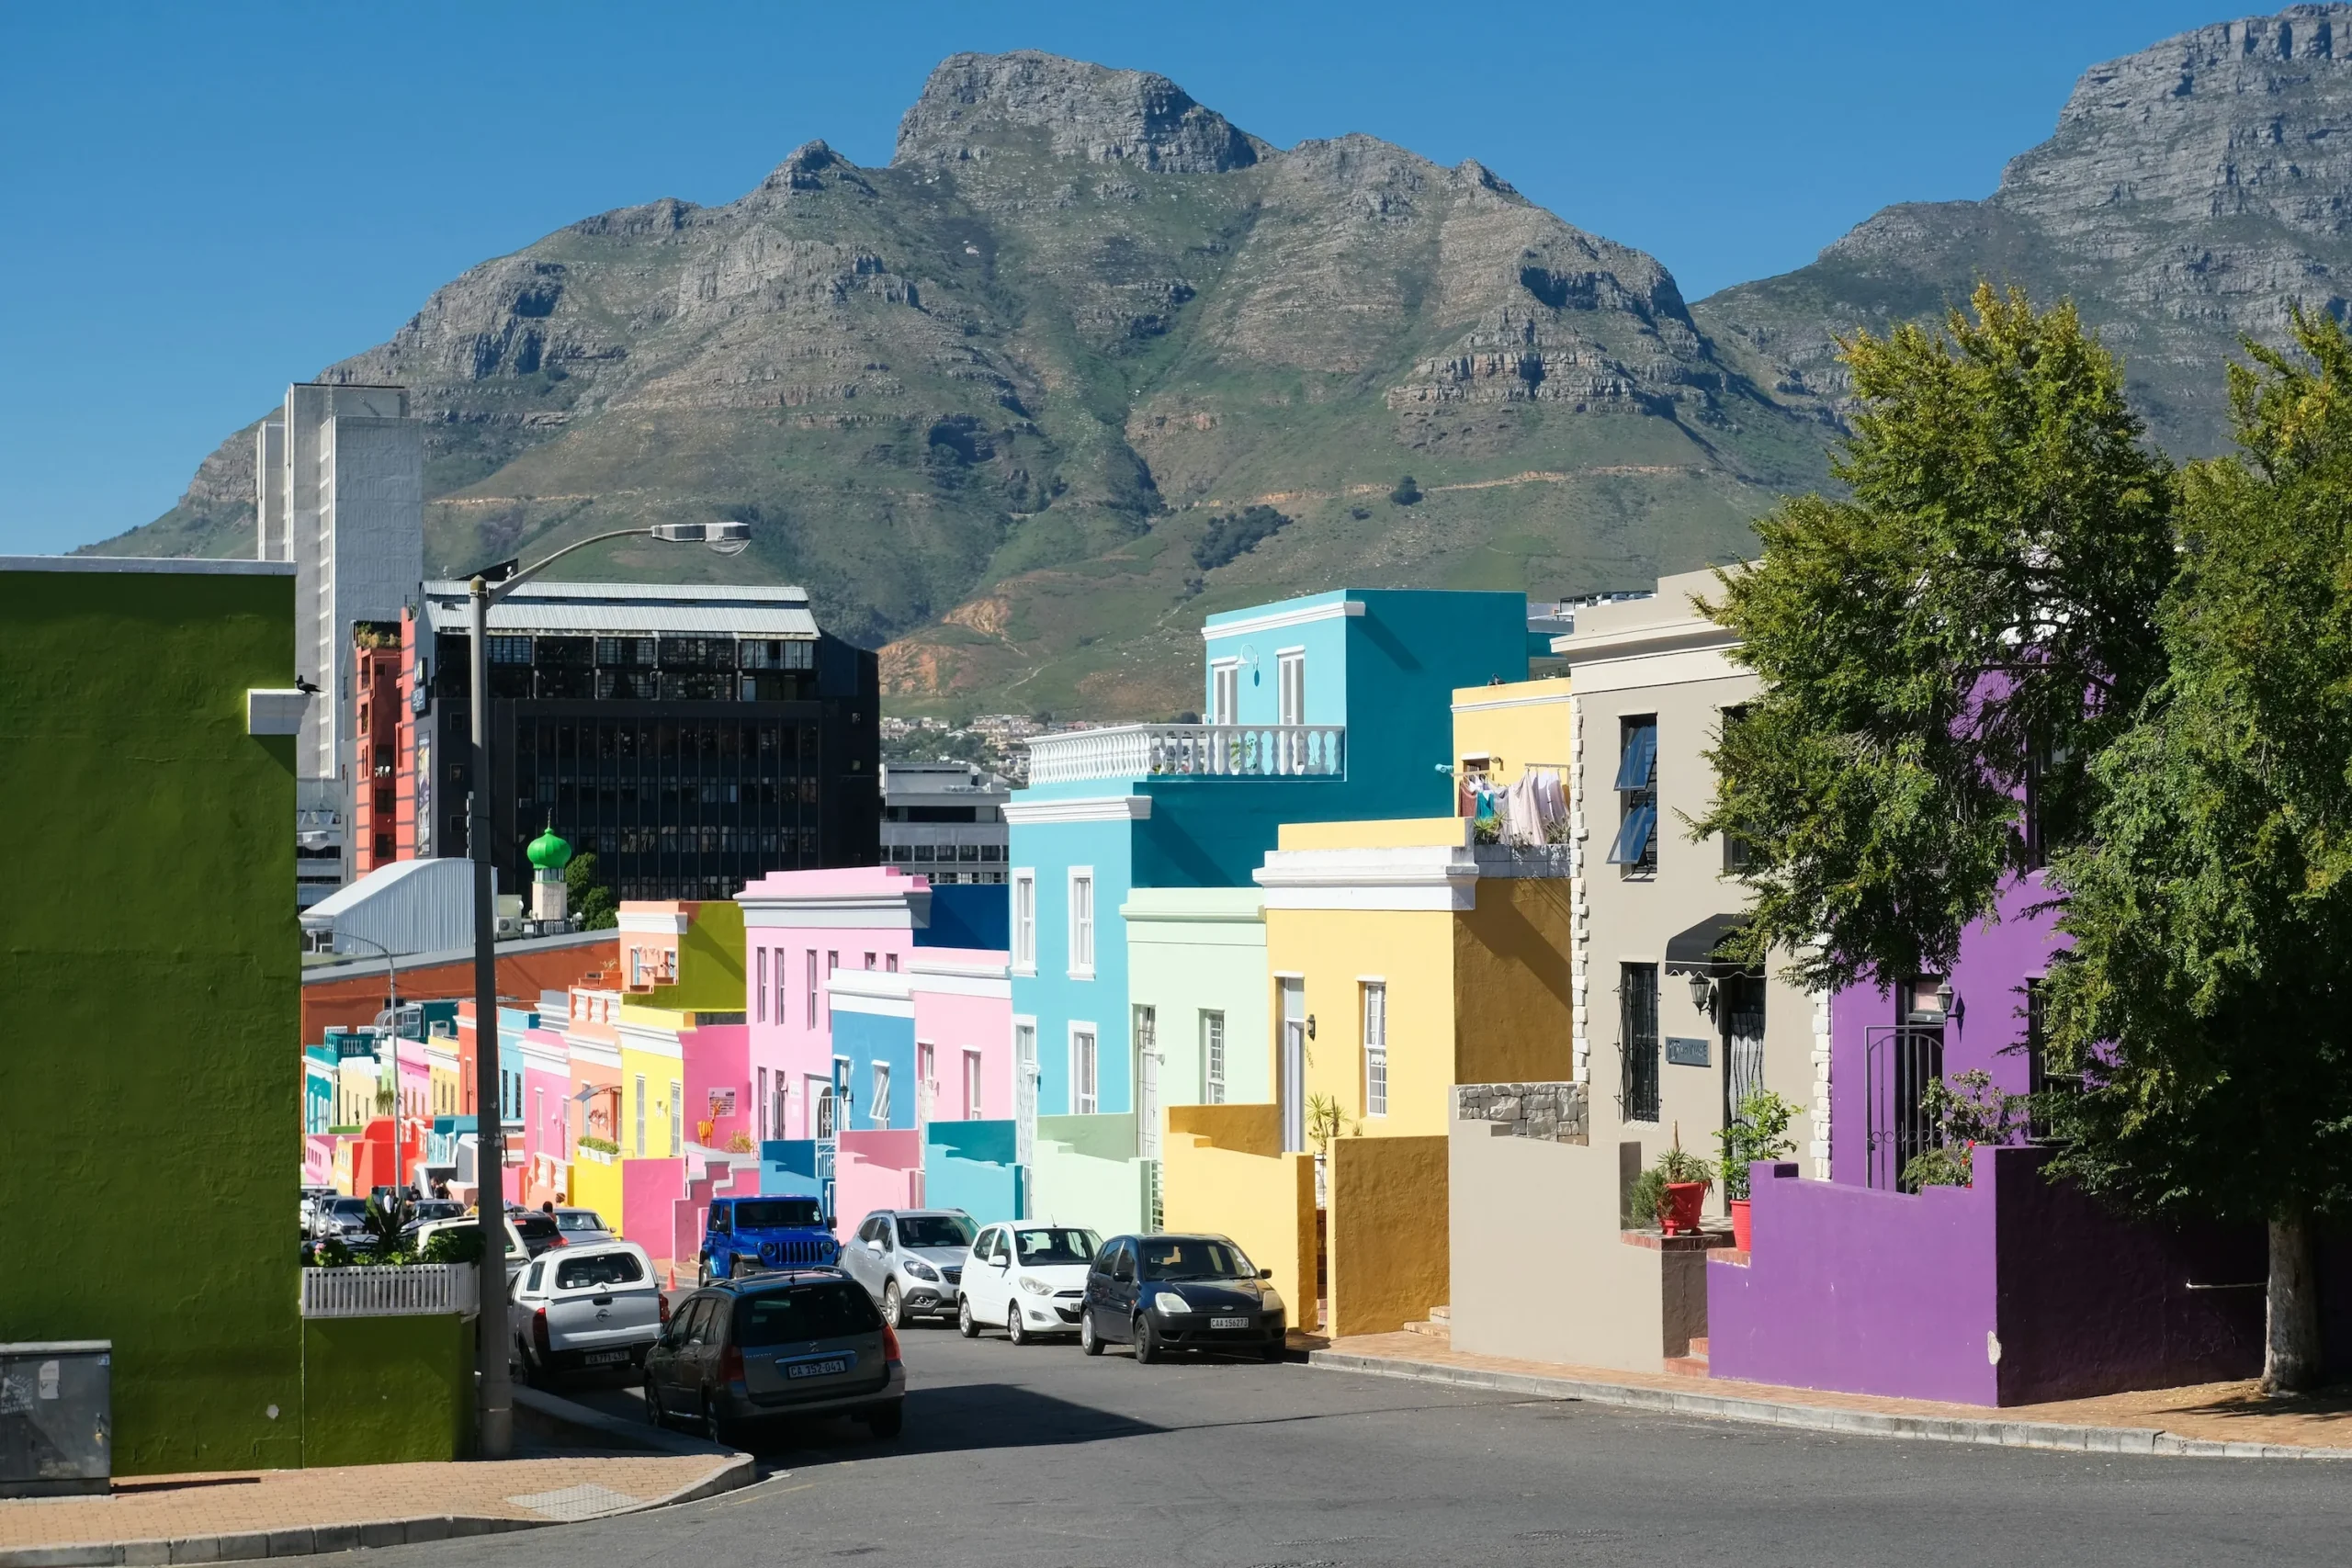
At a recent industry summit in Cape Town, Wafeeq Pandey, Managing Director at Goldman Sachs South Africa, characterized the mid-market as "absolutely underpenetrated." This sentiment was echoed by Hamza Farooqui, founder and CEO of Millat Group, a Johannesburg-based private equity firm. Farooqui notes that while capital has historically flowed toward "trophy assets" and proven luxury lodges, the fragmented nature of independent hotel ownership across Africa has made it difficult for mid-market brands to achieve the scale and standardization required to win the trust of institutional travel partners.
The current pipeline suggests that while the "hardware" of tourism is being built, the "software"—the management systems, distribution networks, and service standards—is lagging behind in the middle tier. This gap prevents the continent from fully capturing the "value-seeking" demographic that currently drives much of the growth in European and Asian markets.
Demographic Shifts and the Rise of the African Middle Class
The urgency to develop the mid-market is driven not only by international arrivals but also by a massive demographic shift within the continent. Africa’s population has surpassed 1.5 billion, with a median age under 20. This young, digitally native population is entering the workforce and forming a new generation of travelers who prioritize mobility and localized experiences over traditional luxury.
Estimates regarding the size of the African middle class vary, but the African Development Bank places the figure at approximately 350 million people. This cohort represents a robust internal market that is increasingly looking to travel across borders for both business and leisure. "You’ve always had a very robust middle class in Africa," Farooqui observed, "and the younger middle-income traveler in particular is becoming a growing market."
In 2025, Africa was the world’s fastest-growing tourism region, with international arrivals rising by 8% to reach 81 million. However, for this growth to be sustainable, the infrastructure must accommodate a broader range of income levels. The current reliance on luxury inventory limits the volume of travelers the continent can support, effectively capping the economic impact of the tourism sector.
Overcoming the "Broken Architecture" of African Travel
A central challenge to scaling African tourism is what Farooqui describes as a "broken architecture"—a disconnect between the various components of the traveler’s journey. In many African destinations, the transition from flight to hotel to local excursion is fraught with friction.
Regulatory and Logistical Barriers
The African Visa Openness Index highlights a significant hurdle: African travelers still require visas before departure for 47% of intra-African journeys. While some regions are moving toward visa-free regimes, the lack of regulatory harmony continues to stifle regional mobility. Furthermore, while air connectivity is improving through corridors opened by carriers like Ethiopian Airlines and Emirates, the "last mile" of travel—ground transportation and inter-regional transfers—remains fragmented and often unreliable for those not booking an all-inclusive luxury package.
Distribution and Discovery
The way travelers discover African destinations is also undergoing a transformation. Skift Research found that 63% of AI-aware travelers globally have used generative AI tools to plan their trips. These tools are shifting the power dynamic away from traditional Online Travel Agencies (OTAs) and large hotel chains, allowing independent and localized brands to gain visibility if they have the right digital infrastructure.
Farooqui argues that the "next-gen" traveler does not want a sanitized, Westernized experience. "They don’t want to walk into a lobby and feel like they’re back in New York City," he said. The opportunity for mid-market operators lies in combining the "scale and sophistication of a global hotel brand with the authenticity of an independent African brand."
The Ecosystem Approach: Beyond Room Nights
To address these systemic issues, firms like Millat Group are advocating for an "ecosystem" approach to hospitality. This model moves away from the traditional focus on filling hotel rooms and toward managing the entire guest journey. Using the Hyatt Regency Cape Town as a proof-of-concept, Millat has integrated in-house logistics, vetted tour operators, and curated local experiences to provide a seamless transition for travelers.
This strategy is aimed at building "institutional trust." For global travel program directors and institutional investors, the primary risk in Africa is often the lack of predictability. By professionalizing the middle tier and creating "connected journeys"—such as seamless transitions between Cape Town, Victoria Falls, and regional business hubs—operators can provide the reliability that international markets demand.
David Frost, CEO of the Southern Africa Tourism Services Association (SATSA), emphasizes that the mid-market is the key to "geographic spread." While luxury travelers often stick to isolated lodges or "trophy" cities, mid-market travelers are more likely to self-drive, explore secondary cities, and stay longer, ensuring that tourism spending reaches a wider range of local communities.
Economic Implications and Strategic Outlook
The development of a professional mid-market tier has profound implications for Africa’s economic resilience. Tourism is a labor-intensive industry; a thriving mid-market sector creates a more diverse range of jobs than the niche luxury sector. Moreover, a robust mid-market provides a buffer against global economic downturns, as it appeals to a broader base of domestic and regional travelers who may continue to travel even when long-haul international arrivals dip.
The current economic climate, characterized by favorable exchange rates for international visitors, provides a temporary window of opportunity. High-quality experiences are currently accessible at mid-market prices for those holding US Dollars or Euros. However, industry leaders warn that this advantage will not last indefinitely. The winners in the next decade will be those who use this period to build the "connective tissue" of African tourism.
Chronology of Recent Developments:
- 2024-2025: Rapid expansion of air corridors between the Middle East and African capitals.
- Early 2025: Africa records 81 million international arrivals, an 8% year-on-year increase.
- Late 2025: W Hospitality Group reports a record 123,000+ rooms in the development pipeline.
- 2026 Forecast: Shift toward AI-driven trip planning begins to impact OTA dominance in African markets.
Conclusion
The future of African tourism is no longer solely about the "frontier" or the "trophy asset." It is about the professionalization of the middle. The "missing middle" represents the bridge between the continent’s vast potential and its realization as a global tourism powerhouse. For operators, the challenge is to deliver technology-driven, localized, and frictionless experiences at scale. For investors, the opportunity lies in the underbuilt and underpenetrated mid-market segments that promise long-term, sustainable volume.
As the continent’s population grows and its middle class expands, the demand for reliable, high-quality, and fairly priced travel infrastructure will only intensify. The operators who can reduce friction, build trust, and curate the entire journey will be the ones to define the next era of African hospitality. The infrastructure being built today will determine whether Africa can successfully transition from a niche luxury destination to a globally competitive, multi-tiered tourism ecosystem.