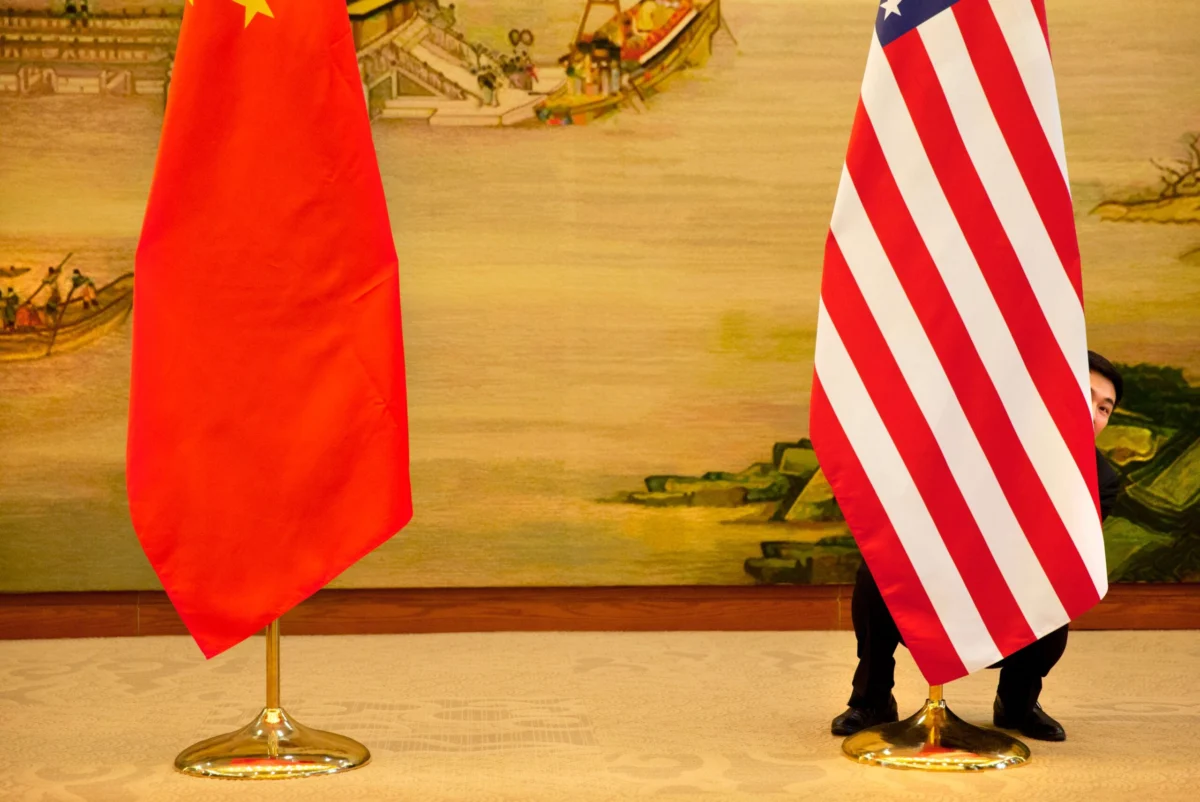
In a significant escalation of its efforts to safeguard critical technology sectors, Washington moved in July and August to tighten restrictions on foreign-made advanced robotic systems and imposed substantial tariffs on imported drones and their components. These measures, citing paramount national-security concerns, are set to profoundly reshape the global robotics and drone industries. The drone tariffs are slated to take effect in September 2026, with further component tariffs following in 2027, signaling a clear intent to reduce reliance on foreign, particularly Chinese, technology in strategically vital areas.
This series of regulatory actions is not an isolated incident but rather an integral part of a broader U.S. strategy to restrict foreign technology, particularly from China, within industries deemed essential for national security and economic competitiveness. The foundation of this policy push can be traced back to the Federal Communications Commission’s (FCC) "Covered List," established in 2021. Initially targeting telecommunications and surveillance equipment from specific companies, notably Huawei, ZTE, and Hikvision, the list has systematically expanded its scope. Its evolution first encompassed foreign-made drones and, most recently, was extended to include advanced robotic devices, reflecting a growing concern across a wider spectrum of emerging technologies.
A Chronology of Escalating Restrictions
The U.S. government’s concerns about the security implications of foreign technology, especially from geopolitical rivals, have been intensifying for several years.
- 2021: The Genesis of the Covered List: The FCC formally established its "Covered List," identifying communications equipment and services produced or provided by companies deemed to pose an unacceptable risk to U.S. national security. This initial iteration primarily focused on prominent Chinese telecommunications giants like Huawei and ZTE, along with surveillance equipment manufacturers such as Hikvision and Dahua, citing their potential links to state-sponsored espionage and vulnerabilities in critical infrastructure.
- 2023: Expanding to Drones: Building on the existing framework, the FCC expanded the Covered List to include certain foreign-made drones. This move came amidst growing apprehension regarding the widespread adoption of Chinese-manufactured drones by various U.S. entities, from local law enforcement to critical infrastructure operators. Concerns revolved around data security, potential surveillance capabilities, and the integrity of supply chains for devices that could have both commercial and military applications.
- July 2026: Advanced Robotic Systems Included: The latest significant expansion occurred in July 2026, when the FCC added "advanced robotic systems" to the Covered List. This broad category encompasses sophisticated autonomous machines capable of complex tasks, often featuring advanced AI and sensor arrays. This action directly targets a burgeoning sector where Chinese manufacturers have rapidly gained a dominant global foothold.
- August 2026: Steep Tariffs on Drones: Following the regulatory restrictions, the U.S. administration imposed steep tariffs on imported drones and their components in August 2026. These economic measures are designed to increase the cost of foreign-made drones, thereby incentivizing domestic production and promoting the use of U.S.-allied alternatives. The tariffs are scheduled to become effective in September 2026, with additional tariffs on components phased in through 2027, indicating a phased but firm commitment to the policy.
These sequential actions illustrate a clear governmental trajectory: moving from restricting specific telecommunications hardware to encompassing a broader array of high-tech devices, including drones and now advanced robotics, reflecting a comprehensive strategy to secure critical supply chains and mitigate perceived national security risks across multiple technological fronts.
The Chinese Dominance and the "Scale Gap"
The latest U.S. policy shifts arrive at a time when Chinese manufacturers have established formidable market positions in both the drone and, increasingly, the humanoid robot sectors. These companies often compete with pricing strategies that U.S. and European rivals struggle to match, a competitive edge rooted in vast manufacturing scale and integrated supply chains.
The global robotics industry currently presents a stark contrast in competitive advantages between the U.S. and China. Unlike the semiconductor industry, which often hinges on a few highly specialized and geographically concentrated manufacturing processes, robotics is a more diffused field, not easily controlled by a single technological choke point, as noted by Ankur Saxena, an investment director at TDK Ventures. However, China’s manufacturing prowess provides a different, yet equally potent, form of leverage.
According to a recent report by Counterpoint Research, global humanoid robot shipments reached an impressive 22,000 units in the first half of 2026. The overwhelming majority of these units – an estimated 86% – originated from Chinese manufacturers. The report identifies the world’s five largest humanoid robot makers by shipments – AgiBot, Unitree, Galbot, UBTECH, and Leju Robotics – as all Chinese entities. This indicates a significant "scale gap," with U.S. companies operating at a considerably smaller scale, as highlighted by Soumen Mandal, a principal analyst at Counterpoint Research.
This manufacturing advantage for Chinese firms is self-reinforcing. Lower unit prices enable the deployment of a greater number of robots into real-world applications, generating invaluable operational data that can be used to refine and improve their technology. This iterative process of deployment and data collection, coupled with higher production volumes, creates a virtuous cycle that further drives down manufacturing costs, as explained by Saxena.
Furthermore, Chinese humanoid robot manufacturers are aggressively pushing down costs by internalizing more of their technology stack and leveraging China’s extensive existing manufacturing ecosystem. For instance, companies like Unitree are developing more components in-house, reducing reliance on external suppliers. Simultaneously, established automakers such as XPeng are entering the robotics space, drawing upon their deep expertise in chip design and large-scale vehicle manufacturing to accelerate their robotics initiatives.
Saxena succinctly encapsulates the dichotomy: "The United States leads in frontier AI, software and semiconductor innovation. China leads in manufacturing scale, supply-chain depth and cost." This manufacturing edge has allowed Chinese companies to reduce humanoid robot prices at a pace that most U.S. competitors find difficult to emulate. Saxena warns that punitive measures alone cannot overcome this fundamental economic reality: "You cannot sanction your way around a cost curve. You can only out-build it, and America has yet to begin making the decade-long investment that will require." This sentiment underscores the long-term challenge facing the U.S. industry.
Industry Reactions and Broader Implications
The U.S. restrictions have elicited varied reactions from the industry, highlighting both support for national security measures and concerns about the potential for market fragmentation. Agility Robotics, a U.S.-based company known for its Digit humanoid robot, welcomed the FCC’s decision in July. The company stated that such proactive measures could address security concerns surrounding foreign-made advanced robots before they become deeply integrated into the U.S. market, a situation that has already occurred in the drone industry. Agility Robotics emphasized that its Digit humanoid is designed and assembled in the U.S., aligning with the stated goals of the new regulations. However, the company also underscored the importance of continued access to essential tools and technologies to foster ongoing robotics research and innovation.
Industry analysts and executives who spoke with TechCrunch largely anticipate that the cumulative effect of these restrictions will not be a clean, binary U.S.-China split in the global market. Instead, they foresee a more fragmented global landscape. This fragmentation implies that while Chinese companies may face barriers in the U.S., they will likely expand their operations and market share elsewhere. Concurrently, U.S. and allied manufacturers will likely find stronger competitive ground in markets where national security requirements and data integrity are paramount considerations.
Where Does China Go Next? The Global South and Beyond
For Chinese robotics companies, losing access to the American market, while significant, does not signify a complete halt to their global ambitions. China possesses a massive domestic market that can absorb substantial production volumes, providing a robust base for continued growth and innovation. Beyond its borders, there remains ample room for expansion, particularly in regions experiencing increasing demand for affordable automation and facing severe labor shortages.
Soumen Mandal indicates that Chinese robotics companies are already strategically targeting price-sensitive markets across Europe, Southeast Asia, Latin America, and the Middle East. These regions often prioritize cost-effectiveness and rapid deployment of automation solutions to address demographic shifts and industrial needs. Mandal predicts that humanoid robot manufacturers will likely follow a trajectory similar to that observed with Chinese electric vehicle (EV) companies: building formidable scale within their domestic market, subsequently expanding into diverse overseas markets, and eventually establishing localized production facilities to cater more effectively to regional demands. Countries grappling with labor shortages and demographic decline, particularly in manufacturing sectors, are poised to become early adopters of humanoids, leveraging them for repetitive and physically demanding tasks.
The drone market offers a concrete precedent for this emerging fragmented landscape. Bentzion Levinson, founder and CEO of Virginia-based drone manufacturer Heven AeroTech, observes that the industry is already bifurcating into two distinct ecosystems. One is a U.S.-led market centered on American-made, NDAA-compliant systems, catering to government, defense, and critical infrastructure applications where security and trusted supply chains are non-negotiable. The other is a China-led market, dominant in low-cost, high-volume production, primarily serving consumer and certain commercial sectors.
Levinson concedes that Western manufacturers are unlikely to outcompete Chinese companies in the low-end consumer drone market, where cost remains the overwhelming determinant. Instead, he suggests that U.S. and allied companies should increasingly focus their efforts on advanced applications such as long-range autonomous systems for defense and critical infrastructure, where stringent security requirements and performance specifications hold greater weight.
Looking ahead, Levinson identifies the next competitive frontier as shifting beyond the drones themselves to the underlying technologies that power them and the sophisticated equipment they carry. "The next battleground is over who owns the next-gen energy and payload architecture," he asserts, pointing specifically to battery limitations as a critical area. As drones become more sophisticated and capable, the constraints and innovations in power systems will become an increasingly vital point of competition, determining endurance, payload capacity, and operational efficiency.
The Emergence of a More Regional Robotics Market
The future of the global robotics industry, therefore, appears to be less about a binary U.S.-China divide and more about the emergence of distinct regional markets and diversified supply chains. As Ankur Saxena posits, "The alternative to China isn’t a purely domestic U.S. supply chain; it’s a diversified allied one." This perspective suggests that while the U.S. aims to reduce its dependence on China, it will likely seek to build stronger alliances and foster production capabilities in friendly nations.
This strategic shift creates significant opportunities for other Asian manufacturing powerhouses. Japan, with its decades of experience in industrial robotics and precision manufacturing, stands to benefit. South Korea brings formidable strengths in electronics, batteries, and advanced automotive manufacturing, all crucial components for sophisticated robotics. Taiwan, a global leader in semiconductor fabrication, remains indispensable for high-tech components. However, Saxena cautions that none of these nations can simply replace China’s vast manufacturing capacity and deep integration into global supply chains overnight, underscoring the complexity of decoupling.
Mandal suggests that Asian manufacturers could carve out a valuable "middle ground" between lower-cost Chinese robots and more expensive U.S. offerings. Companies like South Korea’s Hyundai, which owns Boston Dynamics, and Japan’s Toyota are actively investing in robotics, leveraging their extensive expertise in vehicle manufacturing, autonomous systems, and advanced production processes as they venture into the humanoid robot space. Their established supply chains and R&D capabilities could position them as attractive alternatives for markets seeking a balance of quality, innovation, and competitive pricing.
Yang Fang of Beagle Technology, a California-based agtech startup that utilizes AI and robotics software to transform conventional farm equipment into autonomous machines, offers another perspective on regionalization. He told TechCrunch that robotics is inherently likely to become more regionalized as companies design machines specifically tailored to the unique labor needs, working conditions, and customer preferences of their home markets. For example, Chinese robotics companies may continue to focus on products optimally suited for China and nearby Asian markets, leveraging their cost advantages and understanding of regional requirements. Conversely, U.S. companies are more likely to develop solutions for industries across North America, addressing specific challenges such as labor shortages in agriculture or logistics, or advanced defense applications.
In conclusion, the U.S. government’s intensified restrictions on foreign-made advanced robotic systems and drones are catalyzing a profound transformation within the global robotics industry. The outcome is unlikely to be a neatly bifurcated U.S.- and China-led industry. Instead, these measures are accelerating the emergence of diverse regional markets. Chinese companies will likely continue to dominate on cost and scale across much of the world, particularly in price-sensitive markets. U.S. and allied manufacturers will likely solidify their positions in sectors where security, reliability, and advanced capabilities are paramount. Meanwhile, manufacturers in Japan, Taiwan, and South Korea are poised to innovate and expand, seeking to define their own competitive niches in the evolving global robotics landscape. This fragmentation will necessitate new strategies for market penetration, supply chain resilience, and technological collaboration across borders.