For decades, the United Kingdom has served as a strategic hub for global car brands, offering a gateway to European markets and a skilled engineering workforce. However, the current environment has placed volume manufacturers like Toyota, BMW, and Nissan in an increasingly precarious position. As production costs in the UK continue to outpace those in Eastern Europe and China, the financial incentive to maintain large-scale assembly lines in Britain is under greater scrutiny than ever before. For companies that have yet to fully commit their UK facilities to dedicated electric vehicle (EV) architectures, the window for transition is narrowing, and the cost of entry is rising.
The ZEV Mandate and the Regulatory Framework
The cornerstone of the UK’s strategy to decarbonize transport is the ZEV mandate, which became law in early 2024. The policy dictates that a specific, increasing percentage of each manufacturer’s new car sales must be zero-emission. For the 2024 calendar year, the target was set at 22%, rising annually toward a goal of 80% by 2030 and 100% by 2035.
While the mandate was intended to stimulate the market and provide certainty for charging infrastructure providers, it has also created a rigid compliance environment. Manufacturers that fail to meet these percentages face staggering fines of £15,000 per non-compliant vehicle sold. While a "credit trading" system allows laggards to purchase compliance from over-performers (such as Tesla), the underlying economic pressure remains a significant burden on traditional volume manufacturers who rely on internal combustion engine (ICE) or hybrid sales to fund their R&D.
The disconnect between these mandates and consumer uptake has become the primary point of friction. While fleet sales have seen a steady rise in EV adoption, the private retail market has remained sluggish, hampered by high interest rates, a cost-of-living crisis, and a public perception that charging infrastructure has not kept pace with vehicle rollout.
A Tale of Three Manufacturers: Nissan, BMW, and Toyota
The divergent paths taken by the UK’s major car producers illustrate the complexity of the current manufacturing landscape.
Nissan: The Early Mover
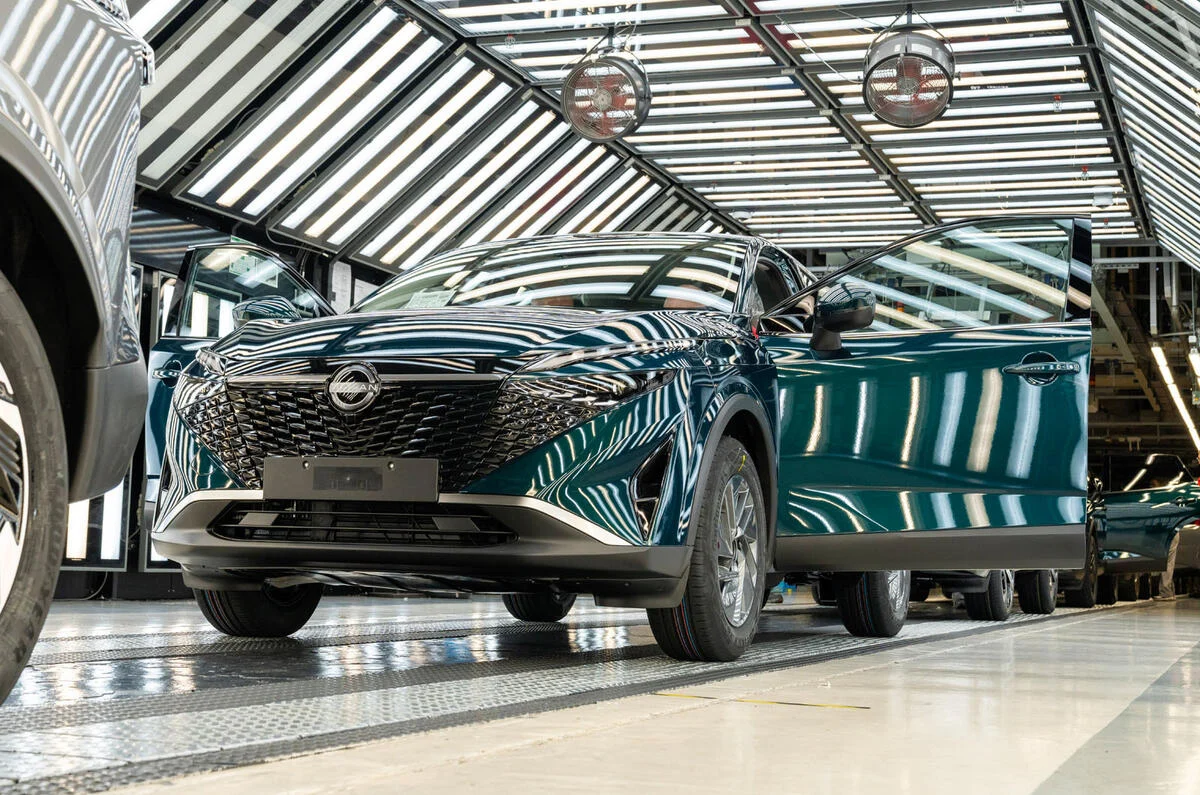
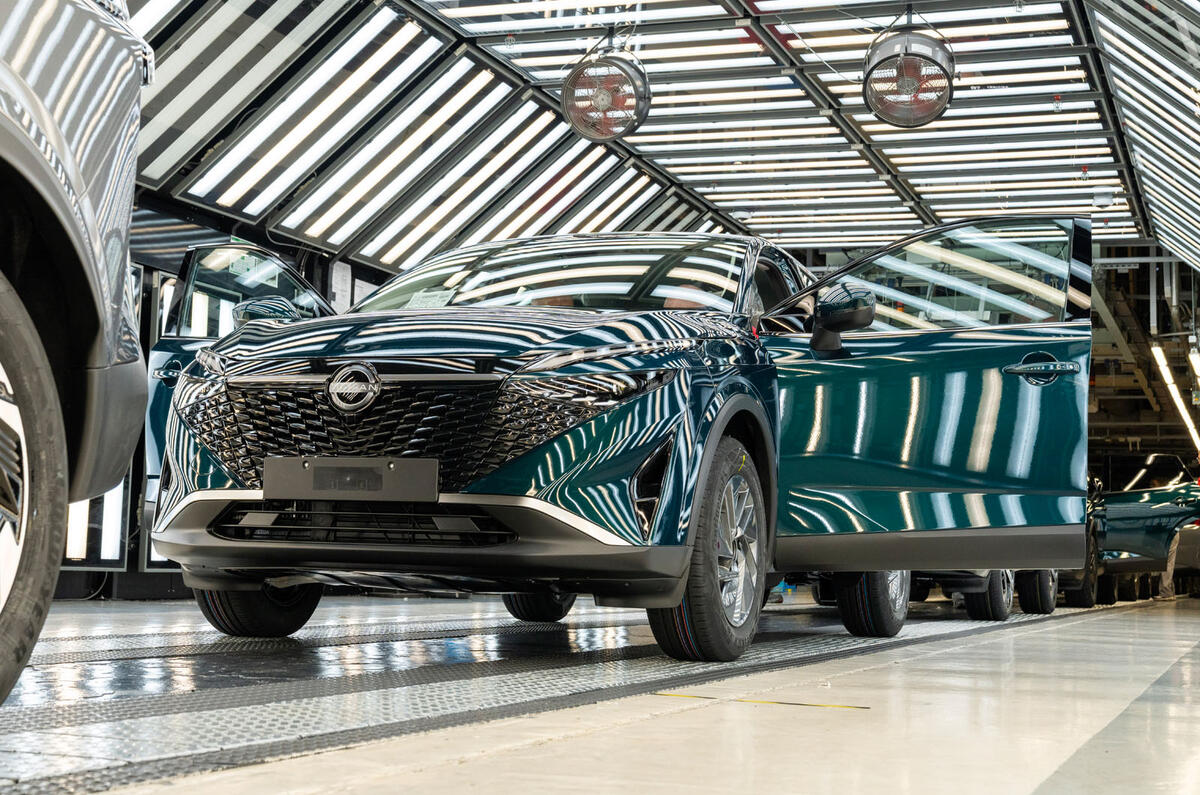
Nissan’s Sunderland plant remains the crown jewel of British automotive manufacturing. Having secured the "EV36Zero" hub project, Nissan has already committed to a multi-billion-pound transformation of the site. This includes the production of electric successors to the Qashqai and Juke, alongside a gigafactory operated by its battery partner, AESC. However, even with this "head start," Nissan faces the challenge of maintaining competitiveness against Chinese imports that benefit from more integrated supply chains and lower energy costs.
BMW (Mini): The Reinvestment Phase
BMW’s Oxford plant, the historic home of the Mini, recently underwent a period of uncertainty before the company announced a £600 million investment to transform the facility for all-electric production by 2030. Previously, production of certain electric Mini models had been shifted to China, raising fears that the UK would lose its status as the brand’s primary manufacturing base. While the return of electric production to Oxford is a victory for UK industry, the transition period requires significant capital expenditure at a time when global margins are being compressed.
Toyota: The Hybrid Specialist
Toyota’s Burnaston facility presents perhaps the most complex challenge for the UK government’s ZEV strategy. The plant is a world leader in hybrid technology, producing the Corolla Hybrid for markets across Europe. However, the UK’s ZEV mandate does not count standard hybrids toward zero-emission targets. This puts Toyota in a difficult position: their current product mix is highly efficient and popular with consumers, but it does not align with the specific regulatory "box" required by British law. Toyota must now decide whether to invest in full-scale BEV (Battery Electric Vehicle) production at Burnaston or shift its manufacturing focus to regions with more flexible regulatory frameworks.
Comparative Economics and the Cost of Production
The decision to build EVs in the UK is no longer just about engineering capability; it is a matter of comparative economics. Several factors have contributed to the "panning out" of the UK’s EV ambitions:
- Energy Costs: Industrial electricity prices in the UK have historically been higher than those in many European competitors and significantly higher than in China. Since battery manufacturing and vehicle assembly are energy-intensive processes, this puts UK-made cars at a price disadvantage from the moment they leave the line.
- Rules of Origin: Post-Brexit trade agreements with the EU include "Rules of Origin" requirements. To avoid a 10% tariff when exporting to the EU, a significant portion of an EV’s value—most notably the battery—must be sourced from the UK or the EU. The slow development of a domestic battery supply chain in Britain has made it difficult for manufacturers to meet these thresholds without relying on expensive European imports.
- Labor and Logistics: While the UK has a highly skilled workforce, the cost of labor and the logistical challenges of a "just-in-time" supply chain operating across the English Channel add layers of complexity and cost that do not exist for manufacturers based within the EU’s single market.
Chronology of the UK’s EV Transition (2020–2026)
- November 2020: The UK government announces a ban on the sale of new petrol and diesel cars by 2030, a target that was at the time one of the most ambitious in the world.
- July 2021: Nissan announces the £1 billion EV36Zero hub in Sunderland, signaling the first major commitment to domestic EV manufacturing.
- January 2023: Britishvolt, the company intended to build the UK’s flagship gigafactory, enters administration, highlighting the fragility of the domestic battery supply chain.
- September 2023: Prime Minister Rishi Sunak announces a delay in the ban of new ICE vehicles from 2030 to 2035, aligning the UK with the EU but causing confusion regarding the ZEV mandate, which remained unchanged.
- January 2024: The ZEV Mandate officially enters into force, requiring 22% of sales to be zero-emission.
- September 2025: Industry data reveals that while EV sales are growing, they are heavily reliant on deep discounting by manufacturers to avoid ZEV mandate fines, further eroding profit margins.
- August 2026: Analysis confirms that the "head start" envisioned in 2020 has been hampered by global competition and high domestic costs, leaving several major UK plants at a crossroads regarding future investment.
Industry Reactions and Official Statements
The Society of Motor Manufacturers and Traders (SMMT) has been vocal about the need for more robust government support. In recent briefings, the organization has emphasized that while the industry is committed to decarbonization, the "stick" of the ZEV mandate must be balanced with the "carrot" of consumer incentives.
"The UK automotive sector is incredibly resilient, but we are operating in a hyper-competitive global environment," an industry spokesperson noted. "Manufacturers need to see a stable market and competitive operating conditions. When the cost of manufacturing in the UK is significantly higher than elsewhere, and the domestic market is being forced faster than consumers are ready to move, it creates a ‘pincer movement’ that threatens long-term investment."
Similarly, representatives from the major manufacturers have called for a more technology-neutral approach. Toyota has frequently argued that hybrids play a vital role in reducing carbon emissions immediately, rather than waiting for the total electrification of the grid and the second-hand car market.
Broader Impact and Future Implications
The failure of the UK to secure an early, undisputed lead in the EV race has broader implications for the national economy. The automotive sector contributes approximately £14 billion to the UK economy and employs over 160,000 people directly in manufacturing. If plants like Burnaston or Oxford were to see reduced investment, the "leveling up" agenda in regions like the Midlands and the North East would face a significant setback.
Furthermore, the rise of Chinese automotive brands in the UK market—such as BYD, MG (owned by SAIC), and Great Wall Motor—presents a new challenge. These companies are able to produce high-quality EVs at a lower cost, often benefiting from state-subsidized supply chains. As they capture more of the UK’s EV market share, domestic manufacturers find it even harder to meet their ZEV mandate quotas through their own production.
Conclusion: The Road Ahead
As the UK moves toward the latter half of the decade, the government and the automotive industry must find a way to reconcile environmental targets with economic reality. The "head start" may not have materialized as planned, but the UK still possesses world-class R&D facilities, a strong motorsport valley, and a legacy of automotive excellence.
To secure the future of volume manufacturing, analysts suggest a multi-pronged approach: reducing industrial energy costs, streamlining the planning process for battery gigafactories, and perhaps introducing more flexible compliance mechanisms for the ZEV mandate that recognize the role of transitional technologies. Without these adjustments, the UK risks becoming a market that consumes EVs produced elsewhere, rather than a powerhouse that builds them. The coming months will be decisive for the boards of Toyota, BMW, and Nissan as they weigh the costs of staying the course in a high-cost, high-regulation Britain.