Marriott International has reported a significant increase in financial performance for the third quarter of 2024, characterized by a substantial rise in gross fees and a robust growth in revenue per available room (RevPAR) that exceeded previous market guidance. The hospitality giant announced that its gross fees climbed 14% to reach $1.52 billion during the quarter, a metric bolstered by an expanding global hotel network and a lucrative surge in revenue from co-branded credit card partnerships. This financial success comes at a delicate time for the corporation, as it navigates a burgeoning dispute with a coalition of hotel owners who are advocating for a more equitable distribution of the profits generated by the company’s loyalty ecosystem.
According to the earnings report released on Monday, Marriott’s net income for the third quarter rose 17% year-over-year, totaling $790 million. Chief Financial Officer Jen Mason highlighted during an earnings call that the company’s co-branded credit card fees are expected to see a full-year increase in the "high 30% range," underscoring the critical role that financial services and data monetization now play in the modern hospitality business model. However, this specific revenue stream has become a primary point of contention. Earlier this year, a group representing hotel owners addressed Marriott’s management in writing, requesting a larger share of the income derived from the loyalty program, specifically citing the fees collected from credit card partners like American Express and JPMorgan Chase.
The Mechanics of Growth: Fees and the Asset-Light Strategy
Marriott’s current financial trajectory is a direct result of its "asset-light" business model, which prioritizes the management and franchising of properties over direct ownership of real estate. By focusing on fees rather than the capital-intensive demands of property maintenance and ownership, Marriott has been able to scale its operations rapidly across the globe. The 14% increase in gross fees to $1.52 billion reflects not only the addition of new rooms to the Marriott system but also the increasing "stickiness" of the Marriott Bonvoy loyalty program.
The $1.52 billion in gross fees is composed of base management fees, incentive management fees, and franchise fees. While base and franchise fees are generally tied to the top-line revenue of the individual hotels, incentive fees are tied to the profitability of the properties. The "solid improvement in hotel margins" cited by CFO Jen Mason suggests that hotel operators are managing costs effectively even as labor and insurance expenses rise, allowing Marriott to capture a higher percentage of incentive-based income.
RevPAR Performance and Market Outperformance
One of the most striking revelations of the third-quarter report was the worldwide RevPAR growth of 6.5% year-over-year. This figure significantly outpaced the company’s own projections from August, which had estimated growth in the range of 3.5% to 4%. This outperformance suggests a more resilient demand for travel than analysts had previously modeled, particularly in the premium and luxury segments.
The growth was not limited to high-end resorts. Marriott’s limited-service hotels—a segment that includes brands like Courtyard by Marriott and Fairfield Inn—recorded their third consecutive quarter of RevPAR gains, rising by more than 6%. This is a critical indicator of the health of the mid-scale market, which often serves as a bellwether for general economic conditions and corporate travel budgets. The strength in this segment indicates that both leisure travelers and business professionals are maintaining their travel frequency despite broader inflationary pressures.
The Conflict Over Loyalty Income
The tension between Marriott and its hotel owners centers on the evolving nature of the "loyalty economy." In the traditional model, hotel owners pay into a fund that supports the marketing and administration of the loyalty program, under the premise that the program drives high-value guests to their properties. However, as Marriott has successfully monetized the Bonvoy brand through co-branded credit cards, the revenue from these financial products has grown exponentially.
Hotel owners argue that because their properties and the service they provide are the primary drivers of the "value" behind the Bonvoy brand, they should receive a portion of the commissions Marriott earns from banks. The owners’ letter sent earlier this year highlighted that while they bear the operational costs of hosting loyalty members—such as providing free breakfasts, room upgrades, and late check-outs—the "ancillary" profits from the credit cards remain largely at the corporate level.
Marriott’s management has historically maintained that the loyalty program provides a competitive advantage that reduces the owners’ reliance on expensive third-party booking sites (Online Travel Agencies or OTAs), thereby saving owners money in the long run. Nevertheless, the high growth rate of these fees—projected to rise nearly 40% this year—has intensified the calls for a "rebate" or a restructuring of the fee hierarchy.
Strategic Portfolio Expansion: The Case of Turtle Bay
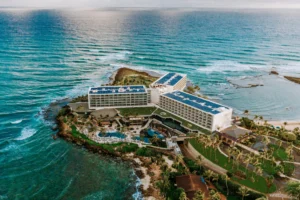
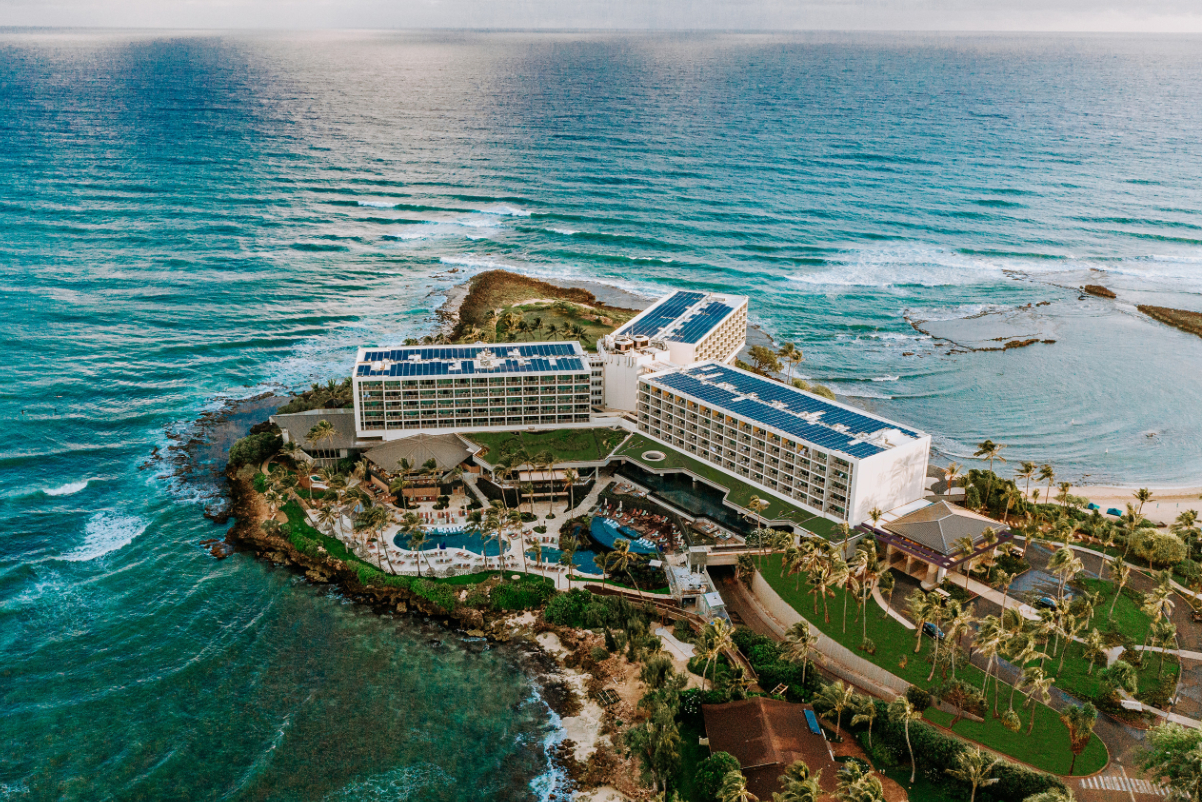
The growth in Marriott’s network is exemplified by high-profile additions and conversions, such as the Ritz-Carlton Oahu, Turtle Bay. The inclusion of such iconic properties into the Marriott portfolio serves a dual purpose: it increases the geographic footprint of the luxury segment and provides a massive draw for Bonvoy members looking to redeem points.
Aerial views of the sprawling peninsula resort in Hawaii highlight the scale of the assets Marriott now manages. By integrating established independent resorts into its system, Marriott provides these properties with immediate access to a global distribution network and a database of over 200 million loyalty members. In exchange, Marriott collects a suite of fees that contribute to the $1.52 billion quarterly total. These conversions are a cornerstone of Marriott’s strategy to maintain a high net-room growth rate without the risks associated with new construction in a high-interest-rate environment.
Chronology of Recent Developments
To understand the current friction and financial success, it is necessary to look at the timeline of the past twelve months:
- Late 2023: Marriott observes a surge in international travel demand, particularly in Asia Pacific and Europe, leading to an aggressive expansion of the Bonvoy program’s digital capabilities.
- Early 2024: A prominent group of hotel owners and franchisees submits a formal inquiry to Marriott leadership regarding the transparency and distribution of credit card-related income.
- August 2024: During the Q2 earnings call, Marriott issues a conservative guidance for Q3, projecting RevPAR growth between 3.5% and 4%, citing potential cooling in the domestic U.S. market.
- September 2024: Strong summer travel performance and a rebound in group and convention bookings provide an unexpected boost to occupancy rates across North America.
- November 2024: Marriott releases Q3 results, shattering its own guidance with 6.5% RevPAR growth and announcing a 17% increase in net income, while simultaneously addressing the "high 30% range" growth in credit card fees.
Broader Implications for the Hospitality Industry
Marriott’s performance is being closely watched by competitors such as Hilton Worldwide and Hyatt Hotels Corporation. The "loyalty-first" strategy pioneered by Marriott has become the industry standard, but the current pushback from owners could signal a shift in the power dynamics of the franchising world. If Marriott reaches a compromise with its owners to share credit card revenue, it could set a precedent that other major hotel chains will be forced to follow.
Furthermore, the data suggests that the "premiumization" of travel is continuing. Despite concerns about a "soft landing" for the global economy, consumers are prioritizing experiential spending. The 6.5% RevPAR growth indicates that travelers are willing to pay higher daily rates, provided the brand promise is met. For Marriott, this means that maintaining the quality of the "guest experience" at the property level is essential to protecting the corporate-level fee structure.
Analytical Outlook: Leveraged Negotiations
The strong Q3 results provide Marriott management with a position of strength in their ongoing talks with hotel owners. With RevPAR beating expectations and hotel margins improving, the company can argue that the current system is functioning optimally for all parties. However, the sheer scale of the credit card revenue—described by Jen Mason as a major growth engine—makes it a difficult target for owners to ignore.
As the company moves toward the end of the fiscal year, the focus will likely remain on whether the 6% growth in limited-service hotels can be sustained and how the company will integrate its recent acquisitions into the broader fee-generating machine. For investors, the 17% rise in net income is a clear signal of efficiency. For hotel owners, however, the 14% rise in the fees they pay to the corporation remains a point of intense scrutiny.
The coming months will determine if Marriott can maintain its record-breaking financial momentum while satisfying the demands of the entrepreneurs and investment firms that own the physical buildings under the Marriott banner. As the hospitality landscape continues to evolve into a hybrid of service and financial technology, the resolution of this fee dispute will likely define the next decade of franchise relations in the travel sector.