A Watershed Moment for the UK Automotive Market
The July registration figures, typically a period of steady but unremarkable growth, showed a startling 19.4% market share for brands headquartered in China. This performance represents more than just a seasonal spike; it is the culmination of a multi-year expansion strategy that has seen brands like BYD, MG, and Chery’s Omoda subsidiary transition from niche players to mainstream contenders.
The primary driver behind this surge is the "value-plus" proposition. Consumers, still navigating the tailwinds of a high-inflation economy, are increasingly prioritizing cost-to-feature ratios. Chinese manufacturers have capitalized on this by offering electrified vehicles—ranging from plug-in hybrids (PHEVs) to battery electric vehicles (BEVs)—at price points that frequently undercut European and American competitors by 15% to 25%. Furthermore, these vehicles often arrive with "all-inclusive" trim levels, including advanced driver assistance systems (ADAS), premium infotainment suites, and heat pumps as standard, features that legacy brands often relegate to expensive optional packages.
Chronology of the Chinese Expansion in the UK
The current dominance of Chinese brands did not occur overnight. It is the result of a calculated, decade-long preparation followed by a five-year execution phase:
- 2021–2022: The MG Vanguard. MG, under the ownership of SAIC Motor, proved that a heritage brand backed by Chinese manufacturing could dominate the affordable EV space. The success of the MG4 EV served as a proof of concept for other Chinese firms.
- Early 2023: The Entrance of BYD. Build Your Dreams (BYD) officially launched in the UK with the Atto 3, followed quickly by the Dolphin and Seal models. Their "Blade Battery" technology, touted for its safety and energy density, became a key marketing differentiator.
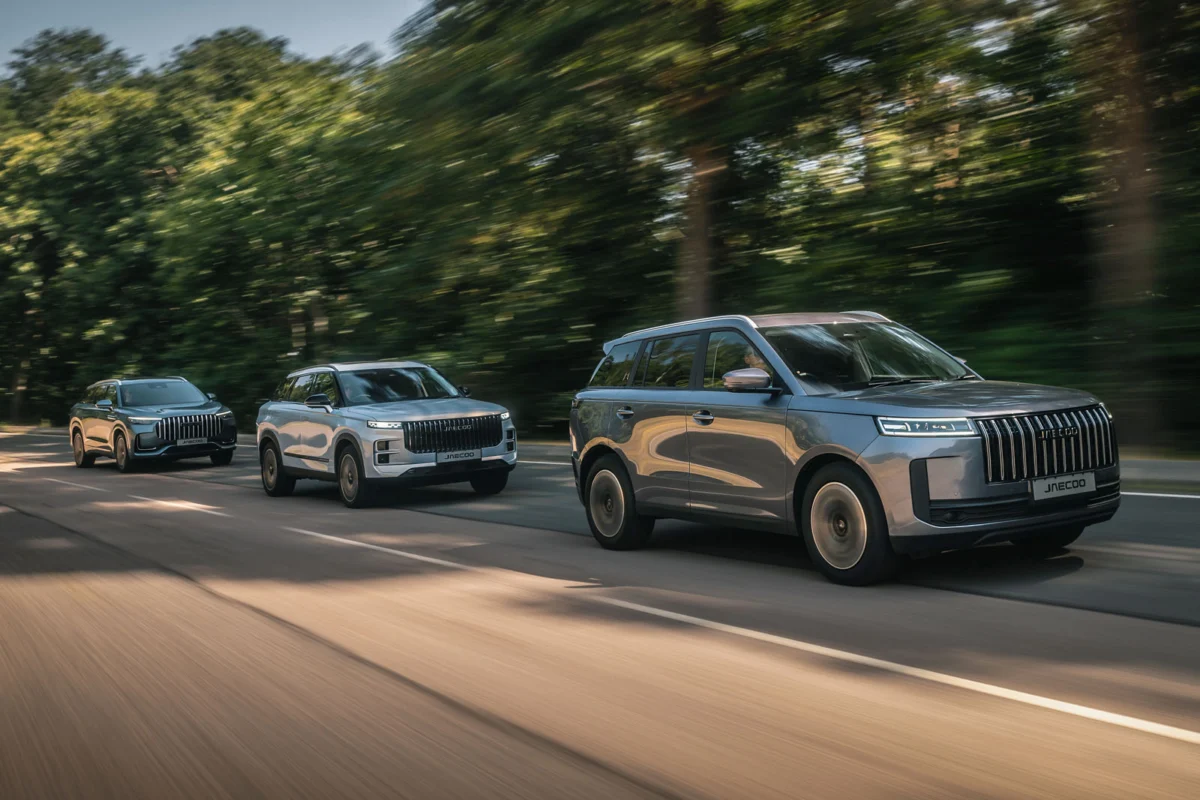
- 2024: Diversification and Dealer Networks. Brands like GWM Ora and Chery (via Omoda and Jaecoo) began establishing traditional physical dealership networks rather than relying solely on direct-to-consumer digital sales. This move built consumer trust and provided the necessary aftersales infrastructure.
- 2025: The ZEV Mandate Pressure. As the UK’s Zero Emission Vehicle (ZEV) mandate increased the required percentage of non-emission sales for all manufacturers, Chinese firms—already producing high volumes of EVs—found themselves in a position to gain market share while legacy firms faced potential fines or expensive credit trades.
- July 2026: The 100,000 Unit Milestone. Omoda-Jaecoo and BYD both reached six-figure cumulative sales, cementing their status as permanent fixtures in the British automotive hierarchy.
Supporting Data: Price and Feature Comparisons
To understand why legacy firms are struggling, one must look at the comparative data. As of mid-2026, the average entry price for a mid-sized electric SUV from a European legacy manufacturer sits at approximately £42,000. In contrast, a comparable model from a Chinese brand, such as the Omoda 5 EV or the BYD Atto 3, is priced between £32,000 and £35,000.

Beyond the initial purchase price, the "equipment gap" is significant. Industry analysts note that to match the standard interior technology and safety sensors found in a base-model BYD Seal, a buyer of a premium German or British executive sedan would need to add between £5,000 and £8,000 in optional extras. This disparity is particularly effective in the fleet and leasing sectors, which account for a large portion of UK registrations, as lower P11D values and high residual value forecasts make Chinese EVs highly attractive for corporate buyers.
The Legacy Manufacturer Dilemma
For established automotive giants like Volkswagen Group, Stellantis, and Ford, the rise of Chinese competitors presents a multifaceted crisis. These "legacy" firms are grappling with several structural disadvantages:
- Supply Chain Vertical Integration: Companies like BYD are vertically integrated, meaning they manufacture their own batteries, semiconductors, and electric motors. Legacy firms, conversely, often rely on complex, multi-tiered global supply chains that add cost and vulnerability to their production lines.
- Legacy Costs: Traditional manufacturers carry the weight of aging factory infrastructure, pension obligations, and the dual-cost of developing internal combustion engine (ICE) technology alongside electric platforms. Chinese firms, many of which started as tech or battery companies, operate with leaner, EV-native cost structures.
- Software Development Speed: The "Software-Defined Vehicle" (SDV) is the new industry standard. Chinese manufacturers are currently iterating software and user interfaces at a pace comparable to smartphone developers, often updating vehicle features over-the-air every few months. European legacy firms have historically struggled with software stability and longer development cycles.
Official Responses and Industry Reactions
The Society of Motor Manufacturers and Traders (SMMT) has noted the shifting tide with a mixture of praise for the market’s growth and caution regarding industrial policy. An SMMT spokesperson recently stated, "The influx of affordable, high-quality electrified vehicles is essential for meeting our decarbonization goals. However, it also highlights the urgent need for a competitive UK industrial strategy that allows domestic and European manufacturers to scale their EV production profitably."
Reaction from dealership groups has been more enthusiastic. "The consumer doesn’t care about the badge as much as they used to," said the CEO of a major UK-wide multi-franchise dealer group. "They care about the monthly PCP payment, the range on a single charge, and the warranty. When a brand like Omoda offers a seven-year warranty and a car that looks like a premium product for two-thirds of the price, it’s an easy sell."
Conversely, European political leaders have expressed concerns regarding the "uneven playing field." The recent implementation of provisional tariffs by the European Union—which the UK has watched closely—aims to counteract what some officials describe as "unfair state subsidies" provided to Chinese automakers. However, analysts suggest that even with tariffs, the cost advantage held by Chinese firms remains significant enough to maintain their competitive edge.

Broader Implications for the UK Economy
The surge in Chinese car sales has implications that reach far beyond the showroom floor. First, there is the impact on the UK’s charging infrastructure. The rapid influx of 100,000+ new EVs from these brands every year is putting immense pressure on the national grid and public charging networks.
Second, there is the question of domestic manufacturing. With brands like BYD and Chery exploring sites for European factories, there is a possibility that the next generation of "British-built" cars could come from Chinese-owned plants, mirroring the way Japanese firms like Nissan and Toyota revitalized the UK car industry in the 1980s.
Finally, the struggle of legacy firms may lead to a consolidation of the market. We are likely to see more "badge engineering" and platform-sharing between European and Chinese firms as a survival tactic. Already, we have seen partnerships where European brands utilize Chinese EV platforms to speed up their time-to-market.
Future Outlook: A New Status Quo
As 2026 progresses, the momentum of Chinese automotive brands shows no signs of slowing. With the UK government’s ZEV mandate tightening each year, the "affordability gap" will become the primary battleground. Legacy manufacturers are at a crossroads: they must either find a way to drastically reduce production costs through radical new manufacturing processes or concede the mass-market segment to Chinese entrants and retreat into the high-margin luxury niche.
For the British consumer, the result is a market with more choices than ever before. However, the long-term health of the UK’s traditional automotive sector remains uncertain as it faces its most significant challenge since the dawn of the motoring age. The July sales figures are not just a statistic; they are a clear signal that the era of Western automotive hegemony is being replaced by a new, electrified global order.