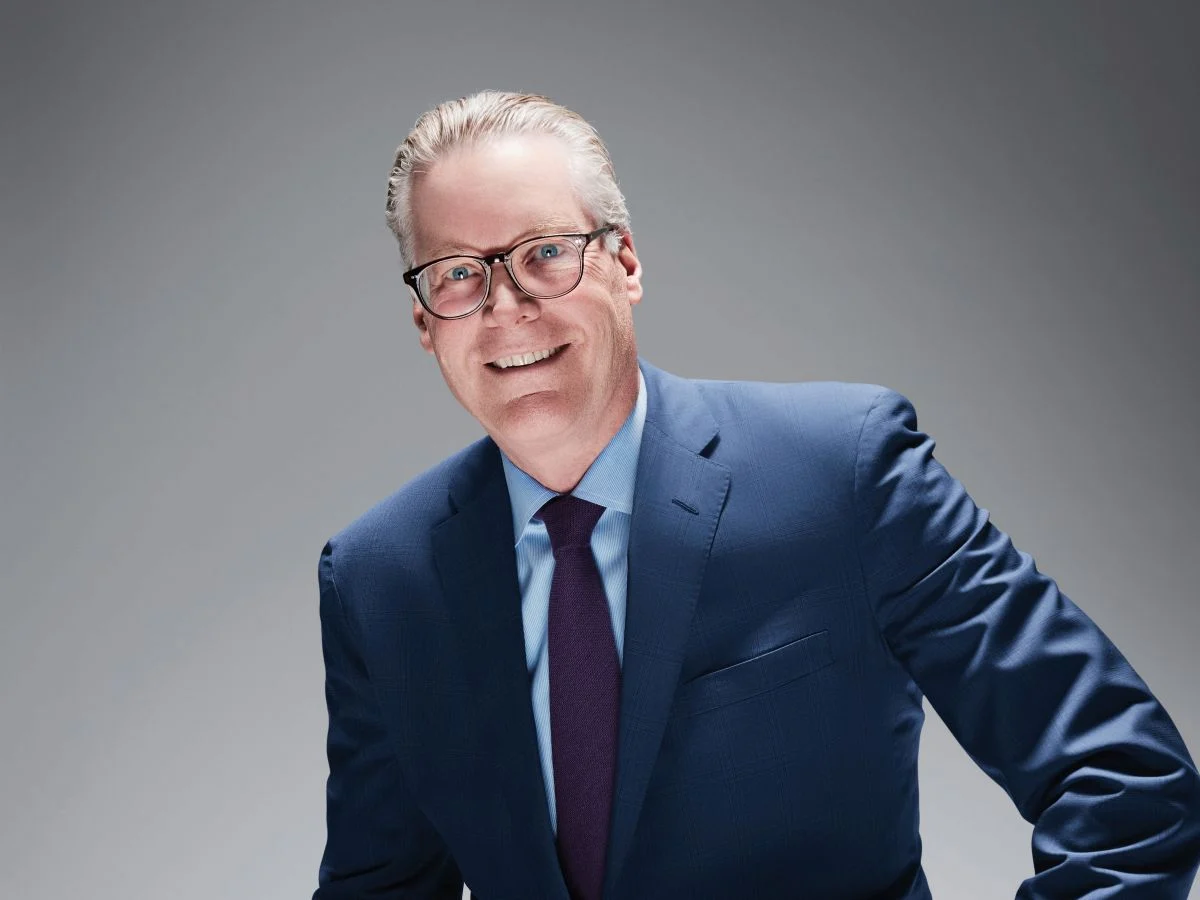
The aviation industry is witnessing a significant escalation in tensions between major carriers and airport infrastructure management as Delta Air Lines Chief Executive Officer Ed Bastian has publicly criticized a proposal by London Heathrow Airport (LHR) to relocate the airline’s operations. In a strongly worded statement released via LinkedIn, Bastian characterized the plan to move Delta from Terminal 3 to Terminal 4 as "short-sighted, deeply disappointing and bad for airline consumers." The move would effectively dissolve the co-location of Delta and its joint venture partner, Virgin Atlantic, ending over a decade of operational synergy at one of the world’s most critical international hubs.
The dispute centers on Heathrow Airport Limited’s (HAL) long-term strategic plan for terminal allocation, which aims to optimize gate usage and passenger flow across its four active terminals. Under the current proposal, Delta would be required to move its operations to Terminal 4 by 2028, while Virgin Atlantic would remain at Terminal 3. This separation would disrupt a partnership that has been a cornerstone of the transatlantic aviation market since Delta acquired a 49% stake in Virgin Atlantic in 2013.
The Strategic Importance of Terminal Co-location
The partnership between Delta Air Lines and Virgin Atlantic is built on the premise of a seamless "metal-neutral" experience for passengers traveling between the United Kingdom and the United States. Since 2013, the two airlines have operated side-by-side in Terminal 3, allowing for synchronized schedules, shared check-in areas, and integrated baggage handling systems.
Bastian emphasized that the co-location in Terminal 3 has served millions of customers by offering convenient connections and access to premium amenities. Central to this premium experience is the Virgin Atlantic Clubhouse and the Delta Sky Club facilities, which are strategically located to serve high-value business travelers. By moving Delta to Terminal 4, which is located on the southern perimeter of the airport and physically separated from Terminal 3 by the airport’s runways, the minimum connection time for passengers transferring between the two airlines would increase significantly.
Industry analysts note that Terminal 4 is often viewed as less desirable for major premium carriers due to its distance from the central terminal area and the Heathrow Express rail links. A relocation would necessitate a transit journey via the Heathrow Cargo Tunnel or the airport’s shuttle systems, adding complexity to the travel ribbon for thousands of daily passengers.
A Chronology of the Delta-Virgin Atlantic Partnership at Heathrow
The relationship between Delta and Heathrow’s Terminal 3 is rooted in a decade of strategic investment and regulatory shifts:
- December 2012: Delta Air Lines announces its intent to purchase a 49% stake in Virgin Atlantic from Singapore Airlines for $360 million.
- June 2013: The United States Department of Transportation (DOT) and European regulators approve the joint venture, allowing the airlines to coordinate schedules and prices.
- 2014-2015: Delta moves the majority of its London operations from Terminal 4 to Terminal 3 to align with Virgin Atlantic. This move was celebrated as a major win for customer convenience.
- 2019: The joint venture expands to include Air France-KLM, creating a powerhouse alliance across the Atlantic with Heathrow as a primary gateway.
- 2020-2022: During the COVID-19 pandemic, Terminal 3 was temporarily closed, and operations were consolidated. As travel recovered, the importance of the T3 hub was reaffirmed by both carriers.
- Late 2023 – Early 2024: Heathrow Airport Limited begins internal consultations regarding "Terminal 4 Refresh" and long-term capacity balancing, leading to the proposal to move Delta back to Terminal 4 by 2028.
Quantitative Impact on Transatlantic Capacity
The proposed move affects one of the most lucrative air corridors in the world. The London Heathrow to New York JFK route is frequently cited as the only billion-dollar route in aviation, and the Delta-Virgin Atlantic partnership holds a substantial share of this market.
Data from aviation analytics firms suggests that Delta and Virgin Atlantic collectively operate up to 40 daily departures from Heathrow during peak seasons. Of these, a significant percentage involves "behind and beyond" traffic—passengers flying from U.S. interior cities via Delta to London, then connecting onto Virgin Atlantic’s network to Africa, the Middle East, or India.
If the relocation proceeds, the "Minimum Connection Time" (MCT), which is a standard metric used by travel agents and booking engines to determine if a connection is sellable, would likely rise from the current 60-90 minutes to 120 minutes or more. This change would make many existing flight combinations "illegal" for booking purposes, forcing a restructure of the airlines’ joint schedules and potentially leading to a loss of market share to competitors like British Airways and American Airlines, who remain consolidated in Terminal 5 and Terminal 3 respectively.
Responses from Stakeholders and Industry Leaders
Ed Bastian’s public intervention follows months of behind-the-scenes lobbying and increasingly public frustration from Virgin Atlantic leadership. Sir Richard Branson, the founder of Virgin Atlantic, has previously voiced his concerns, suggesting that any move to separate the airlines would be a "betrayal" of the investments made by the carriers into the Heathrow ecosystem.
Shai Weiss, CEO of Virgin Atlantic, has also been vocal in his opposition. In previous statements regarding airport infrastructure, Weiss has argued that Heathrow’s primary focus should be on enhancing the consumer experience rather than administrative convenience for the airport operator. The airline leadership views the co-location as a vital competitive tool against the dominance of International Airlines Group (IAG), the parent company of British Airways, which enjoys a near-monopoly on Terminal 5.
Heathrow Airport Limited, for its part, has maintained a more neutral public stance, emphasizing the need for long-term operational efficiency. In statements regarding terminal rebalancing, airport spokespeople have noted that the airport must manage a constrained footprint while accommodating new entrants and ensuring that all terminals are utilized to their maximum capacity. The airport argues that Terminal 4, following recent investments, offers a modern environment that can adequately support international operations.
Competitive Implications and the Oneworld Advantage
The primary beneficiary of a split between Delta and Virgin Atlantic would likely be the Oneworld alliance, led by British Airways and American Airlines. British Airways operates the vast majority of its flights out of Terminal 5, a dedicated facility that provides a seamless experience for its passengers. American Airlines, a key partner of British Airways, operates out of Terminal 3, but the two are linked by sophisticated airside transfer systems and a shared strategic vision for the airport.
By forcing Delta to Terminal 4, Heathrow would create a bifurcated experience for SkyTeam alliance members. While Virgin Atlantic would stay in Terminal 3, Delta passengers would find themselves on the opposite side of the airfield. This geographical split would undermine the "all under one roof" marketing strategy that SkyTeam has promoted at Heathrow. It also raises questions about the future of Air France and KLM at the airport, as they currently operate out of Terminal 4, further complicating the integration with their transatlantic partners in Terminal 3.
Analysis of Economic and Consumer Fallout
From a journalistic and industry-analytical perspective, the conflict highlights a growing rift between "hub-and-spoke" airlines and the airports that host them. Airlines view terminals as strategic assets that define their brand and operational reliability. Airports, conversely, view terminals as infrastructure that must be managed to balance the needs of dozens of different stakeholders, including low-cost carriers, cargo operators, and ground handlers.
For the consumer, the implications are largely negative. The "seamless" travel experience is a major selling point for premium tickets. If a business traveler landing on a Delta flight from Atlanta must clear security and take a bus to another terminal to catch a Virgin Atlantic flight to Delhi, the value proposition of the joint venture is significantly diminished. Furthermore, the cost of relocating ground equipment, staff offices, and maintenance facilities would likely be passed down to the consumer in the form of higher ticket prices or reduced service frequencies.
The Path Forward: Negotiation or Litigation?
The 2028 deadline provides a window for negotiation, but the public nature of Ed Bastian’s criticism suggests that private talks have reached an impasse. Delta and Virgin Atlantic are likely to seek support from the Civil Aviation Authority (CAA), the UK’s aviation regulator, which oversees Heathrow’s pricing and operational standards.
The airlines may argue that the forced relocation constitutes a "discriminatory practice" that unfairly penalizes one alliance to the benefit of another. There is also the possibility of legal challenges if it can be proven that the move violates existing bilateral agreements or the terms of the airport’s operating license.
As Heathrow continues to navigate its post-pandemic recovery and discusses the possibility of a third runway, the resolution of this terminal dispute will serve as a bellwether for the airport’s relationship with its most important international partners. For now, the "Delta-Virgin" hub in Terminal 3 remains under threat, and the rhetoric from Atlanta and Crawley suggests that the airlines are prepared for a protracted battle to maintain their combined home at London’s premier gateway.
The outcome of this dispute will not only affect Delta and Virgin Atlantic but will also set a precedent for how terminal assignments are handled at capacity-constrained airports worldwide. If a major stakeholder like Delta, with its significant financial and operational footprint, can be moved against its will, it signals a shift in the power dynamic between airlines and airport authorities that could resonate across the global aviation industry.