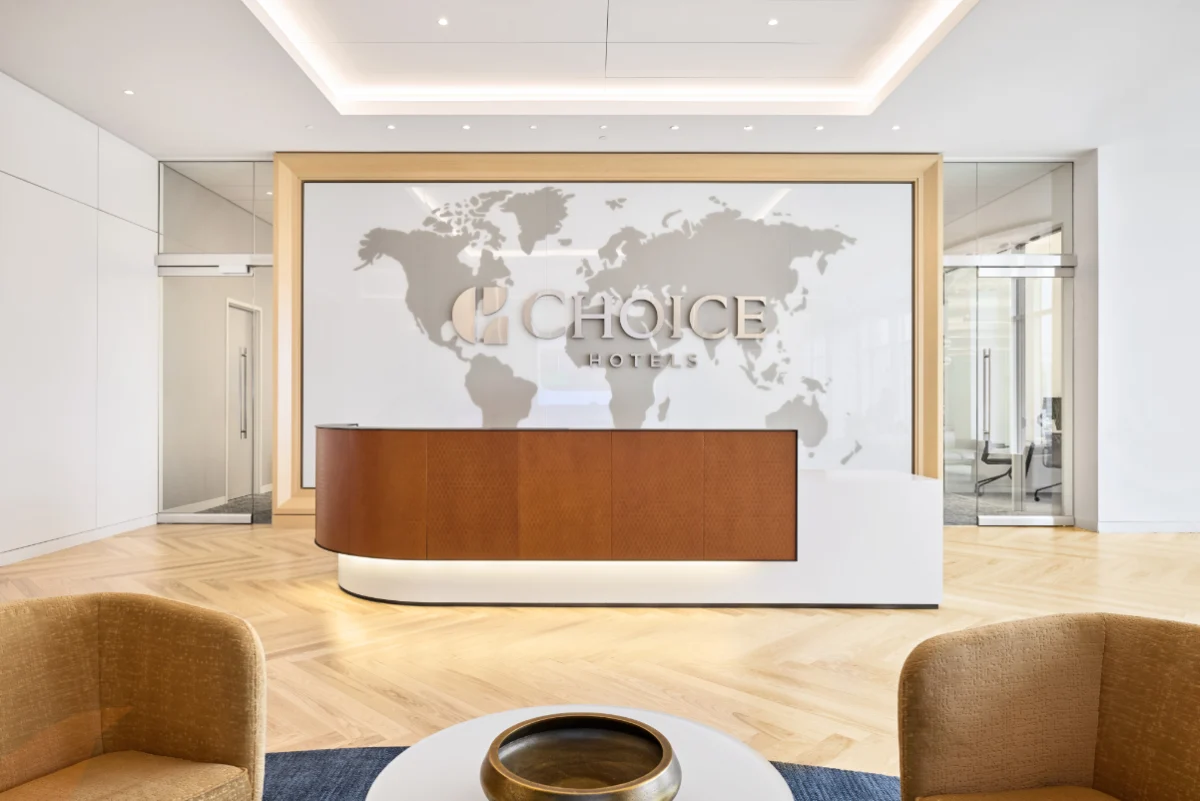
Choice Hotels International has reported a significant shift in its domestic performance metrics, revealing that its budget-friendly brands successfully outpaced broader U.S. industry benchmarks during the critical summer travel season. This development serves as a pivotal indicator of progress for the company’s leadership, specifically Executive Vice President Dominic Dragisich, who has been navigating a complex landscape of post-pandemic recovery and shifting consumer preferences. While the economy and midscale segments of the Choice portfolio showed resilience and growth, the company’s higher-priced, upscale brands continued to face challenges in matching the performance of their direct competitors, albeit with signs of a narrowing performance gap.
The third quarter of the fiscal year provided a clearer picture of Choice Hotels’ standing in the competitive lodging market. Domestic revenue per available room (RevPAR)—a key industry metric that combines occupancy and room rates—grew by 3.8%. This figure was notably impressive as it sat approximately 1.5 percentage points above the consensus forecasts provided by Wall Street analysts. The momentum appeared to carry into the final quarter of the year, with Dragisich noting during a recent earnings call that RevPAR for October reached approximately 7%, signaling a robust start to the autumn season and suggesting that the company’s strategic adjustments are beginning to yield tangible results.
Analyzing the RevPAR Performance and Market Dynamics
The disparity between different segments of the Choice Hotels portfolio remains a central theme for the company’s executive team. In August, data provided by CoStar indicated that Choice trailed behind industry averages in every price tier where it maintains a presence, ranging from the economy sector to the upscale market. This across-the-board lag was a point of concern for investors, as it suggested that Choice was struggling to capture its fair share of the travel rebound compared to other major hotel groups.
However, the third-quarter results demonstrated a meaningful reversal of this trend, particularly within the budget segments. According to analysis from Truist Securities, which utilized CoStar data, Choice’s budget-tier hotels saw RevPAR growth of 3.5%. This outperformed the industry-wide average for the same segment, which hovered around 2.5%. This outperformance in the economy and midscale categories is critical for Choice, as these brands represent the historical core of the company’s franchise model and provide the highest volume of royalty fees.
The upscale segment, however, presents a more nuanced challenge. While Choice’s upscale brands—including Cambria Hotels and the Ascend Hotel Collection—have historically lagged behind the industry average, the third quarter saw a concerted effort to close that distance. Dragisich emphasized during the earnings call that the company had successfully "narrowed the gap," suggesting that while they are not yet leading the upscale market, the trajectory is moving toward alignment with industry norms.
Chronology of Strategic Shifts and Summer Performance
The path to the current financial standing began with a difficult start to the summer. In June and July, inflationary pressures and a shift in consumer spending toward international travel and cruise lines initially softened the demand for domestic budget lodging. Choice Hotels, with its heavy concentration in the U.S. "drive-to" market, felt these headwinds acutely.
By August, the company faced a crossroads. Internal data showed that the portfolio was underperforming relative to the broader market in every category. This prompted a shift in marketing strategy and a renewed focus on the company’s loyalty program, Choice Privileges, to drive direct bookings and increase occupancy during the tail end of the summer.
The turnaround became evident in September, as business travel and local events began to supplement the waning leisure demand. This recovery culminated in the reported 3.8% RevPAR growth for the quarter. The announcement of a 7% RevPAR growth for October serves as a significant milestone, representing a doubling of the growth rate seen in the previous three months. Analysts attribute this October surge to a combination of favorable calendar shifts, a recovery in mid-week business travel, and the successful integration of newly franchised properties into the Choice distribution system.
Supporting Data and Financial Highlights
Choice Hotels’ financial health extends beyond RevPAR. The company’s business model, which relies heavily on franchising fees, benefited from an expansion in its global pipeline. Key data points from the most recent reporting period include:
- Total Revenue: The company saw a steady increase in total revenue, driven by a 2% growth in the number of domestic rooms within the system.
- Adjusted EBITDA: Choice reported adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) that exceeded internal projections, supported by disciplined cost management and higher-than-expected royalty rates.
- Pipeline Expansion: The global pipeline for new hotel developments increased by double digits, with a specific focus on the "conversion" market—existing hotels switching from other brands to Choice.
- Radisson Americas Integration: The company confirmed that the integration of the Radisson Americas portfolio is largely complete, contributing significantly to the upscale segment’s inventory and providing a platform for future RevPAR growth in higher-tier markets.
The performance of the WoodSpring Suites brand, a leader in the extended-stay segment, also remained a bright spot. Extended-stay properties have shown remarkable consistency in the post-pandemic era, often maintaining occupancy levels well above 70% even during seasonal downturns. Choice has leaned into this success by expanding its Everhome Suites and MainStay Suites brands, aiming to capture more of the workforce and long-term relocation market.
Executive Responses and Strategic Vision
During the earnings call, Dominic Dragisich provided context for the company’s performance, acknowledging the competitive pressures while highlighting the strengths of the Choice ecosystem. He pointed to the company’s ability to "narrow the gap" in the upscale segment as a testament to the improved quality of the portfolio following the Radisson acquisition.
"Our focus remains on high-royalty-generating segments," Dragisich stated, according to transcripts of the call. "While the summer presented challenges in the broader economy sector, our brands have shown that they can outpace the benchmark when we leverage our distribution platform and loyalty reach. The October data gives us immense confidence that our value proposition is resonating with both franchisees and guests."
Industry analysts have noted that Choice’s strategy involves a delicate balancing act. On one hand, the company must defend its dominance in the economy and midscale markets against aggressive moves from competitors like Wyndham and Hilton’s new "premium economy" offerings. On the other hand, it must prove to developers that it can successfully operate in the upscale space to attract higher-value contracts.
Broader Industry Implications and Market Outlook
The performance of Choice Hotels serves as a bellwether for the broader U.S. lodging industry, particularly for the mid-market and budget sectors. Several implications arise from the company’s latest data:
- Consumer Value Sensitivity: The outperformance of budget brands suggests that U.S. travelers are becoming increasingly price-sensitive. As household savings from the pandemic era dwindle and interest rates remain elevated, travelers are opting for "value-oriented" stays rather than high-end luxury, benefiting brands like Quality Inn and Comfort.
- The "Conversion" Trend: With the cost of new construction remaining high due to expensive financing and labor shortages, the industry is seeing a surge in "conversions." Choice’s ability to grow its pipeline through conversions rather than new builds is a strategic advantage that allows for faster unit growth and immediate royalty generation.
- Business Travel Recovery: The 7% growth in October RevPAR is a strong indicator that small-to-mid-sized business travel is recovering. Unlike large corporate travel, which remains below 2019 levels for many urban centers, the "blue-collar" and regional business travel that Choice services is proving to be more resilient.
- Technological Competitive Advantage: Choice has invested heavily in its proprietary ChoiceEDGE reservation system. The company’s ability to beat Wall Street forecasts is partially attributed to its sophisticated revenue management tools, which allow franchisees to adjust rates in real-time based on local demand fluctuations.
Looking forward, Choice Hotels faces a landscape defined by moderate RevPAR growth and increased competition for franchisee loyalty. The company’s ability to maintain its lead in the budget sector while simultaneously elevating its upscale brands will determine its stock performance in the coming quarters. Investors will be watching closely to see if the October momentum can be sustained through the holiday season and into the first quarter of the new year.
As the industry moves toward 2025, the focus for Choice Hotels will likely remain on maximizing the value of the Radisson Americas integration and continuing to shift the portfolio mix toward higher-revenue-per-room properties. For now, the third-quarter results provide a narrative of a company that has successfully navigated a turbulent summer to emerge with a stronger, more competitive stance across its diverse range of hotel brands.