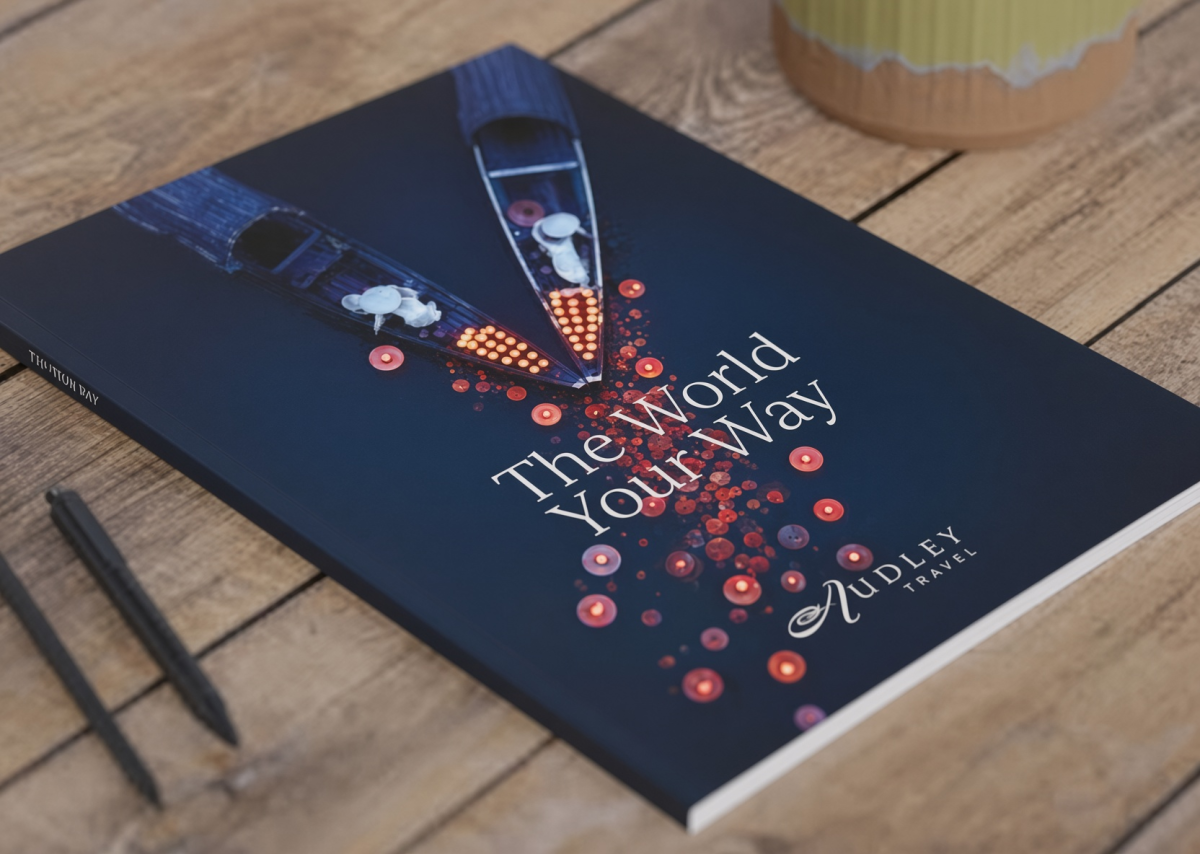
Audley Travel stands as a preeminent figure in the global tailor-made tour operation sector, representing a £482 million ($656 million) enterprise founded upon a business philosophy that currently serves as a central point of debate within the broader travel industry: the utilization of highly compensated human specialists to curate and manage end-to-end travel experiences. While the travel sector at large has increasingly pivoted toward algorithmic recommendations and automated booking systems, Audley Travel has doubled down on its high-touch, expertise-driven model. This strategy has positioned the company at the pinnacle of the luxury travel market, yet its internal financial mechanics have remained largely opaque due to its status as a privately held entity within a sophisticated private equity structure. However, through recent disclosures from its primary stakeholder, the London-listed investment firm 3i, and detailed filings submitted to Companies House, a comprehensive portrait of the company’s financial health, its debt obligations, and its current standing in the global M&A market has finally emerged.
The narrative of Audley Travel is not merely one of luxury itineraries and high-end service; it is a complex case study in private equity longevity and the challenges of exiting a high-performing asset in a volatile economic climate. Having remained under private equity control for nearly 14 years through two successive ownership cycles, Audley Travel has reached a critical juncture. In October 2024, 3i—which holds a 48% equity stake alongside a significant portion of the shareholder debt—initiated the process of exploring a sale, appointing investment bankers to oversee an auction scheduled for early 2025. This move comes at a time when the company is reporting record profits, yet the path to a successful divestment remains obstructed by the very financial structures that facilitated its growth.
The Human-Centric Model in an Automated Era
At the core of Audley Travel’s market proposition is the "country specialist." Unlike traditional travel agencies that offer a broad but often shallow knowledge of global destinations, Audley employs individuals who have lived, worked, or traveled extensively in specific regions. These specialists are tasked with designing bespoke itineraries that cannot be replicated by standard online travel agencies (OTAs). This model relies on a high-cost labor force, where specialists are compensated not just for sales, but for their deep intellectual capital and ability to provide a "concierge-level" service.
The travel industry is currently divided on the sustainability of this model. Proponents argue that as artificial intelligence commoditizes basic travel planning, the value of human expertise and localized "insider" knowledge increases exponentially, particularly for high-net-worth individuals. Critics, however, point to the scalability challenges and the high overhead associated with maintaining a large staff of specialized consultants. Audley’s financial performance suggests that, for now, the premium market is willing to pay the margin required to sustain this human-centric approach. The company’s £482 million revenue figure is a testament to the enduring demand for curated travel, particularly in the post-pandemic era where travelers have shown a heightened preference for security, personalization, and complex multi-destination trips.
A Fourteen-Year Chronology of Private Equity Ownership
To understand Audley Travel’s current position, one must trace its ownership history, which reflects the broader trends of the private equity landscape over the last decade and a half.
- Founding and Early Growth (1996–2012): Founded by Craig Burkinshaw in 1996, Audley Travel began as a niche operator focusing on Southeast Asia. Its success in providing authentic, off-the-beaten-path experiences led to rapid expansion into other territories.
- The Equistone Era (2012–2015): In 2012, the private equity firm Equistone Partners Europe acquired a majority stake in the business. During this period, the company professionalized its management structure and expanded its footprint in the North American market, which would eventually become a primary engine of growth.
- The 3i Acquisition (2015–Present): In December 2015, 3i Group PLC acquired a majority stake in Audley Travel in a deal valued at approximately £159 million. At the time, the move was seen as a bet on the resilience of the luxury "experiential" travel market. 3i maintained a 48% shareholding, with the remainder held by management and other investors.
- The Pandemic Resilience (2020–2022): Like all travel entities, Audley faced an existential threat during the COVID-19 pandemic. However, the company utilized the hiatus to refine its digital infrastructure while retaining its core specialist staff. The subsequent "revenge travel" boom in 2023 and 2024 propelled the company to record-breaking financial heights.
- The Sale Exploration (October 2024): After nine years of ownership—a duration significantly longer than the typical three-to-five-year private equity cycle—3i appointed investment bankers to explore a sale.
Deconstructing the Financial Architecture
The financial disclosures from 3i and the holding companies above Audley reveal a "barbell" economic structure. On one side, the operational business is thriving. The £482 million in revenue is supported by robust margins that are typical of the bespoke travel sector, where markups are justified by the complexity of the service provided.
However, the other side of the barbell reveals the costs of a long-term private equity stay. The ownership structure involves layers of shareholder debt sitting above the equity. This is a common private equity tactic used to optimize tax efficiency and ensure that the parent firm (3i) receives interest payments even if dividends are not declared. While this structure is standard, its accumulation over 14 years has created a complex "capital stack" that any potential buyer must navigate.
The accounts filed at Companies House indicate that while Audley is producing record operational profits (EBITDA), a significant portion of its cash flow is diverted to servicing the debt and the structural costs of its ownership. This creates a paradox: the business is more successful than ever in terms of customer satisfaction and top-line growth, yet its valuation is complicated by the financial engineering of the past decade.
The Auction of 2025: Challenges and Opportunities
The decision to move toward an auction in early 2025 is a strategic gamble. The luxury travel M&A market has seen several notable transactions, such as the acquisition of Scott Dunn by Flight Centre Travel Group for £121 million in early 2023. These deals suggest there is an appetite for high-end operators, but Audley’s scale makes it a much larger target, potentially limiting the pool of buyers.
Several factors will influence the success of the 2025 auction:
- Valuation Gaps: 3i will likely seek a valuation that reflects Audley’s status as a market leader and its record-breaking recent performance. However, strategic buyers (such as larger travel conglomerates) and other private equity firms may be cautious about the high multiples often demanded for "trophy" assets in a high-interest-rate environment.
- The Debt Burden: The shareholder debt sitting above the equity must be addressed. A buyer would likely need to refinance this debt, and the cost of new capital in 2025 may be significantly higher than when 3i first structured the deal in 2015.
- Market Saturation vs. Growth Potential: While Audley has a strong presence in the UK and the US, a buyer will look for "white space." Further expansion into the Middle East or Asia-Pacific markets could be a selling point, but these regions present different operational challenges for the tailor-made model.
- The "Key Person" Risk: The model’s reliance on human specialists is its greatest strength but also a potential risk. A buyer must be convinced that the culture of expertise is institutionalized and not dependent on a few key executives or a specific cohort of specialists who might leave post-acquisition.
Statements and Market Sentiment
While official statements from 3i have remained focused on the "resilience and quality" of the Audley asset, industry analysts suggest that the extended holding period is a sign of the difficulties inherent in exiting large-scale luxury travel businesses. "Audley is a jewel in the crown of the UK travel industry," noted one M&A consultant specializing in leisure and tourism. "But it is a large jewel, and the number of people with deep enough pockets to buy it—while also being comfortable with a model that resists automation—is relatively small."
Internally, Audley’s leadership has consistently messaged a "business as usual" approach, focusing on the quality of the itineraries and the training of their staff. The upcoming auction is viewed not as a sign of distress, but as the natural conclusion of 3i’s investment lifecycle.
Broader Implications for the Travel Industry
The outcome of the Audley Travel sale will serve as a bellwether for the entire luxury travel sector. If 3i achieves its target valuation, it will validate the human-centric, high-margin model of tailor-made travel. It would signal to the market that even in an age of AI, there is a substantial and profitable niche for expert-led services.
Conversely, if the auction fails to attract a buyer or results in a lower-than-expected price, it may prompt a re-evaluation of the "specialist" model. It could lead to pressure on other operators to incorporate more technology and reduce labor costs to make their businesses more "exit-friendly" for private equity investors.
Furthermore, the Audley situation highlights the "exit bottleneck" currently facing many private equity firms. With hundreds of companies held past their intended exit dates due to the economic disruptions of the past four years, the market is watching closely to see how 3i navigates the sale of a high-performing but complex asset.
As 2025 approaches, the travel industry and the financial world alike will be focused on Audley Travel. The company represents a rare intersection of traditional craftsmanship in service and modern private equity finance. Whether it finds a new home with a strategic giant or another private equity house, its journey offers profound insights into the value of expertise in a digital world and the enduring complexity of the luxury travel market.