Awaze, the preeminent vacation rental property manager in Europe, has released its annual financial report for 2025, revealing a complex fiscal landscape defined by strategic pricing trade-offs and looming debt obligations. The group, which oversees a portfolio of high-profile brands including Cottages.com, Hoseasons, and Novasol, reported a significant 20% increase in adjusted EBITDA (earnings before interest, taxes, depreciation, and amortization) and a marked narrowing of its net losses. However, these gains were offset by a 1.3% slip in net revenue, which fell to €378 million ($511 million), alongside a shrinking cash position and a transition into a net liability status. This financial profile emerges at a critical juncture as the company prepares for a major debt refinancing scheduled for 2028.
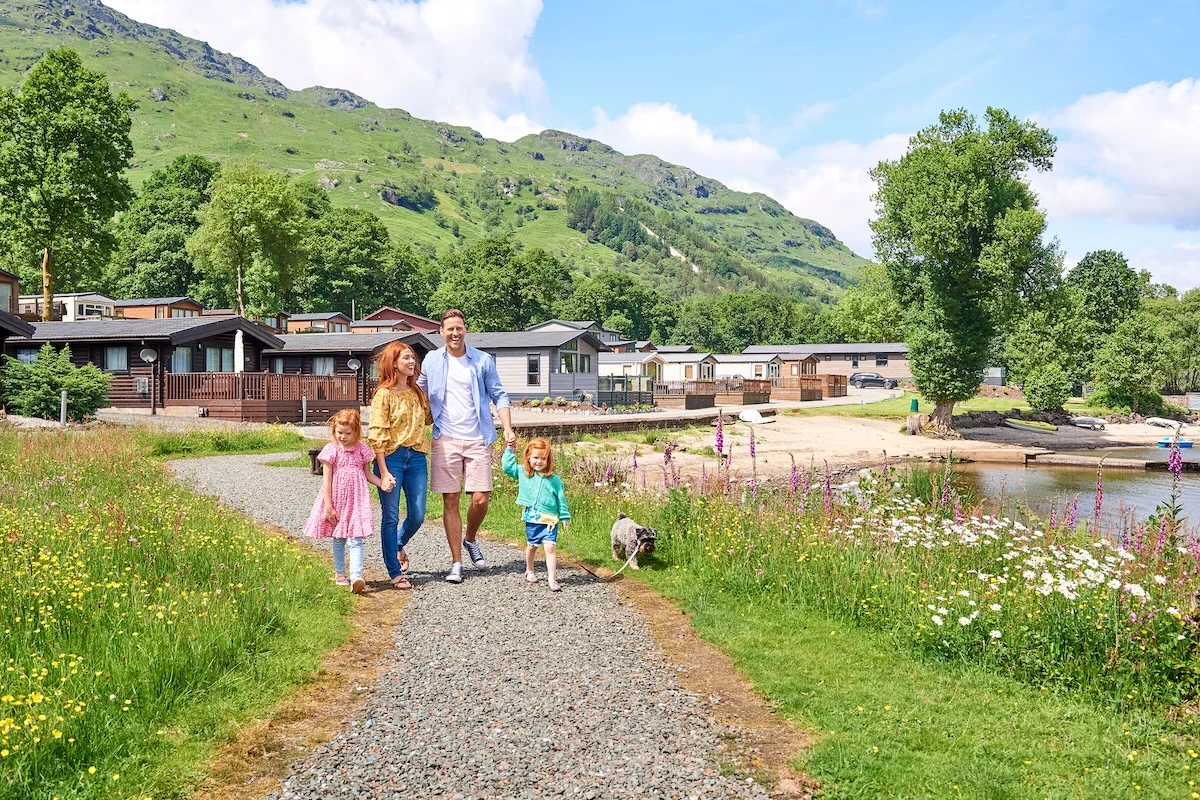
The 2025 fiscal year was characterized by a deliberate management decision to prioritize occupancy and customer loyalty over aggressive price increases. Amidst a persistent cost-of-living crisis across major European markets, Awaze opted to hold rental rates relatively flat. The strategy was designed to capture the "staycation" market, enticing travelers to forgo expensive long-haul flights in favor of domestic or regional destinations, such as the rugged coastlines of Cornwall or the serene cabins of the Danish coast. While this move successfully maintained high occupancy levels and bolstered the company’s direct-booking ecosystem, it constrained top-line revenue growth during a period of inflationary pressure on operational costs.
Strategic Pricing and the Occupancy Bet
The decision to maintain flat pricing was a calculated risk aimed at securing market share in a fragmented and increasingly competitive industry. By positioning its properties as high-value alternatives to traditional hotels and international travel, Awaze sought to insulate itself from the volatility of discretionary spending. According to the internal report, this strategy yielded positive results in terms of consumer engagement. Direct bookings remained robust at 72%, a metric that is vital for reducing reliance on third-party online travel agencies (OTAs) and preserving margins.
Furthermore, more than half of the guests recorded in 2025 were repeat customers, suggesting that the value proposition resonated with the company’s core demographic. CEO Matthew Price attributed the growth in adjusted EBITDA to the company’s internal efficiencies and the successful integration of its various brand platforms. By streamlining administrative functions and leveraging a unified technology stack, Awaze was able to extract higher earnings from a slightly smaller revenue base.
However, the 1.3% decline in net revenue highlights the limitations of the flat-pricing model. In a year where many competitors in the broader travel sector raised prices to counteract rising labor and energy costs, Awaze’s revenue contraction suggests that volume gains were not quite sufficient to overcome the lack of price growth. This tension between volume and value remains a central theme for the group as it enters the 2026 booking season.
Financial Performance and Net Liability Concerns
The most pressing concern for analysts and stakeholders lies in the company’s balance sheet. While the narrowing of net losses is a positive indicator of a path toward profitability, the shift into a net liability position reflects the heavy debt burden typical of private equity-backed enterprises. Awaze is currently owned by Platinum Equity, which acquired the business from Wyndham Worldwide in 2018 for approximately $1.3 billion.
The 2025 report indicates that the group’s cash reserves have shrunk, a development that reduces the company’s financial "dry powder" for further acquisitions or emergency capital expenditures. With a 2028 refinancing deadline approaching, the company must demonstrate sustained earnings growth to secure favorable terms from lenders. The transition to net liabilities—where total liabilities exceed total assets—often signals to the market that a firm is highly leveraged and sensitive to interest rate fluctuations.
For Awaze, the path to the 2028 refinancing will require a delicate balancing act: maintaining the operational efficiency that drove the 20% EBITDA increase while finding ways to reinvigorate revenue growth without alienating its cost-conscious customer base.
A Chronology of Restructuring and Market Evolution
To understand Awaze’s current position, it is necessary to examine the timeline of its operational evolution over the last several years. Since the 2018 acquisition, the group has undergone a massive digital transformation, moving away from a decentralized collection of local brands toward a centralized, tech-driven powerhouse.
- 2018–2020: The Integration Phase. Following the carve-out from Wyndham, the group rebranded as Awaze. The primary focus was on consolidating the technology behind Hoseasons and Cottages.com in the UK and Novasol in mainland Europe.
- 2021–2022: The Pandemic Surge. The "staycation" boom during the COVID-19 pandemic provided a significant tailwind. Demand for private, self-contained holiday homes skyrocketed, allowing the company to shore up its market position.
- 2023: Portfolio Optimization. In late 2023, Awaze made the strategic decision to shutter James Villas, a well-known brand specializing in Mediterranean villa holidays. This move was intended to streamline operations and focus resources on the core property management and agency business. The closure contributed to the revenue fluctuations seen in the subsequent 2024 and 2025 cycles.
- 2024–2025: The Affordability Crisis. The group pivoted to its current strategy of price restraint to combat the impact of high inflation and interest rates on European households.
Regional Performance: UK and Scandinavia
The performance of Awaze’s regional brands provided a mixed picture of the European travel market. In the United Kingdom, Hoseasons and Cottages.com remained the dominant players in the domestic rental sector. The UK market, however, has been particularly sensitive to energy price hikes and mortgage rate increases, which squeezed the disposable income of the middle-class families that form Awaze’s primary customer base.
In Scandinavia and Northern Europe, the Novasol brand continued to leverage its massive inventory of traditional holiday homes. The Danish coast, mentioned specifically in the CEO’s commentary, remained a resilient destination for German and Dutch travelers seeking nature-based, socially distanced vacations. The stability of the Northern European market acted as a buffer against the more volatile economic conditions in Southern Europe and the UK.
Sector Analysis: The Competitive Landscape
Awaze operates in a space that is increasingly squeezed between global tech giants like Airbnb and Booking.com and localized, boutique rental agencies. While Airbnb has historically focused on urban apartments and individual hosts, it has recently made inroads into the professional vacation rental market—Awaze’s home turf.
The competitive advantage for Awaze lies in its end-to-end management services. Unlike Airbnb, which is primarily a marketplace, Awaze brands often handle property maintenance, cleaning, and local support, providing a level of quality assurance that appeals to older demographics and families. However, maintaining this infrastructure is capital-intensive, contributing to the higher overhead costs that the company has been working to trim.
Industry analysts suggest that Awaze’s 72% direct booking rate is an industry-leading figure. By keeping customers within its own ecosystem, the company avoids the 15% to 20% commission fees typically charged by global distribution platforms. This direct relationship is the cornerstone of the company’s strategy to improve its margin profile ahead of its debt maturity.
Future Outlook and Refinancing Implications
Looking toward 2026 and the 2028 refinancing horizon, Awaze faces several critical questions. The first is whether the "flat rate" strategy can be sustained if inflation remains sticky. At some point, the company may be forced to raise prices to cover rising labor costs for cleaning and maintenance staff, which could test the loyalty of its repeat customers.
The second question involves the group’s capital structure. With net liabilities on the rise, the company may need to consider asset sales or a further injection of equity from Platinum Equity to improve its leverage ratios. The 2028 refinancing will likely take place in a very different interest rate environment than the original acquisition financing, potentially leading to higher debt-servicing costs.
The broader implications for the European vacation rental market are significant. As the largest player, Awaze’s health is often seen as a bellwether for the industry. If the group can successfully navigate its current financial squeeze by leveraging its massive scale and direct-to-consumer reach, it will provide a blueprint for other leveraged travel firms. If, however, the revenue slip continues, it may signal a cooling of the post-pandemic travel boom.
Conclusion
Awaze’s 2025 results represent a snapshot of a company in transition. By prioritizing operational efficiency and customer retention, management has managed to improve earnings even as the top-line revenue faced headwinds. The sharp narrowing of losses suggests that the core business model remains viable and that the restructuring efforts of the past few years are bearing fruit.
Nevertheless, the shadow of the 2028 refinancing looms large. The group’s ability to reverse the trend of shrinking cash and manage its net liability position will be the true test of its long-term stability. For now, Awaze remains a dominant force in European travel, betting that its deep roots in the "staycation" market will provide the resilience needed to weather the ongoing economic storm. Travelers in the UK and Europe continue to show a strong preference for the reliability of managed holiday homes, and as long as Awaze can maintain its value proposition, it remains well-positioned to lead the sector—provided it can successfully manage the complexities of its balance sheet.