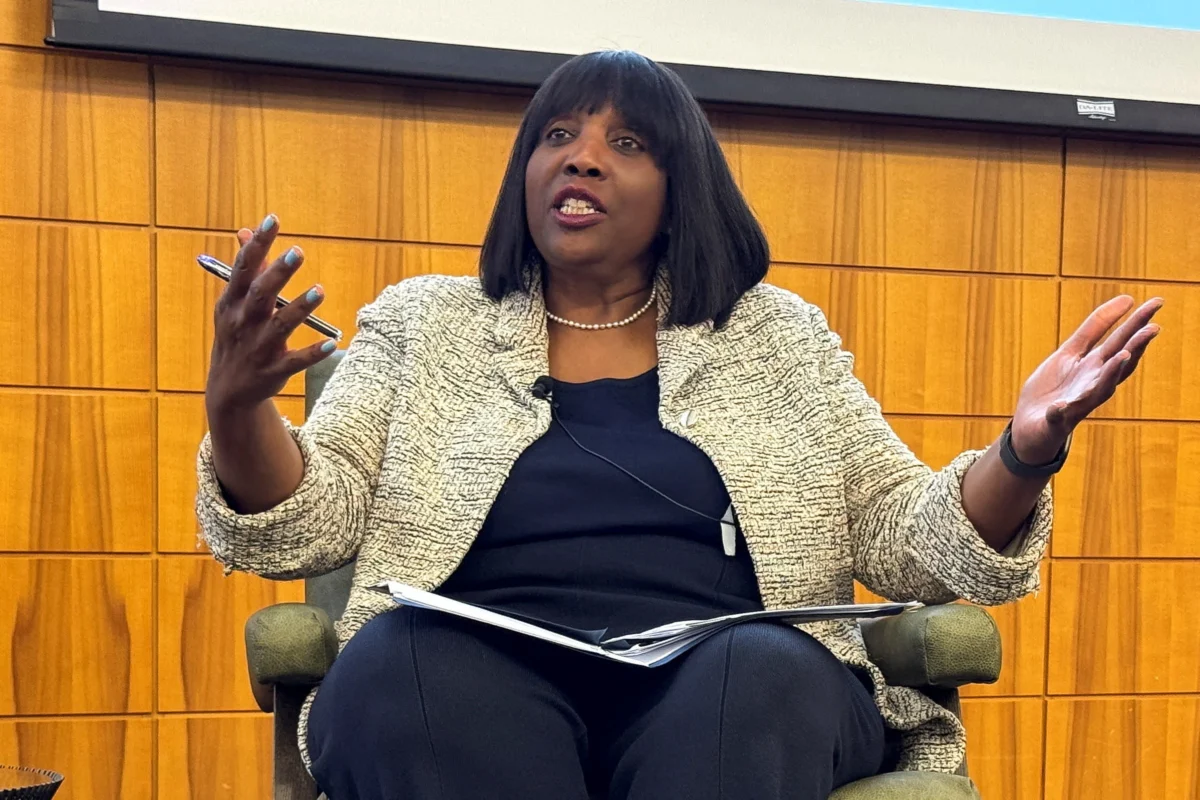
Federal Reserve Governor Lisa Cook announced on Wednesday her readiness to support an increase in the benchmark interest rate unless a decisive and sustained improvement in inflation figures materializes. Her remarks, delivered during a speech in Anchorage, Alaska, underscored the central bank’s unwavering focus on price stability, even as economic growth shows signs of deceleration. Cook’s stance adds a hawkish tone to the ongoing debate within the Federal Open Market Committee (FOMC) regarding the appropriate path for monetary policy in the face of complex economic crosscurrents.
A Clear Warning on Inflation Risks
"Inflation is too high, and I consider the risks to the inflation side of the dual mandate higher than the risks to the employment side at this point," Cook stated unequivocally, referencing the Fed’s congressionally mandated goals of maximum employment and price stability. "As such, I am prepared to act by raising rates, if necessary." This direct communication signals a growing impatience with the current pace of disinflation and suggests a leaning towards more aggressive action if forthcoming data does not align with the Fed’s objectives. Her emphasis on inflation risks outweighing employment risks highlights a critical pivot in the Fed’s assessment, indicating that the current labor market, despite some cooling, is still considered robust enough to withstand tighter monetary conditions. As of July 2026, the national unemployment rate stood at 4.0%, a figure still near historical lows, reinforcing the argument that the labor market retains significant strength.
Cook acknowledged the recent June data, which indicated some easing in headline inflation, thanks in large part to a sharp decline in energy prices. The Consumer Price Index (CPI) for June registered a 3.8% annual increase, a notable moderation from the 4.5% seen in May. However, the policymaker cautioned against over-interpreting a single data point, particularly given that the pace of price increases, especially core inflation, continues to run well ahead of the Fed’s long-term 2% target. Core CPI, which strips out volatile food and energy components, remained stubbornly high at 3.3% in June, reflecting more entrenched inflationary pressures across various sectors of the economy. This persistent gap between actual inflation and the target underscores the Fed’s dilemma: balancing the need to tame prices without inadvertently stifling economic growth.
Chronology of Recent Fed Actions and Economic Context
Cook’s Wednesday remarks come on the heels of a closely watched Federal Open Market Committee meeting last week, on July 29, where the central bank opted to maintain its benchmark borrowing rate in a range between 3.5% and 3.75%. This decision, supported by a 9-3 majority vote, marked a pause after a series of aggressive rate hikes initiated in early 2022 to combat surging inflation. Governor Cook was part of this majority, explaining that her vote stemmed from a desire to allow more time for recent policy tightening to filter through the economy and to assess the evolving impacts of several key factors influencing prices.
The journey to the current rate range began in March 2022, following a period where interest rates had been near zero since the onset of the COVID-19 pandemic. The initial surge in inflation was driven by a combination of robust fiscal stimulus, unprecedented consumer demand, and severe supply chain disruptions. Geopolitical events, such as the conflict in Ukraine in early 2022, further exacerbated energy and food price pressures globally. The Fed responded by embarking on its most aggressive tightening cycle in decades, raising rates at successive meetings to curb demand and bring inflation back under control. By the end of 2025, the federal funds rate had reached its current level, reflecting a significant shift from the accommodative policies of the pandemic era.
The economic backdrop to Cook’s current assessment includes a noticeable slowdown in growth. The U.S. economy expanded at an annualized rate of just 1.5% in the second quarter of 2026, a deceleration from the 2.2% growth observed in the first quarter. While this slowing growth suggests that past rate hikes are indeed having an effect, it also complicates the Fed’s task, raising concerns about the potential for a "hard landing" or recession if monetary policy becomes too restrictive.
Elaborating on Influencing Factors
In her Anchorage speech, Cook elaborated on the specific factors she wished to observe before committing to another rate hike. These included "possibly waning impacts from tariffs," an "energy supply shock due to the Iran war," and "pressures from the artificial intelligence buildout." Each of these elements represents a significant and complex driver of contemporary inflation.
The "waning impacts from tariffs" refers primarily to the trade policies enacted in the late 2010s, particularly those imposed on goods imported from China. While some of these tariffs have remained in place, their initial inflationary impulse, stemming from increased import costs, may be diminishing as supply chains adapt or as companies absorb some of the costs. However, the lingering effects on global trade flows and domestic production costs remain a subject of debate among economists. If the disinflationary effect from these tariffs truly begins to materialize, it could provide some relief to overall price pressures.
The "energy supply shock due to the Iran war" points to a critical geopolitical development impacting global commodity markets. A hypothetical conflict involving Iran would almost certainly disrupt oil production and shipping lanes in the Middle East, leading to a significant spike in crude oil prices and, consequently, gasoline, transportation, and industrial costs worldwide. Such an event would present a severe challenge to central banks, as energy shocks are often supply-side driven and less responsive to demand-cooling measures like interest rate hikes. Cook’s mention of this factor suggests the Fed is keenly aware of external, non-monetary risks that could derail disinflationary progress.
Finally, "pressures from the artificial intelligence buildout" highlights a newer and more technologically driven inflationary force. The rapid expansion of AI infrastructure requires massive investments in specialized chips, data centers, and highly skilled labor. This surge in demand can drive up prices for semiconductors, computing power, and wages for AI engineers and researchers. Furthermore, the energy consumption of large AI models is substantial, potentially contributing to higher electricity prices. While AI is often touted for its long-term productivity-enhancing potential, in the short to medium term, the sheer scale of its buildout could create demand-side inflationary pressures in specific sectors, adding another layer of complexity to the inflation outlook.
The Risk of Entrenched Inflation
Cook underscored the urgency of addressing persistent price increases, warning that "if I do not see signs of continued disinflation soon, I am prepared to act." Her concern stems from the risk that higher inflation could become "entrenched in price- and wage-setting behavior." This phenomenon, often referred to as a wage-price spiral, occurs when workers demand higher wages to offset rising living costs, and businesses, in turn, raise prices to cover increased labor expenses, creating a self-reinforcing cycle.
"With five years of above-target inflation, the risk grows that higher inflation may become entrenched," Cook emphasized. This period, stretching back to late 2021/early 2022 when inflation first surged significantly above the 2% target, represents a prolonged departure from price stability. The longer this situation persists, the greater the likelihood that inflation expectations among consumers and businesses become unanchored. If people expect prices to continue rising rapidly, they adjust their economic decisions accordingly, making it much harder for the central bank to restore price stability without triggering a more severe economic downturn. "The longer inflation is above target, the more likely this scenario becomes," she warned, highlighting the diminishing window for a relatively benign resolution.
Other economic environments might afford the Fed the luxury of waiting longer before taking action, Cook conceded, but she firmly stated, "We do not have that luxury in this one." This statement reflects the unique combination of persistent inflation, geopolitical risks, and structural economic shifts that characterize the current landscape. The potential for entrenched inflation, coupled with external shocks, means the cost of inaction could be substantially higher than the cost of a pre-emptive, albeit potentially unpopular, rate hike.
Market Reactions and Dissenting Views
Financial markets have been closely monitoring Fed communications for clues on the future trajectory of interest rates. According to the CME Group’s FedWatch tool, markets currently expect the central bank to potentially act as soon as September, though higher odds are being priced in for an October move. This reflects the prevailing uncertainty and the data-dependent approach the Fed has adopted. Investors are grappling with the implications of continued tightening, which could impact everything from corporate earnings to consumer borrowing costs.
Cook’s hawkish tone resonates with views expressed by other members of the FOMC. Just a day prior to her speech, on August 5, Minneapolis Fed President Neel Kashkari, one of the three dissenting votes at the July FOMC meeting, reiterated his belief that higher rates are still necessary. Kashkari, known for his more hawkish leanings, told CNBC that he favored an immediate rate hike, arguing that the time for gradual action had arrived. His dissent highlighted a segment of the committee that believes the Fed has already waited long enough and should be moving proactively to bring inflation down to target, even at the risk of further slowing economic growth.
The split within the FOMC reflects the challenging trade-offs inherent in current monetary policy. While a majority, including Cook, opted for a pause in July to assess incoming data, the sentiment among some members is clearly shifting towards renewed tightening if disinflationary trends do not accelerate.
Broader Economic Implications and Outlook
A potential rate hike by the Federal Reserve would carry significant implications across the U.S. and global economies. For consumers, it would translate into higher borrowing costs for mortgages, auto loans, and credit card debt, potentially dampening consumer spending and demand for housing. Businesses would face increased costs for financing investments and operations, which could impact hiring decisions and capital expenditure plans.
The Fed’s ultimate goal is to achieve a "soft landing," where inflation is brought under control without triggering a recession. However, the path to a soft landing is narrow, and the risk of over-tightening, leading to a significant economic downturn, remains a persistent concern. Cook’s remarks underscore the Fed’s commitment to its price stability mandate, even if it means accepting some economic pain in the short term to avoid the more severe consequences of persistent, high inflation. The central bank is navigating a complex landscape where traditional economic models are being challenged by unique supply-side shocks, geopolitical instability, and emerging technological shifts.
As the economy moves closer to the next FOMC meeting, scheduled for mid-September, all eyes will be on upcoming inflation reports, labor market data, and other economic indicators. Governor Cook’s firm stance suggests that the threshold for avoiding another rate hike is becoming increasingly high, placing the burden squarely on the shoulders of incoming data to demonstrate a clear and sustained return to price stability. The stakes are high, and the Fed’s decisions in the coming months will profoundly shape the economic trajectory for years to come.